 Oct 18, 2026
Hidden Markov Model Against the VIX on a Regime-Aware Factor Portfolio Comparison
Steered by the VIX against Steered by the model
Walk-forward studiesQuanterLab Research
“We examine not to claim that any model works, but to understand when they do — and when they don't.”
QuanterLab is software built for quantitative research, and every study below is its output. Each one fixes its universe, step size and method before the walk begins, sees only what was knowable on each date, and puts every attempt on the record — including the ones that failed. Free to read. Methodology articles live alongside, and new studies go out by RSS.
44 studies
Walking in the Garden of Forking Paths
Each study walks one question forward on point-in-time data, window by window: a published result taken to a portfolio a retail hand could hold, or one choice a strategy designer must make, walked on both branches.
Oct 18, 2026
Hidden Markov Model Against the VIX on a Regime-Aware Factor Portfolio Comparison
Steered by the VIX against Steered by the model
 Open in the lab
 Oct 17, 2026
Hedgefundie’s Excellent Adventure, Tested Apart: What It Did Until the Forum Post, and What Changed Since
As posted against Bills instead of the bonds
 Oct 15, 2026
Clenow’s Stocks on the Move, Tested Apart Ten Years After the Book
A: the book's rules against B: without the market rule
 Oct 12, 2026
The Calm Before More Calm: the TTM Squeeze, the Bollinger Squeeze and volatility clustering in twenty years of S&P 500 stocks
The squeeze breakout against The plain breakout
 Oct 10, 2026
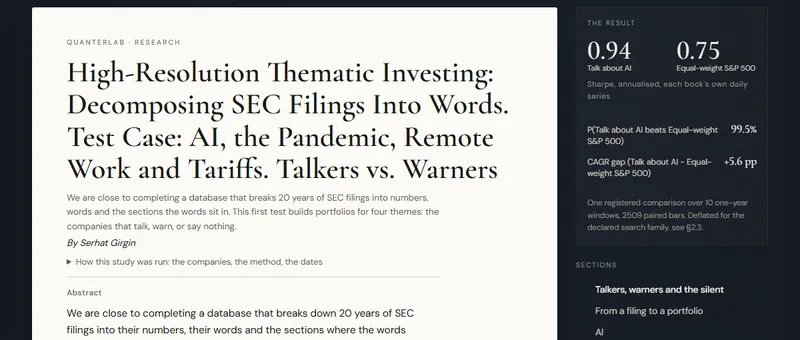
High-Resolution Thematic Investing: Decomposing SEC Filings Into Words. Test Case: AI, the Pandemic, Remote Work and Tariffs. Talkers vs. Warners
Talk about AI against Equal-weight S&P 500
 Oct 07, 2026
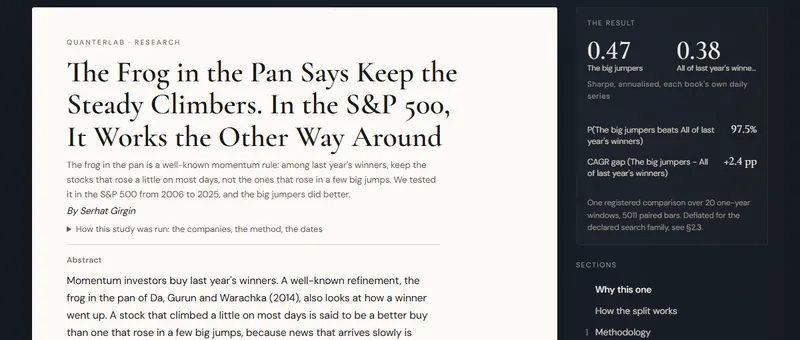
The Frog in the Pan Says Keep the Steady Climbers. In the S&P 500, It Works the Other Way Around
The big jumpers against All of last year's winners
 Oct 05, 2026
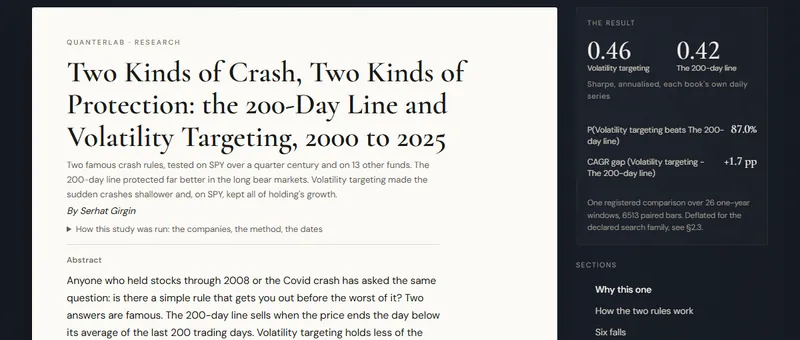
Two Kinds of Crash, Two Kinds of Protection: the 200-Day Line and Volatility Targeting, 2000 to 2025
Volatility targeting against The 200-day line
 Oct 03, 2026
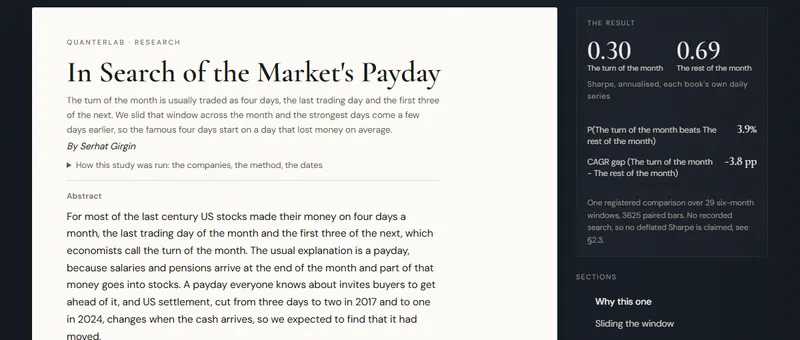
In Search of the Market's Payday
The turn of the month against The rest of the month
 Oct 02, 2026
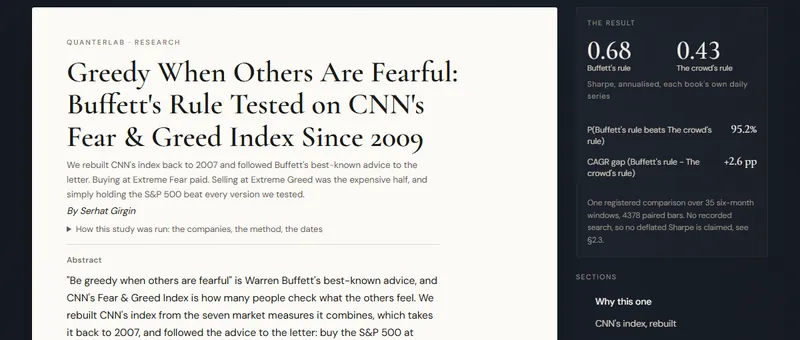
Greedy When Others Are Fearful: Buffett's Rule Tested on CNN's Fear & Greed Index Since 2009
Buffett's rule against The crowd's rule
 Sep 28, 2026
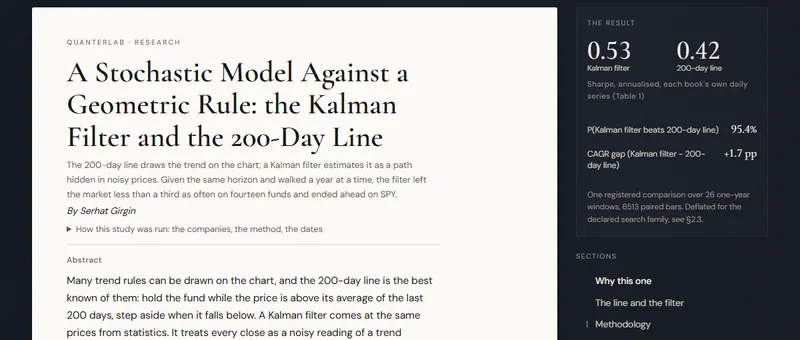
A Stochastic Model Against a Geometric Rule: the Kalman Filter and the 200-Day Line
Kalman filter against 200-day line
 Sep 26, 2026
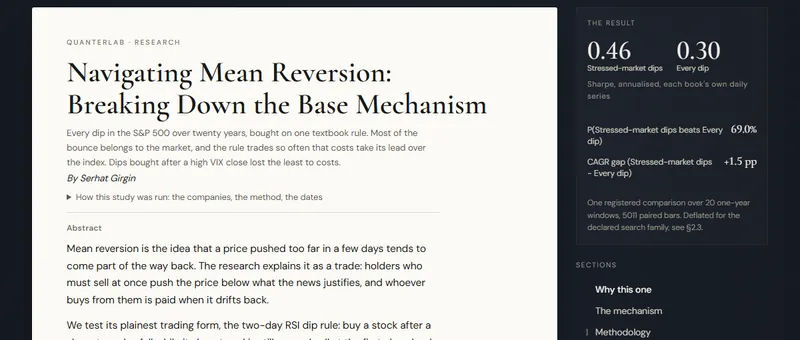
Navigating Mean Reversion: Breaking Down the Base Mechanism
Stressed-market dips against Every dip
 Sep 23, 2026
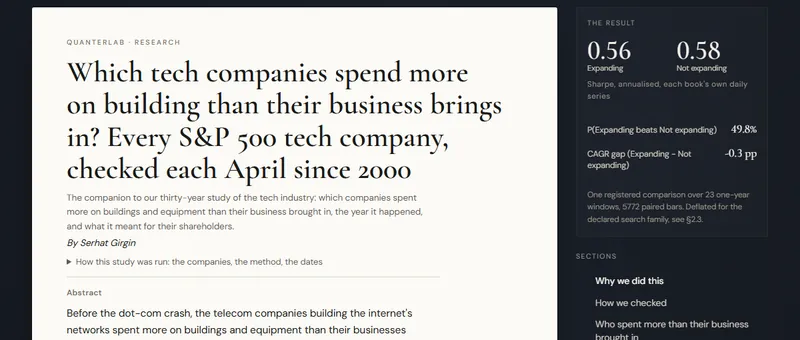
Which tech companies spend more on building than their business brings in? Every S&P 500 tech company, checked each April since 2000
Expanding against Not expanding
 Sep 22, 2026
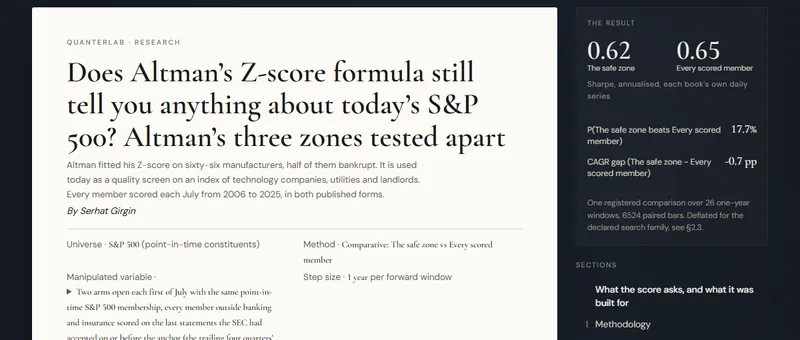
Does Altman’s Z-score formula still tell you anything about today’s S&P 500? Altman’s three zones tested apart
The safe zone against Every scored member
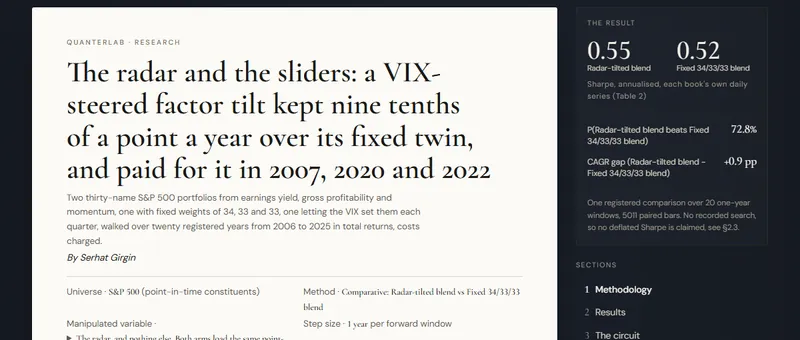 Sep 19, 2026
The radar and the sliders: a VIX-steered factor tilt kept nine tenths of a point a year over its fixed twin, and paid for it in 2007, 2020 and 2022
Radar-tilted blend against Fixed 34/33/33 blend
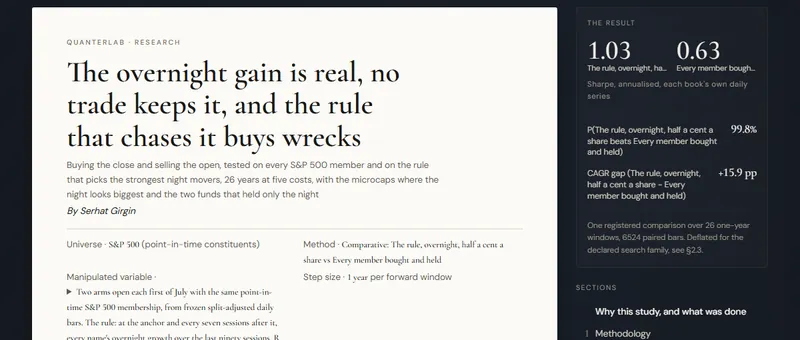 Sep 18, 2026
The overnight gain is real, no trade keeps it, and the rule that chases it buys wrecks
The rule, overnight, half a cent a share against Every member bought and held
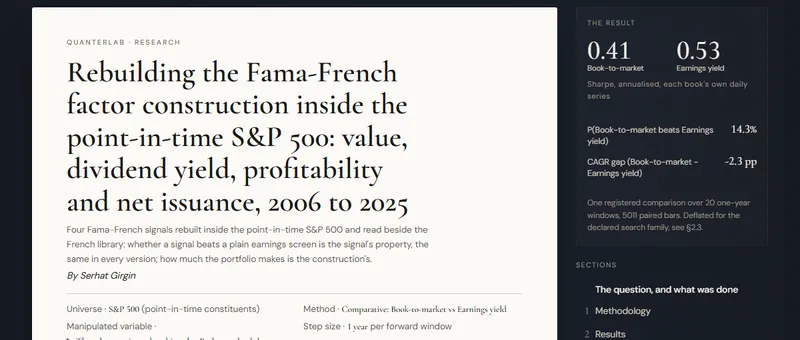 Sep 16, 2026
Rebuilding the Fama-French factor construction inside the point-in-time S&P 500: value, dividend yield, profitability and net issuance, 2006 to 2025
Book-to-market against Earnings yield
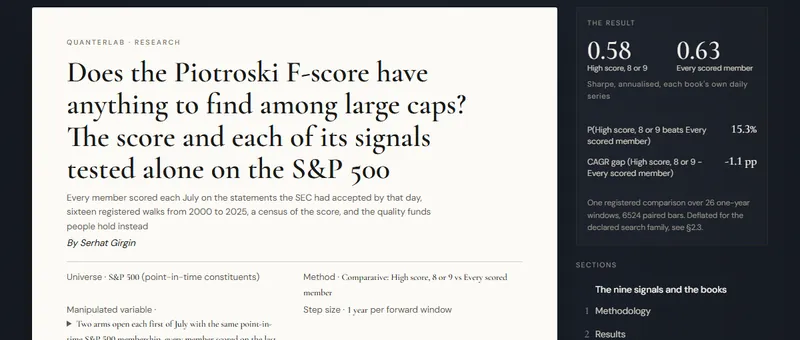 Sep 12, 2026
Does the Piotroski F-score have anything to find among large caps? The score and each of its signals tested alone on the S&P 500
High score, 8 or 9 against Every scored member
 Sep 11, 2026
Dividend capture loses, the week before the ex-date pays, and holding the same stocks beats both
Selected by past drop ratio against Every name of the cut
 Sep 08, 2026
What a European country fund is made of, and whether the country part is worth rotating
A registered, point-in-time walk-forward study of European rotation books (fixed lists) in 1-year steps. Stitched out-of-sample Sharpe 0.50 over 4512 observations. Deflated for the declared family search of N=30: 51%.
 Sep 06, 2026
Post-Earnings Drift, Decomposed: 81 Walks, a Predictability Spread That Was Market Exposure, and a Screen That Picks Better Announcements and a Worse Book
A registered, point-in-time walk-forward study of S&P 500 in 1-year steps. Stitched out-of-sample Sharpe 0.57 over 5012 observations. Deflated for the declared family search of N=81: 54%.
 Sep 05, 2026
Antonacci's Dual Momentum Taken Apart: Gate, Relative Leg, and Blends Across Four Lookbacks
Dual momentum (gate + relative leg) against Absolute momentum only (no international leg)
 Sep 04, 2026
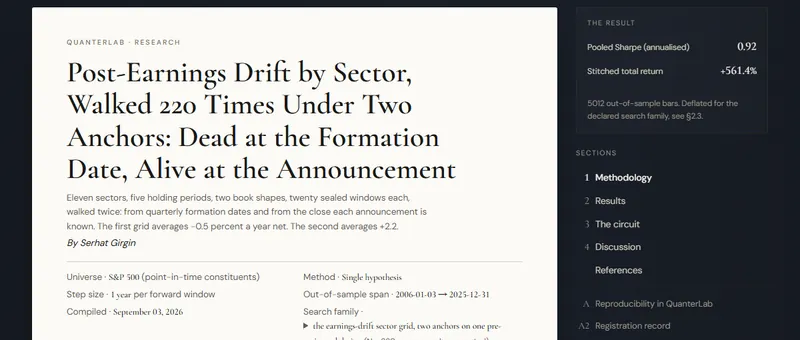
Post-Earnings Drift by Sector, Walked 220 Times Under Two Anchors: Dead at the Formation Date, Alive at the Announcement
A registered, point-in-time walk-forward study of S&P 500 in 1-year steps. Stitched out-of-sample Sharpe 0.92 over 5012 observations. Deflated for the declared family search of N=220: 90%.
 Sep 02, 2026
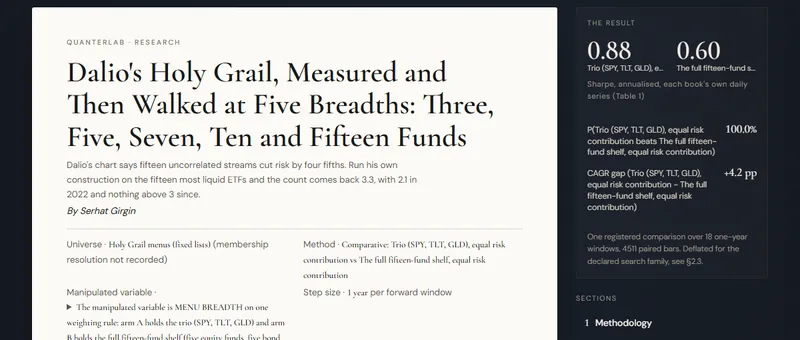
Dalio's Holy Grail, Measured and Then Walked at Five Breadths: Three, Five, Seven, Ten and Fifteen Funds
Trio (SPY, TLT, GLD), equal risk contribution against The full fifteen-fund shelf, equal risk contribution
 Sep 01, 2026
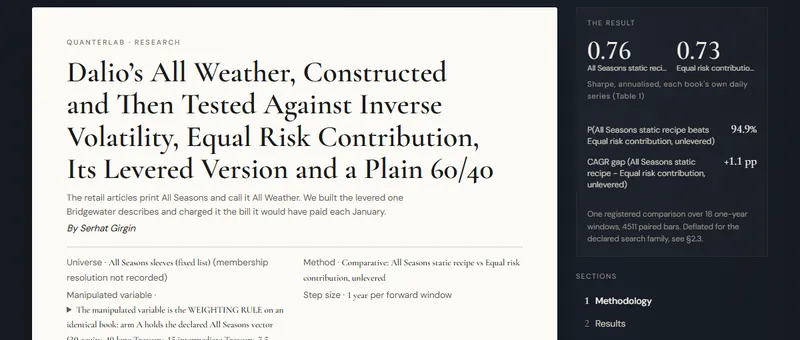
Dalio’s All Weather, Constructed and Then Tested Against Inverse Volatility, Equal Risk Contribution, Its Levered Version and a Plain 60/40
All Seasons static recipe against Equal risk contribution, unlevered
 Aug 30, 2026
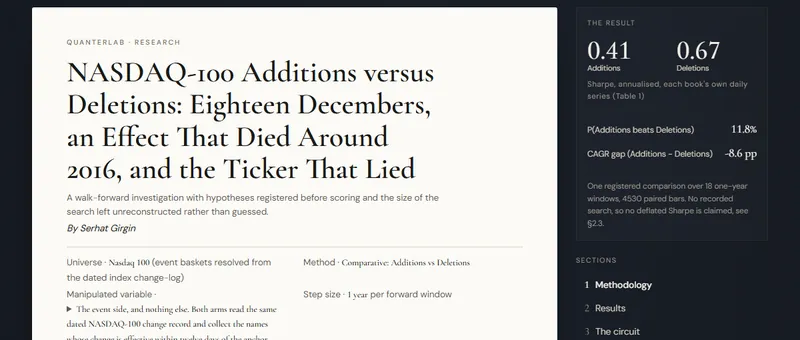
NASDAQ-100 Additions versus Deletions: Eighteen Decembers, an Effect That Died Around 2016, and the Ticker That Lied
Additions against Deletions
 Aug 27, 2026
One Half of the Magic Formula Beat the Whole Thing: Greenblatt's Two Ranks, Tested Apart
Magic Formula against Quality alone
 Aug 24, 2026
The Crash Switch Worked and the Strategy Starved Anyway: Keller's Menu Tested
Canary as published (B=1) against Two-bird floor (B=2)
 Aug 22, 2026
Steering Wheel, Not Brake - nineteen years of regime investing
Hold all nine against The regime turn
 Aug 21, 2026
The Regime Atlas - ten ways to read the market, twenty years, one scoreboard
A registered atlas from QuanterLab: the platform's ten regime classifiers, twenty years of causal labels on one scoreboard.
 Aug 20, 2026
The Sector Playbook, Audited - rotation, two gates and two hedges on one scoreboard
A research note from QuanterLab: commentary across cited studies, with figures drawn live from their frozen records.
 Aug 19, 2026
Arguments About Personality - a research note on the Fama-French series
A research note from QuanterLab: commentary across cited studies, with figures drawn live from their frozen records.
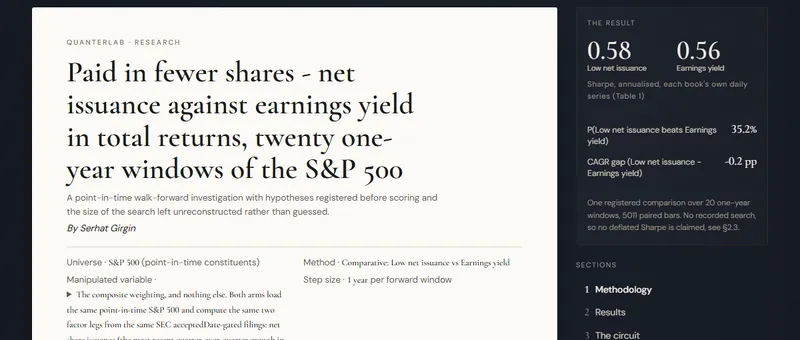 Aug 19, 2026
Paid in fewer shares - net issuance against earnings yield in total returns, twenty one-year windows of the S&P 500
Low net issuance against Earnings yield
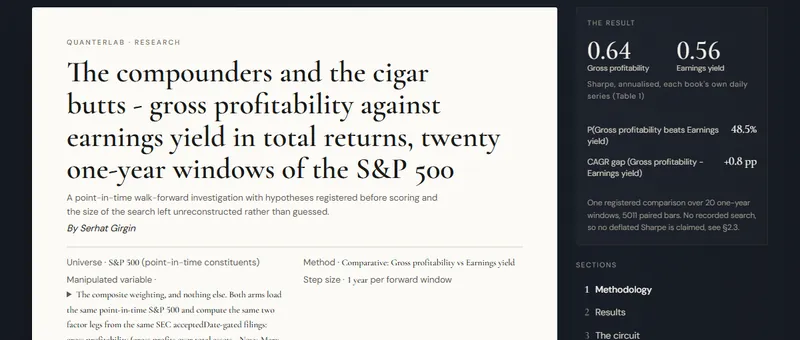 Aug 19, 2026
The compounders and the cigar butts - gross profitability against earnings yield in total returns, twenty one-year windows of the S&P 500
Gross profitability against Earnings yield
 Aug 19, 2026
Paid to wait, paid less - dividend yield against earnings yield in total returns, twenty one-year windows of the S&P 500
Dividend yield against Earnings yield
 Aug 19, 2026
The choice that washes out - book-to-market against the earnings yield it displaced, twenty one-year windows of the S&P 500
Book-to-market against Earnings yield
 Aug 12, 2026
The number on every brokerage screen mostly tells you where the market is
52-week high against 12-1 momentum
 Aug 09, 2026
Two ways to say calm - low beta and low volatility are not the same trade, and the difference is measurable
Low beta against Low volatility
 Aug 09, 2026
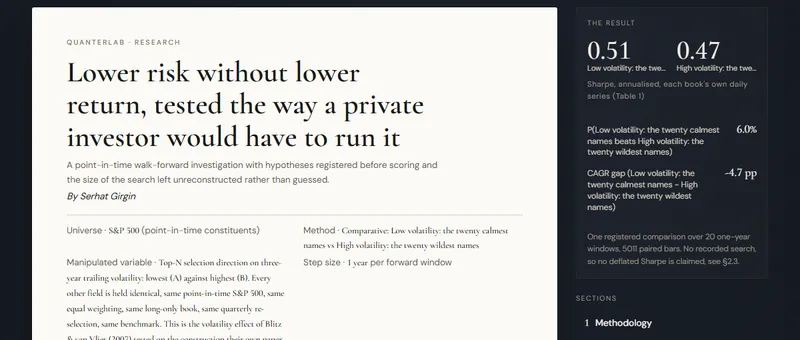
Lower risk without lower return, tested the way a private investor would have to run it
Low volatility: the twenty calmest names against High volatility: the twenty wildest names
 Aug 08, 2026
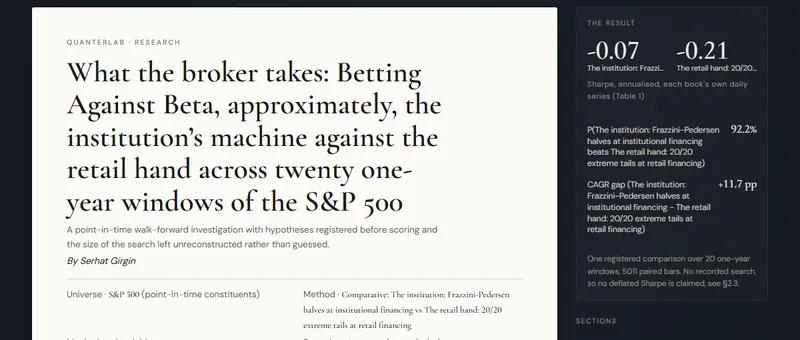
What the broker takes: Betting Against Beta, approximately, the institution’s machine against the retail hand across twenty one-year windows of the S&P 500
The institution: Frazzini-Pedersen halves at institutional financing against The retail hand: 20/20 extreme tails at retail financing
 Aug 07, 2026
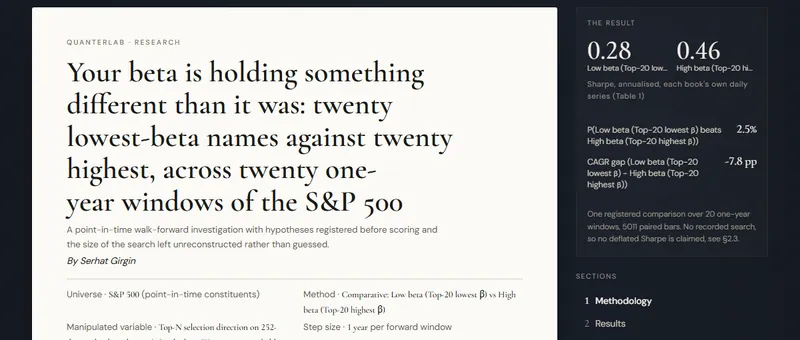
Your beta is holding something different than it was: twenty lowest-beta names against twenty highest, across twenty one-year windows of the S&P 500
Low beta (Top-20 lowest β) against High beta (Top-20 highest β)
 Aug 05, 2026
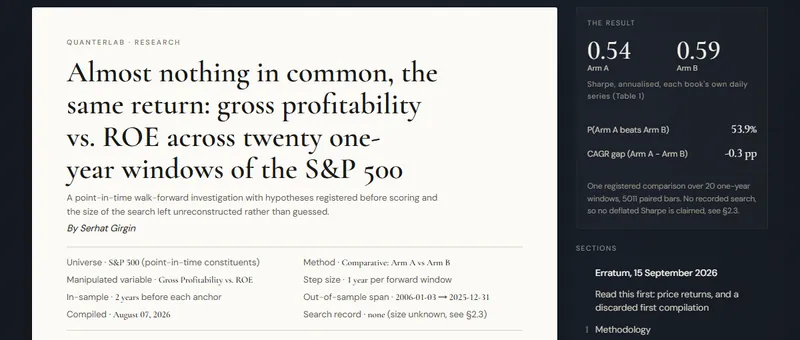
Almost nothing in common, the same return: gross profitability vs. ROE across twenty one-year windows of the S&P 500
Arm A against Arm B
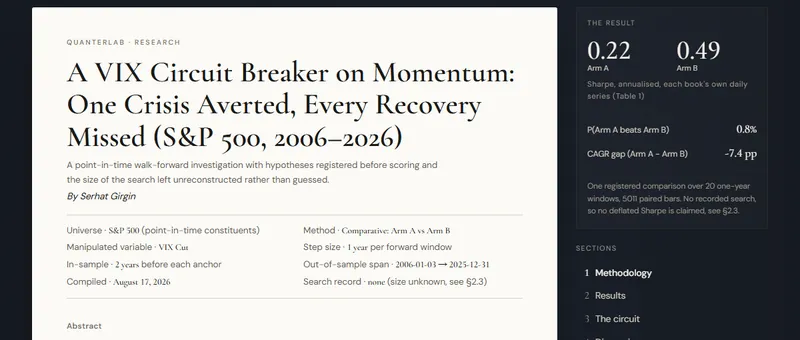 Aug 02, 2026
A VIX Circuit Breaker on Momentum: One Crisis Averted, Every Recovery Missed (S&P 500, 2006–2026)
Arm A against Arm B
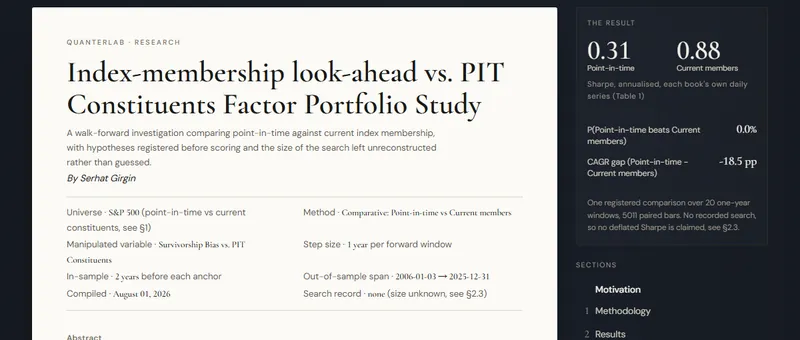 Jul 31, 2026
Index-membership look-ahead vs. PIT Constituents Factor Portfolio Study
Point-in-time against Current members
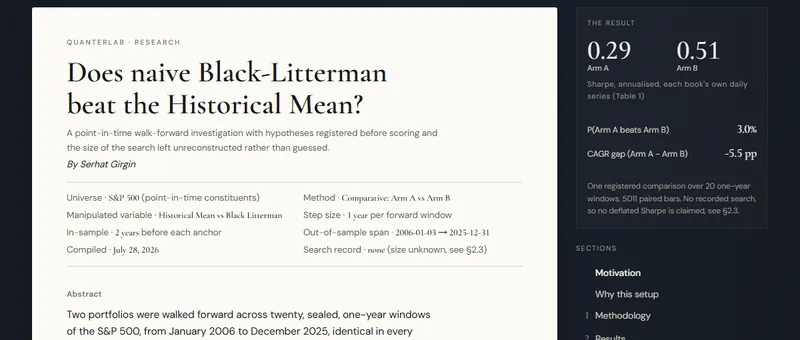 Jul 28, 2026
Does naive Black-Litterman beat the Historical Mean?
Arm A against Arm B
No studies match. Clear the box to see the full shelf.
Run a study like these
Everything on this page was produced inside QuanterLab — the registration, the walk, the statistics and the paper itself. Reading the research needs no account; creating one is free.