The radar and the sliders: a VIX-steered factor tilt kept nine tenths of a point a year over its fixed twin, and paid for it in 2007, 2020 and 2022
A regime tilt is bought as insurance: lean into momentum while the market is calm, into quality when it is stressed, and keep your head in a crash at little cost in between. The premium is rarely priced with the rule held fixed, because most tests choose the thresholds after seeing the crashes. This one fixed them before the walk and printed the bill year by year.
Two portfolios hold thirty S&P 500 names each, chosen every quarter by one score from three ranks, earnings yield, gross profitability and twelve-month momentum with the latest month skipped, on point-in-time membership and filings admitted by their SEC acceptance date. The fixed portfolio weights the three ranks 34, 33 and 33 in every quarter. The radar portfolio reads the VIX close of the day before each re-selection and leans to momentum when the VIX is below 16, to quality between 16 and 25, and to quality and value at 25 and above; the three weight maps are in Table 1. Nothing else differs: equal weight, total returns with dividends credited on the ex-date, ten basis points on every traded dollar, the equal-weight S&P 500 in total return as the ruler, twenty one-year windows from 2006 to 2025, each registered before it ran.
On the stitched record the radar compounded at 10.43 percent a year against 9.57 for the fixed portfolio and 9.51 for the index, with a worst drawdown of 55.0 percent against 57.2 and 60.7. The fixed portfolio matched the index; the radar kept 0.86 of a point a year over the fixed portfolio and 0.92 over the index. The radar led in nine of the twenty windows and five of them carry the lead, 2021 by 10.2 points, 2016 by 8.7, 2008 by 7.7 and 2014 and 2019 by 5.8 each, 38.2 of the 49.3 points the nine windows gave; the fixed portfolio led the other eleven by 35.9 points in total, and a block bootstrap of the daily differences puts the radar ahead in 72.8 percent of 2,000 resampled paths.
The bill is itemised. The 2008 cushion of 7.7 points was paid for in 2007, when the call turned defensive in July while the market still rose and the radar gave up 7.9 points, and in 2009, when a quality-heavy portfolio caught the rebound only 1.3 points better than the fixed one; compounded over the three years the radar still finished 5.4 percent of equity ahead. In 2020 the January call was calm, so the momentum map rode through the March fall and the stressed map arrived in April, after the bottom. In 2022 a rate shock hit the quality names the radar had rotated into and it was the worst of the three portfolios. What the record shows is a detector whose calls land up to a quarter after the turn, and a price list for that lag.
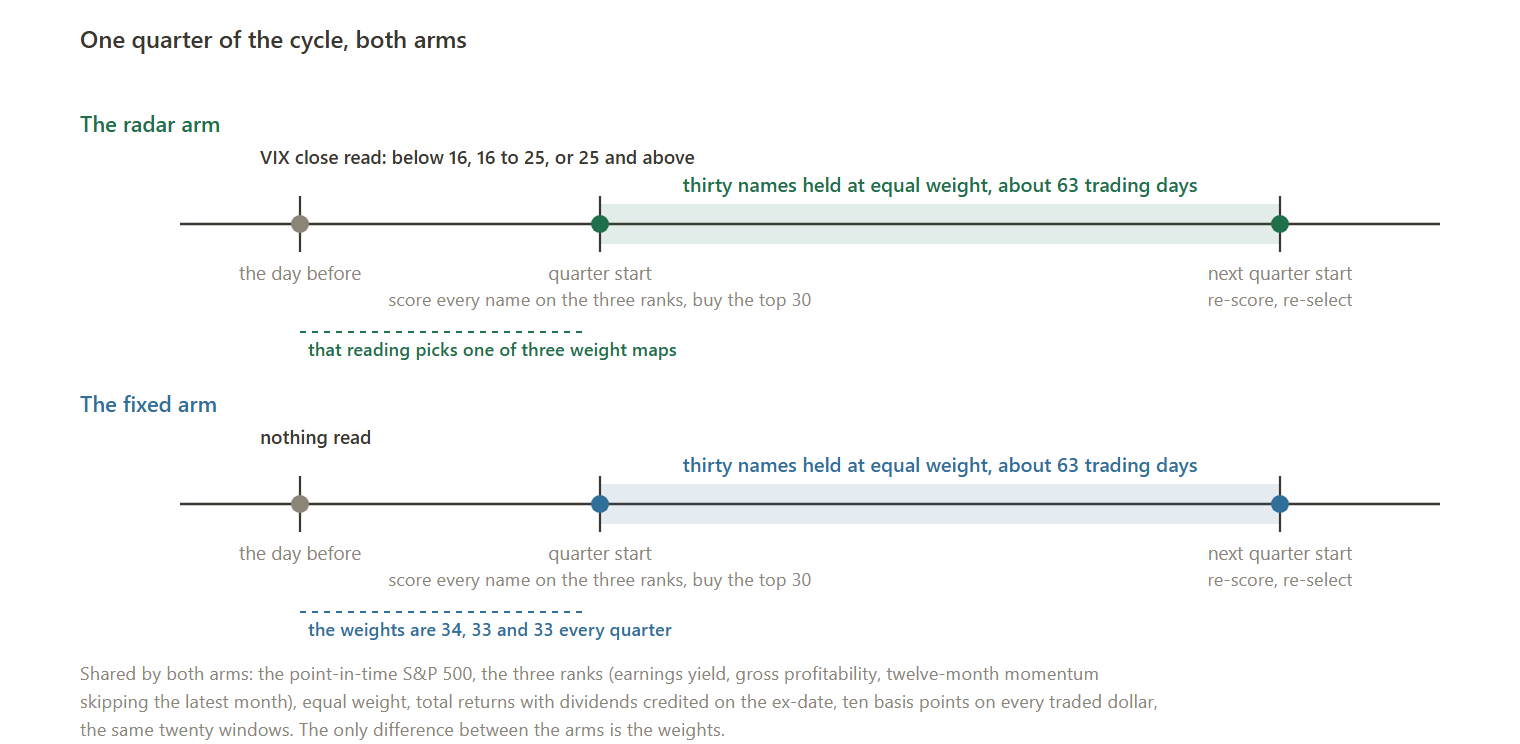
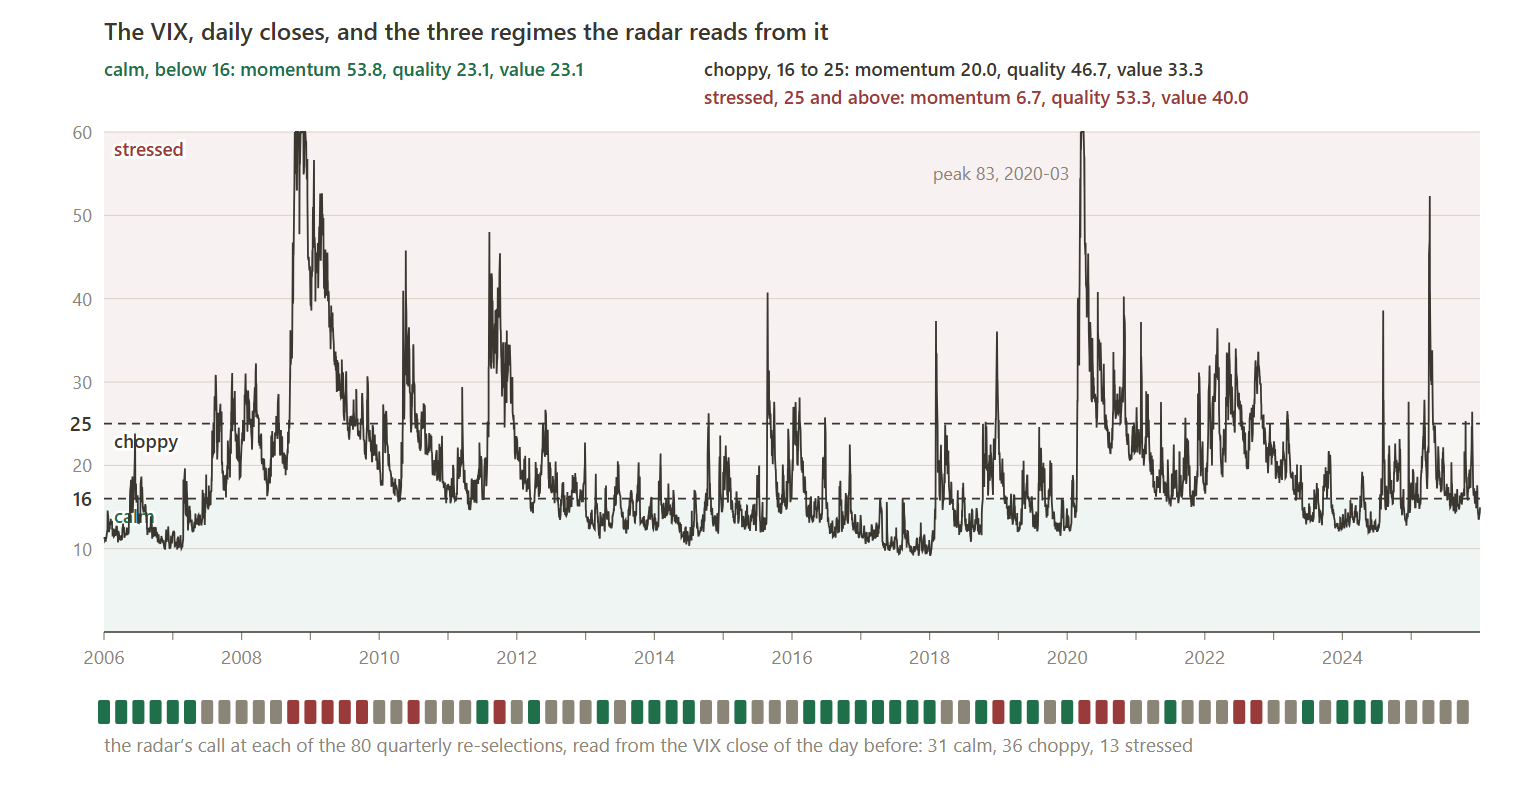
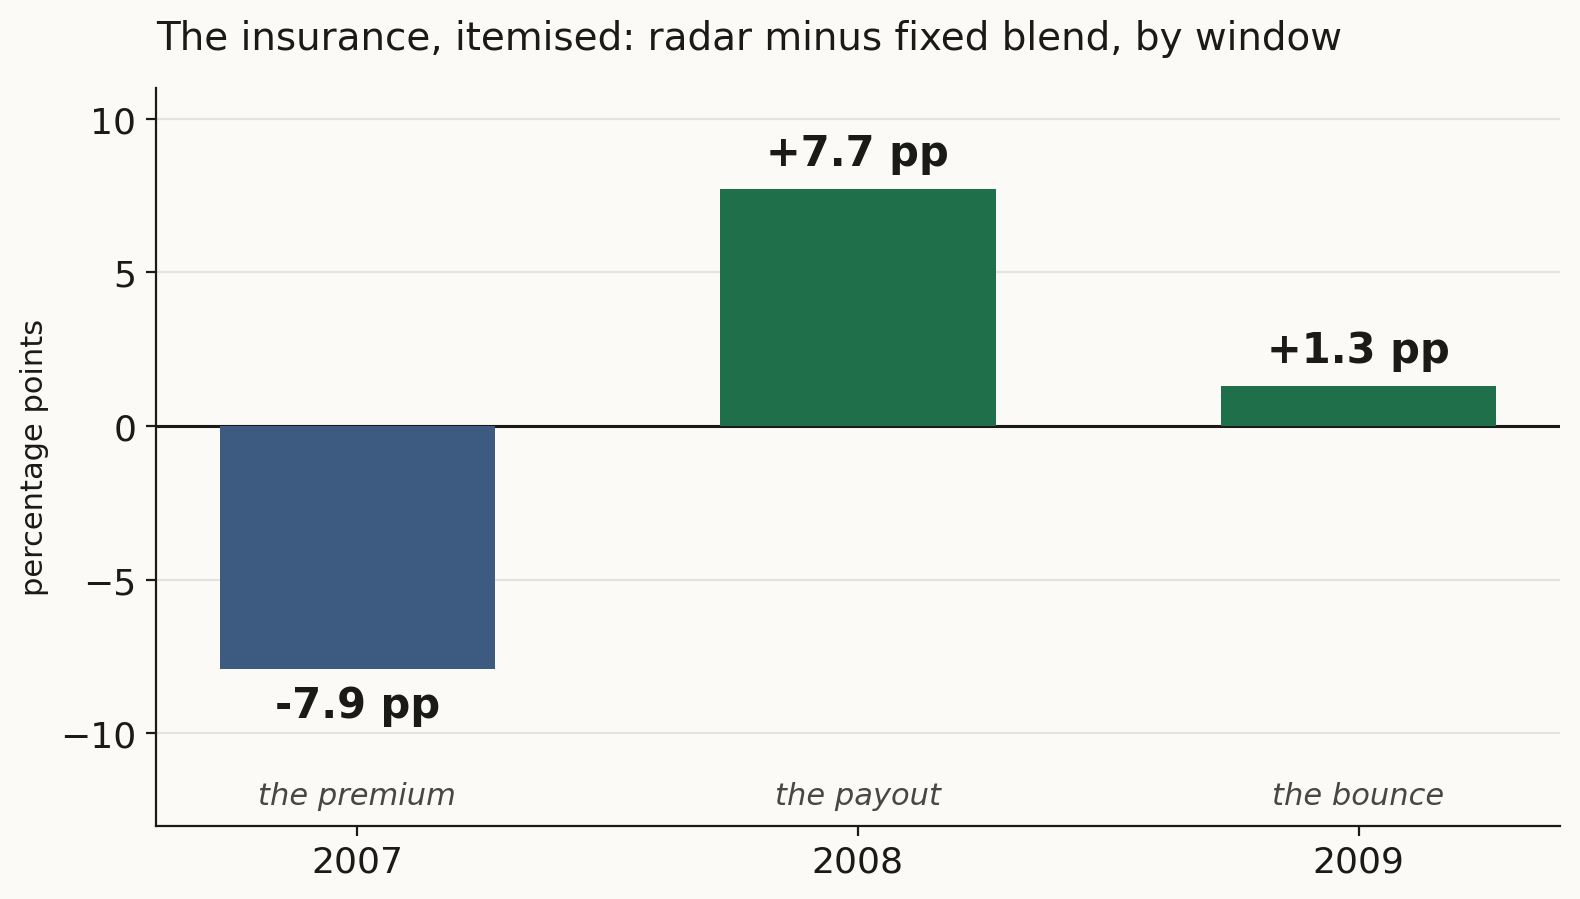
Table 1. The radar reads the VIX close of the day before each quarterly re-selection and applies the map of its band; the fixed portfolio applies the same weights every quarter. The maps are the tilt node's default settings and the bands the platform's house thresholds, both fixed before the walk. The last column counts the 80 quarterly re-selections of the twenty windows by the call made.
| Regime | VIX close | Momentum, % | Quality, % | Value, % | Re-selections |
|---|---|---|---|---|---|
| calm | below 16 | 53.8 | 23.1 | 23.1 | 31 |
| choppy | 16 to 25 | 20.0 | 46.7 | 33.3 | 36 |
| stressed | 25 and above | 6.7 | 53.3 | 40.0 | 13 |
| fixed blend | not read | 33 | 33 | 34 | 80 |
1 Methodology
The universe is the S&P 500 as it stood on each anchor date. Each company gets three ranks from data public on that date: earnings yield, trailing earnings over price; gross profitability, gross profit over assets; and momentum, the return over the twelve months to the month before the anchor, the latest month skipped. Filings enter by their SEC acceptance date, so a quarter's numbers count only from the day they were public. The three ranks are combined into one score with three weights, the thirty highest scores are bought at equal weight and held for a quarter, and at each quarter start the score is recomputed and the thirty names re-selected.
The fixed portfolio uses the same three weights at every re-selection: 34 percent on earnings yield, 33 on gross profitability, 33 on momentum. The radar portfolio takes the VIX close of the day before the re-selection and sets the weights from it. The tilt node applies its default regime adjustment to the same 34, 33 and 33 sliders, so the result is three fixed weight maps (Table 1): below 16 the portfolio leans to momentum; from 16 to 25 to quality; at 25 and above to quality and value, with momentum nearly out. The thresholds are the platform's house settings, the adjustment is the node's default, and the node was set to follow the VIX classifier alone, its three other signal inputs at zero; all of it was fixed before the walk and none of it was tuned to this record. Over the twenty years the radar called calm at 31 of the 80 re-selections, choppy at 36 and stressed at 13 (Figure 2).
Both portfolios are long only, equal weight, thirty names, in total returns with each dividend credited on its ex-date and held as cash to the next re-selection, with ten basis points charged on every one-way traded dollar, about four tenths of a point of equity a year at this turnover, and with the equal-weight S&P 500 rebuilt in total return by the same ex-date rule as the ruler: an equal-weight thirty-name portfolio is measured against the equal-weight index because the cap-weighted one would credit the tilt with the weighting scheme. Sharpe ratios are on raw daily returns with no cash hurdle. Every number quoted in the text and in the headline card is on the stitched basis of Table 2's total, per-year, volatility, Sharpe and drawdown columns: each portfolio's own daily series chained through the twenty windows with the ten basis points of each window's opening purchase charged at the window start. The window returns of Tables 3, 4, 6 and 7, Table 2's mean-window column, the bootstrap and the paired Sharpe ratio are the registration's paired-day figures, which start each window after that purchase, so the twenty window returns chain to 10.54 and 9.68 percent a year where Table 2 reads 10.43 and 9.57; the index pays no opening charge and chains to within a hundredth of its Table 2 figure. The two bases differ in level by that charge, a tenth of a point a year, and agree on the gap between the arms, 0.86, to the hundredth.
The two circuits differ in two nodes, the VIX classifier and the tilt node it feeds, which together are the radar; the tilt node cannot run without the classifier, so the pair is one treatment, and the difference between the arms is the radar and nothing else. Twenty one-year windows from January 2006 to December 2025, each registered before it ran and frozen when it landed; the walk moves only forward. Three unregistered rehearsal runs of the exact circuit were made before registration, at the 2006, 2020 and 2022 anchors, to check that the radar moved the weights in both directions and that the cost and dividend accounting were live; no design change followed. The design was not promoted from a recorded search, so no count of alternatives is claimed and no deflation is applied to the numbers.
2 Results
2.1 Headline
| Book | Total return | Per year | Volatility | Sharpe | Worst drawdown | Mean window |
|---|---|---|---|---|---|---|
| Radar-tilted blend | +627.6% | 10.43% | 22.6% | 0.55 | -55.0% | +11.79% |
| Fixed 34/33/33 blend | +521.8% | 9.57% | 22.4% | 0.52 | -57.2% | +11.12% |
| Benchmark (reference) | +515.1% | 9.51% | 20.7% | 0.54 | -60.7% | +11.11% |
Volatility, Sharpe and worst drawdown are computed on each book's own stitched daily series over the identical trading days that Figure 4 draws, so the panel and the figure are the same arithmetic. Sharpe carries no cash hurdle. Mean window is the arithmetic average of the one-year window returns, each from its first close after the opening trade, and does not compound to the total beside it: the difference is volatility drag, plus that opening charge where the walk pays one.
Table 3. Each window runs from the first trading day of January for one year. The four calls are the regime the radar read at the January, April, July and October re-selections; the returns are total returns, the two portfolios net of costs and the equal-weight index with no cost; the gap is radar minus fixed in percentage points.
| Window | January | April | July | October | Radar, % | Fixed, % | Index, % | Gap, points | Led by |
|---|---|---|---|---|---|---|---|---|---|
| 2006 | calm | calm | calm | calm | +9.6 | +12.9 | +13.5 | -3.2 | fixed |
| 2007 | calm | calm | choppy | choppy | +1.5 | +9.4 | +0.9 | -7.9 | fixed |
| 2008 | choppy | choppy | choppy | stressed | -30.3 | -38.0 | -39.1 | +7.7 | radar |
| 2009 | stressed | stressed | stressed | stressed | +20.6 | +19.3 | +39.9 | +1.3 | radar |
| 2010 | choppy | choppy | stressed | choppy | +9.7 | +10.7 | +19.5 | -1.0 | fixed |
| 2011 | choppy | choppy | calm | stressed | -1.3 | -3.5 | -0.8 | +2.2 | radar |
| 2012 | choppy | calm | choppy | choppy | +16.6 | +20.9 | +16.8 | -4.3 | fixed |
| 2013 | choppy | calm | choppy | calm | +39.1 | +41.2 | +33.4 | -2.1 | fixed |
| 2014 | calm | calm | calm | choppy | +25.6 | +19.8 | +16.2 | +5.8 | radar |
| 2015 | choppy | calm | choppy | choppy | -3.1 | +0.6 | -1.7 | -3.7 | fixed |
Table 4. The same columns as Table 3 for the second decade.
| Window | January | April | July | October | Radar, % | Fixed, % | Index, % | Gap, points | Led by |
|---|---|---|---|---|---|---|---|---|---|
| 2016 | choppy | calm | calm | calm | +11.9 | +3.2 | +15.8 | +8.7 | radar |
| 2017 | calm | calm | calm | calm | +19.1 | +23.0 | +17.6 | -3.9 | fixed |
| 2018 | calm | choppy | choppy | calm | -4.0 | -8.0 | -8.5 | +4.0 | radar |
| 2019 | stressed | calm | calm | choppy | +26.7 | +20.9 | +28.8 | +5.8 | radar |
| 2020 | calm | stressed | stressed | stressed | +16.6 | +18.2 | +12.4 | -1.6 | fixed |
| 2021 | choppy | choppy | calm | choppy | +26.7 | +16.5 | +31.3 | +10.2 | radar |
| 2022 | choppy | choppy | stressed | stressed | -12.4 | -9.7 | -11.7 | -2.7 | fixed |
| 2023 | choppy | choppy | calm | choppy | +19.7 | +23.5 | +13.8 | -3.8 | fixed |
| 2024 | calm | calm | calm | choppy | +27.7 | +24.1 | +12.8 | +3.6 | radar |
| 2025 | choppy | choppy | choppy | choppy | +15.7 | +17.4 | +11.5 | -1.7 | fixed |
2.2 Per-step results
| # | Out-of-sample window | Radar-tilted blend SR | Fixed 34/33/33 blend SR |
|---|---|---|---|
| 1 | 2006-01-03 → 2006-12-29 | 0.60 | 0.82 |
| 2 | 2007-01-03 → 2007-12-31 | 0.17 | 0.54 |
| 3 | 2008-01-02 → 2008-12-31 | -0.68 | -0.94 |
| 4 | 2009-01-02 → 2009-12-31 | 0.77 | 0.80 |
| 5 | 2010-01-04 → 2010-12-31 | 0.55 | 0.55 |
| 6 | 2011-01-03 → 2011-12-30 | 0.09 | -0.01 |
| 7 | 2012-01-03 → 2012-12-31 | 1.10 | 1.32 |
| 8 | 2013-01-02 → 2013-12-31 | 2.29 | 2.36 |
| 9 | 2014-01-02 → 2014-12-31 | 1.47 | 1.25 |
| 10 | 2015-01-02 → 2015-12-31 | -0.11 | 0.12 |
| 11 | 2016-01-04 → 2016-12-30 | 0.88 | 0.29 |
| 12 | 2017-01-03 → 2017-12-29 | 1.45 | 1.99 |
| 13 | 2018-01-02 → 2018-12-31 | -0.08 | -0.29 |
| 14 | 2019-01-02 → 2019-12-31 | 1.83 | 1.41 |
| 15 | 2020-01-02 → 2020-12-31 | 0.59 | 0.63 |
| 16 | 2021-01-04 → 2021-12-31 | 1.42 | 0.89 |
| 17 | 2022-01-03 → 2022-12-30 | -0.38 | -0.22 |
| 18 | 2023-01-03 → 2023-12-29 | 1.18 | 1.29 |
| 19 | 2024-01-02 → 2024-12-31 | 1.33 | 1.44 |
| 20 | 2025-01-02 → 2025-12-31 | 0.79 | 0.82 |
2.3 Search accounting
No search record exists for this design. It was not promoted from a recorded evolving search, so the number of alternatives tried before it, on paper, in another tool, or in the author's head, is unknown. Unknown is a different fact from one: a study with no lineage is not a strategy with one trial, it is a strategy with an unrecorded number of them. Accordingly no count of alternatives tried is claimed, and nothing in this paper is corrected for a search that was never recorded; the number that stands is the raw out-of-sample result plus this disclosure. The registered per-step record below (§4) still guarantees each window's hypothesis was hashed and registered before that window was scored.
2.4 The comparison
Both arms trade the same registered windows, so their returns can be PAIRED: inside each window the two return series are inner-joined date by date and the difference rRadar-tilted blend − rFixed 34/33/33 blend is the object under test. Because this is ONE pre-declared contrast, frozen at registration before any window was scored, the paired statistic needs no multiple-testing deflation, and the per-arm pooled numbers above are likewise uncorrected, because this design has no recorded search to correct against (§2.3). The paired contrast carries that gap differently from the arm levels: it was declared before each window ran and it is scored on the difference, so no window could be read first and scored after. What the timestamps cannot speak to is how this contrast came to be the declared one, which is the limit §2.3 states.
In the table: Arm A = Radar-tilted blend · Arm B = Fixed 34/33/33 blend.
| # | Window | Paired bars | Arm A | Arm B | Δ | Leader |
|---|---|---|---|---|---|---|
| 1 | 2006-01-04 → 2006-12-29 | 250 | +9.6% | +12.9% | -3.2 pp | Arm B |
| 2 | 2007-01-04 → 2007-12-31 | 250 | +1.5% | +9.4% | -7.9 pp | Arm B |
| 3 | 2008-01-03 → 2008-12-31 | 252 | -30.3% | -38.0% | +7.7 pp | Arm A |
| 4 | 2009-01-05 → 2009-12-31 | 251 | +20.6% | +19.3% | +1.3 pp | Arm A |
| 5 | 2010-01-05 → 2010-12-31 | 251 | +9.7% | +10.7% | -1.0 pp | Arm B |
| 6 | 2011-01-04 → 2011-12-30 | 251 | -1.3% | -3.5% | +2.2 pp | Arm A |
| 7 | 2012-01-04 → 2012-12-31 | 249 | +16.6% | +20.9% | -4.3 pp | Arm B |
| 8 | 2013-01-03 → 2013-12-31 | 251 | +39.1% | +41.2% | -2.1 pp | Arm B |
| 9 | 2014-01-03 → 2014-12-31 | 251 | +25.6% | +19.8% | +5.8 pp | Arm A |
| 10 | 2015-01-05 → 2015-12-31 | 251 | -3.1% | +0.6% | -3.7 pp | Arm B |
| 11 | 2016-01-05 → 2016-12-30 | 251 | +11.9% | +3.2% | +8.7 pp | Arm A |
| 12 | 2017-01-04 → 2017-12-29 | 250 | +19.1% | +23.0% | -3.9 pp | Arm B |
| 13 | 2018-01-03 → 2018-12-31 | 250 | -4.0% | -8.0% | +4.0 pp | Arm A |
| 14 | 2019-01-03 → 2019-12-31 | 251 | +26.7% | +20.9% | +5.8 pp | Arm A |
| 15 | 2020-01-03 → 2020-12-31 | 252 | +16.6% | +18.2% | -1.6 pp | Arm B |
| 16 | 2021-01-05 → 2021-12-31 | 251 | +26.7% | +16.5% | +10.2 pp | Arm A |
| 17 | 2022-01-04 → 2022-12-30 | 250 | -12.4% | -9.7% | -2.7 pp | Arm B |
| 18 | 2023-01-04 → 2023-12-29 | 249 | +19.7% | +23.5% | -3.8 pp | Arm B |
| 19 | 2024-01-03 → 2024-12-31 | 251 | +27.7% | +24.1% | +3.6 pp | Arm A |
| 20 | 2025-01-03 → 2025-12-31 | 249 | +15.7% | +17.4% | -1.7 pp | Arm B |
Paired Sharpe of the difference track: 0.13 · block bootstrap (2000 paths, block 10, seed 1234): P(Radar-tilted blend beats Fixed 34/33/33 blend) = 72.8%.
Window win-rate. Radar-tilted blend led 9 of 20 windows (45.0%), Fixed 34/33/33 blend led 11, yet the mean window gap runs the other way: +0.67 pp toward Radar-tilted blend. Fixed 34/33/33 blend wins more often and smaller; Radar-tilted blend wins less often and larger. The count and the mean answer different questions, and neither settles the comparison by itself. Widest single window: 2021 at +10.2 pp.
| Period | Windows | Radar-tilted blend | Fixed 34/33/33 blend | Mean gap | Radar-tilted blend led |
|---|---|---|---|---|---|
| All windows | 20 | +11.79% | +11.12% | +0.67 pp | 9/20 |
| Before 2010 | 4 | +0.36% | +0.88% | -0.52 pp | 2/4 |
| 2010 onward | 16 | +14.65% | +13.68% | +0.97 pp | 7/16 |
3 The circuit
The strategy is a circuit of platform primitives, frozen when the study is registered. Below is the circuit as wired on the canvas, the objective it encodes and how the search runs through it, followed by the mathematics each primitive actually computes, the same formulas the execution engine runs. The complete parameterisation is preserved in the study ledger (Appendix A).
The sentence below is the registration record, generated when the circuit was sealed and printed verbatim; the authored description of the design is Section 1.
A COMPARATIVE study, Radar-tilted blend vs Fixed 34/33/33 blend, walked on the same registered out-of-sample windows. Radar-tilted blend: S&P 500, rebalanced quarterly across the selected basket, conditioned on the wired regime classifier, and run out-of-sample from the anchor, whatever the design estimates from history is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. Fixed 34/33/33 blend: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor, whatever the design estimates from history is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. The arms differ in: 2 places, VIX Regime, removed in Fixed 34/33/33 blend; Regime Tilt (radar), removed in Fixed 34/33/33 blend. NOTE: with more than one difference, an out-of-sample gap cannot be attributed to any single change. The contrast under test: whether Radar-tilted blend generates better risk-adjusted returns than Fixed 34/33/33 blend over the identical out-of-sample windows.
Envelopes show counts, ratios, dates, and the parameters the author chose. Full price and per-name data series are not republished: the underlying market data is licensed to QuanterLab. Point figures quoted in the prose, a named holding's return over a stated span, are summary facts derived from public market prices, not redistributed series.
The objective and the search
Radar-tilted blend
| Universe | S&P 500 index constituents. |
|---|---|
| Validation & out-of-sample | portfolio forward test (buy-and-hold book) (1y horizon from the anchor, quarterly rebalance); overlays: Transaction Cost. |
| Regime layer | macro regime detected via live VIX threshold. |
| Other components | Factor models: Factor Composite, Factor Select, Fundamentals Loader (PIT), Momentum Factor, Quality Factor, Regime Tilt (radar), Value Factor. |
Fixed 34/33/33 blend
| Other components | Factor models: Factor Composite, Factor Select, Fundamentals Loader (PIT), Momentum Factor, Quality Factor, Value Factor. |
|---|
Every other specification row is identical to Radar-tilted blend's table above.
What differs between the arms, 2 differences; more than one thing changes at once:
- removedVIX Regime, removed in Fixed 34/33/33 blend
- removedRegime Tilt (radar), removed in Fixed 34/33/33 blend
Reader's note. With 2 settings changed at once across 2 nodes, an out-of-sample gap between the arms cannot be attributed to any single change, the arms are compared as whole packages, and any causal reading of one ingredient is unsupported by this design.
Author's note. The note above counts two settings across two nodes. The two are one treatment: the tilt node cannot run without the classifier that feeds it, and the classifier feeds nothing else, so the radar is the only thing that differs between the arms, and the gap is attributed to the radar as a whole, not to either node alone.
Cost elements are wired into the circuit, the realised drag is reported per step in Appendix B.
Show the mathematics, 13 primitives, formulas and parity notes
3.1 Universe
The starting set of tickers, resolved point-in-time from the index change-log, so names delisted or removed later still compete on the dates they traded.
Before any math, you need a list of stocks. An index preset (S&P 500, Nasdaq-100, Dow 30) is reconstructed as it stood ON your anchor date by replaying the historical add/drop change-log backwards, so a 2018 backtest sees the 2018 membership, not today's winners.
Start from today's constituents and un-apply every membership change after the anchor t:
\mathcal{U}(t) = \mathcal{U}_{\text{now}} \;\ominus\; \{\text{adds after } t\} \;\oplus\; \{\text{drops after } t\}3.2 Price Loader
Bulk OHLCV fetch for the whole universe, point-in-time, no future bars.
Momentum, volatility, trend, every price-based metric needs history. This loads open/high/low/close/volume for all names in parallel, clipped so nothing after the anchor can leak in. The lookback window is derived automatically from the deepest metric you wired.
It loads exactly enough history for the hungriest downstream metric plus a warm-up buffer:
W = \max_k(\text{lookback}_k) + \text{buffer}, \qquad \text{bars} \le \text{anchor } t3.3 Factor Loader
Point-in-time fundamentals, never let the user see a number before the SEC did.
Loads ~23 fundamental metrics (valuation, quality, growth) per name, but with one inviolable rule: a financial statement becomes visible only on or after its SEC acceptedDate. A 2020 backtest sees only what was actually filed by 2020, no look-ahead, ever.
\text{visible}(f, t) \iff \text{acceptedDate}(f) \le t3.4 Factor Value
Value, how cheap is the stock, cross-sectionally?
Blends cheapness metrics, P/E, P/B, P/S, EV/EBITDA (lower is better) plus free-cash-flow and earnings yields (higher is better). Each metric is z-scored across the universe, winsorized against outliers, weighted by the importance you set (Off/Low/Med/High), and averaged.
z_{i,k} = \pm\,\frac{x_{i,k} - \bar x_k}{s_k}\text{Value}_i = \frac{\sum_k \omega_k\,z_{i,k}}{\sum_k \omega_k}, \quad \omega \in \{0,\,0.5,\,1,\,2\}3.5 Factor Quality
Quality, is this a strong, profitable, well-financed business?
Blends profitability (ROE, ROA, ROIC, margins) and balance-sheet strength (debt-to-equity inverted, current ratio, interest coverage). Same z-score, winsorize, importance-weight recipe as every factor family.
\text{Quality}_i = \frac{\sum_k \omega_k\,z_{i,k}}{\sum_k \omega_k}3.6 Factor Momentum
Momentum, recent price strength, no filing required.
Pure price-based: 1/3/6/12-month returns measured at the anchor. Because it needs no financial statement, it is always available, even for names with thin fundamentals.
\text{Mom}_i = \frac{\sum_k \omega_k\, z\!\big(R_{i}^{(k)}\big)}{\sum_k \omega_k}, \quad R^{(k)} = \frac{P_{\mathrm{near}}}{P_{t-k}}-13.7 Factor Composite
The weighting console, blend Value, Quality, Momentum, Growth into one 0–100 score.
Where the four factor families become a single ranking. Each family score is standardized across the universe, blended with your slider weights (or the radar's suggested tilt), and min-max scaled to 0–100. Winsorizing tames outliers; z-score or percentile normalization is your choice.
z_{i,f} = \frac{x_{i,f} - \bar x_f}{s_f}\quad(\text{clipped at the 1st / 99th percentile})C_i = \sum_f W_f\,z_{i,f}, \qquad \text{score}_i = 100\cdot\frac{C_i - \min_j C_j}{\max_j C_j - \min_j C_j}3.8 Factor Top Tier
The cut out of the factor lane, keep the top-ranked names.
Takes the composite-ranked factor set and keeps the best N, carrying the composite score, the four family scores and the point-in-time market cap for each survivor. Feed 10–20 to a direct portfolio, or 30–100 as an optimizer pool.
\{\, i : \operatorname{rank}(C_i) \le N\,\}, \quad C_i = \text{composite score}3.9 Portfolio Backtest
Replay the portfolio forward, rebalanced, point-in-time, with costs.
Holds the basket and rebalances on schedule, re-selecting and re-optimizing point-in-time at each rebalance (so it only ever uses information available then), and reports the equity curve, Sharpe, drawdown and trade stats, optionally net of cost and risk overlays.
E_t = E_{t-1}\big(1 + \mathbf w_{t}^{\top}\mathbf r_t - \text{costs}_t\big)\text{DD}_t = \frac{E_t}{\max_{\tau\le t}E_\tau} - 1, \qquad \text{MaxDD} = \min_t \text{DD}_t\text{charge}_t \;=\; \text{loan}_t \cdot \frac{\text{spread}}{252}, \qquad \text{loan}_t = \begin{cases}\max(0,\,-\text{cash}_t) & \text{institutional (netted)}\\ \max(0,\,\text{long MV}_t - E_t) & \text{retail (no netting)}\end{cases}3.10 Portfolio Forward Autopsy
The post-mortem, where the forward test’s return actually came from.
Runs after the Portfolio Forward Test and dissects its realized path: per-rebalance contributions, winners and losers, exposure and cash periods, and how the realized route compares to what the risk cones projected. It computes nothing new about the future, it explains the past the book just lived.
Depth I–IV: headline attribution, per-segment breakdown, per-name contributions, and the calibration ledger (projected cone vs realized, segment by segment). In a study, this is the node that fills the appendices.
3.11 Vix Regime
VIX thresholds, the simplest fear gauge.
Reads the VIX (or a wired series) and classifies by two cut-offs: low VIX is calm, high VIX is stressed, in between is choppy. Confidence scales with how far past the boundary you are.
\text{regime} = \begin{cases}\text{calm} & \text{VIX} < c\\[2pt]\text{stressed} & \text{VIX} \ge s\\[2pt]\text{choppy} & \text{otherwise}\end{cases}3.12 Factor Regime Tilt
The radar, read the market and suggest which factors to lean on.
Four market signals vote on a recommended Value/Quality/Momentum/Growth weighting: the trend regime (momentum & growth in bull markets, quality & value in bear), the valuation spread, factor momentum, and cross-sectional dispersion. Their importances normalize to 100 and produce a tilt the Composite applies.
\mathbf{w} = 0.30\,\mathbf{R} + 0.25\,\mathbf{V} + 0.25\,\mathbf{M} + 0.20\,\mathbf{D}\text{calm}\to\text{bullish},\ \ \text{choppy}\to\text{sideways},\ \ \text{stressed}\to\text{bearish}3.13 Transaction Cost
Charge for trading, slippage + commission on every turn.
Real trading isn't free. This deducts a cost proportional to how much you trade (turnover), in basis points, so the backtest reflects net, not gross, performance.
\text{cost}_t = \frac{\text{bps}}{10{,}000}\;\times\;\text{turnover}_t, \qquad \text{turnover}_t = \tfrac12\sum_i \lvert w_{i,t}-w_{i,t^-}\rvert4 Projection calibration, pooled across the walk
Every rebalance carried a Monte Carlo cone and a 95% VaR estimated before the segment it is scored against. Two questions, pooled over the whole study: did realized outcomes land inside the band as often as the band claims, and were VaR breaches as frequent as 5%?
This section is produced by the forward tester itself: every portfolio backtest fits the cone and the VaR estimate at each rebalance and scores them against the segment that followed. It does not require, and this circuit does not contain, a Monte Carlo primitive; that primitive is a separate, standalone analysis.
| Arm | Steps | Rebalances | In band | Coverage | Expected | VaR days | Breach rate | Expected |
|---|---|---|---|---|---|---|---|---|
| Radar-tilted blend | 20 | 95 | 71 / 80 | 88.8% ±3.53 | 90.0% | 4951 | 6.56% ±0.352 | 5.0% |
| Fixed 34/33/33 blend | 20 | 95 | 71 / 80 | 88.8% ±3.53 | 90.0% | 4951 | 6.26% ±0.344 | 5.0% |
± values are binomial standard errors on the estimate. A coverage figure below the expected band means the projection was over-confident; a breach rate above 5% means the same of the risk model. Both forecasts used only data prior to the segment scored.
5 Discussion
5.1 Findings
On the stitched record the radar compounded at 10.43 percent a year against 9.57 for the fixed portfolio and 9.51 for the equal-weight index, on a Sharpe ratio of 0.55 against 0.52 and 0.54 (Table 2). The radar's worst drawdown was 55.0 percent against 57.2 for the fixed portfolio and 60.7 for the index; all three are the fall from mid-2007 to March 2009, so the drawdown gap is one observation where the annual gap has twenty.
The radar led in nine of the twenty windows and trailed in eleven (Tables 3 and 4). Five windows carry the lead: 10.2 points in 2021, 8.7 in 2016, 7.7 in 2008 and 5.8 in each of 2014 and 2019, 38.2 points between them; the other four, 2009, 2011, 2018 and 2024, added 11.1. The eleven windows the fixed portfolio led cost 35.9 points in total, 2007's 7.9 the largest and the rest one to four at a time. A block bootstrap of the daily differences, 2,000 paths in ten-day blocks, puts the radar ahead in 72.8 percent of paths; the paired difference runs at a Sharpe ratio of 0.13 over the twenty years, a lean and not a certainty. With the three rehearsed windows set aside, 2006, 2020 and 2022, all three of which the fixed portfolio won, the other seventeen compound at 11.76 percent a year for the radar against 10.26 for the fixed portfolio, a gap of 1.50.
The 2008 window is the radar's best case and its bill in one. The radar called choppy from January 2008 and stressed from October, held quality-heavy portfolios through the crash, and lost 30.3 percent against 38.0 for the fixed portfolio and 39.1 for the index. The cushion was paid for on both sides. In 2007 the call turned choppy in July while the market still rose, and the radar gave up 7.9 points to the fixed portfolio. In 2009 the radar held its stressed map through the whole year and caught 20.6 percent of a 39.9 percent index rebound, 1.3 points more than the fixed portfolio, because the names that led the rebound were the ones a quality portfolio does not hold. Compounded over 2007 to 2009 the radar ended at 85.3 cents on the dollar against 80.9, 5.4 percent of equity ahead over the crisis cycle; the sum of the three window gaps, 1.1 points, understates it because 2008 shrank the base the 2009 gap was earned on. The tilt also cut the radar's 2008 turnover to 2.7 times equity against 3.6 for the fixed portfolio: a quality-leaning score changed fewer names quarter to quarter through the crash.
The two most recent crises show the limit, and it is the same limit both times: the detector is right about the regime and late about the date, by up to one quarter. In 2020 the January call was calm, so the momentum map rode through the February and March fall, 34.5 percent down against the fixed portfolio's 34.4; the April call was stressed, after the bottom, and the quality map sat out the rebound; the radar finished 1.6 points behind the fixed portfolio, while both beat the index's 12.4. In 2022 the call was choppy through June and stressed from July, the portfolio leaned to quality and away from momentum, and a rate-driven decline that repriced long-duration quality made it the worst of the three: 12.4 percent down against 9.7 for the fixed portfolio and 11.7 for the index. The VIX measures how much the market is moving; 2022 moved for a reason the three maps were not built for.
Outside the crises the lead comes from the years the call matched the year. In 2016 the radar called choppy in January and calm from April, leaned to momentum, and led by 8.7 points; in 2019 stressed in January and calm through the middle of the year, 5.8 points; in 2021 choppy for three quarters and calm in July, 10.2 points; in 2014 calm for three quarters, 5.8 points. The portfolios carried the same risk, annualised volatility of 22.6 percent against 22.4, and the same quarterly turnover, 4.2 times equity a year against 4.1, so the ten-basis-point charge cost them the same, 0.42 and 0.41 points a year. The charge matters for the claim against the index, which pays none: at 25 basis points one way the radar's lead over the index shrinks from 0.92 of a point to about 0.3, and at about 32 basis points it is gone; the lead over the fixed portfolio is nearly untouched at any charge, because both pay it. Per-window risk calibration read the same in both arms, 88.8 percent coverage of the 90 percent projection bands and daily 5 percent VaR breached on 6.56 and 6.26 percent of days: the cone and the VaR were slightly over-confident, equally for both, and nothing in the comparison comes from one arm being modelled more tightly than the other.
5.2 Interpretation
The factor-timing literature is sceptical for good reasons. Asness (2016) found the signals that seem to time factors weak, unstable and largely priced in, and warned practitioners off. Moreira and Muir (2017) showed that scaling exposure by recent volatility raises risk-adjusted returns, which is the case for reading the VIX at all. This study sits between the two: one rule, fixed in advance, lands on the positive side at 0.86 of a point a year and 72.8 percent of 2,000 paths, no more. The drawdown gap, 55.0 percent against the index's 60.7, is what the tilt was bought for, and it showed up in the one crisis deep enough to set the figure, 2007 to 2009; the 2020 fall, which the detector met late, cost both arms the same, 34.5 percent against 34.4.
The mechanism explains the bills. The stressed map is a move to quality and away from momentum, and the record charges that move at the same place every time, the rebound. Daniel and Moskowitz (2016) showed that the rallies after panics are led by the names that fell hardest; a portfolio that has just rotated into quality holds few of them, so the shelter it bought in the crash keeps it out of the recovery. That is 2009 and 2020. The quality tilt has a second failure: quality is long-duration cash flow, and 2022 repriced duration, so the move to quality landed in the year's worst names.
What the record gives a reader is the price list. Every node in both portfolios is a shipped QuanterLab primitive, the VIX classifier and the tilt node included, at the platform's house thresholds and the node's default regime adjustment, with the tilt node set to follow the classifier alone; the walk was registered window by window on point-in-time membership with filings gated by acceptance date; and the platform prices the tilt's habits year by year, so a reader who wants the 2008-shaped cushion can see what it cost in 2007, 2009 and 2022 before buying it.
Two registered companions take the question further on the same chassis: one swaps the detector behind the tilt, the trailing VIX rule here against a fitted hidden Markov model; the other keeps the detector and swaps the response, rotating the factor weights against cutting exposure. They follow this paper.
No search record exists for this study: the design was not promoted from a recorded evolving search, so the number of alternatives tried before it is UNKNOWN, which is a different fact from one. No count of alternatives tried is claimed, and nothing is corrected for a search that was never recorded; the number that stands is the raw out-of-sample result plus this disclosure. The out-of-sample windows are historical.
5.3 Limitations
A paired-difference Sharpe ratio of 0.13 over twenty years does not certify the lead. The pre-2010 record is four windows, two led by each side, and it is also the thinnest data of the walk, about 380 ranked names in 2008 against more than 500 after 2020, in both arms alike, so the paper's most-cited window and its thinnest coverage are the same period. The detector is one reading of the VIX at house thresholds and the three weight maps follow from the node's default adjustment; other thresholds or adjustments were not run. The crisis-year readings are descriptions of this record after the fact. Dividends are credited gross of tax; costs are a flat ten basis points with no market impact; the portfolios are thirty concentrated names, not diversified factor portfolios. Three rehearsal runs at the 2006, 2020 and 2022 anchors preceded registration, so those three windows were seen once before the walk; the lead without them is stated in the findings.
References
- Gelman, A., & Loken, E. (2013). The garden of forking paths: Why multiple comparisons can be a problem, even when there is no “fishing expedition.” Working paper, Columbia University.
- Harvey, C. R., Liu, Y., & Zhu, H. (2016). … and the Cross-Section of Expected Returns. Review of Financial Studies, 29(1), 5–68. doi:10.1093/rfs/hhv059
- Lo, A. W. (2002). The Statistics of Sharpe Ratios. Financial Analysts Journal, 58(4), 36–52. doi:10.2469/faj.v58.n4.2453
- Asness, C. S. (2016). The Siren Song of Factor Timing. Journal of Portfolio Management 42(5).
- Moreira, A. and Muir, T. (2017). Volatility-Managed Portfolios. Journal of Finance 72(4).
- Daniel, K. and Moskowitz, T. J. (2016). Momentum Crashes. Journal of Financial Economics 122(2).
- Whaley, R. E. (2009). Understanding the VIX. Journal of Portfolio Management 35(3).
- Fama, E. F. and French, K. R. (2015). A Five-Factor Asset Pricing Model. Journal of Financial Economics 116(1).
Appendix A Reproducibility in QuanterLab
Each step is backed by a frozen run report. The study is re-derivable from the ledger below.
| # | Commit | Report | Anchor | OOS window |
|---|---|---|---|---|
| 1 | 35f8f68156b8 | 1263 | 2006-01-01 | 2006-01-03 → 2006-12-29 |
| 2 | eac8f7549147 | 1264 | 2007-01-01 | 2007-01-03 → 2007-12-31 |
| 3 | fb20b71bb305 | 1265 | 2008-01-01 | 2008-01-02 → 2008-12-31 |
| 4 | 32b718018520 | 1266 | 2009-01-01 | 2009-01-02 → 2009-12-31 |
| 5 | 64ce8a0ab70d | 1267 | 2010-01-01 | 2010-01-04 → 2010-12-31 |
| 6 | cd086e41f2bc | 1268 | 2011-01-01 | 2011-01-03 → 2011-12-30 |
| 7 | 85082174f701 | 1269 | 2012-01-01 | 2012-01-03 → 2012-12-31 |
| 8 | d8b29d9be049 | 1270 | 2013-01-01 | 2013-01-02 → 2013-12-31 |
| 9 | 65b05b9768ae | 1271 | 2014-01-01 | 2014-01-02 → 2014-12-31 |
| 10 | 827c7d1b2dea | 1272 | 2015-01-01 | 2015-01-02 → 2015-12-31 |
| 11 | 18e910809af9 | 1273 | 2016-01-01 | 2016-01-04 → 2016-12-30 |
| 12 | 057f0f126536 | 1274 | 2017-01-01 | 2017-01-03 → 2017-12-29 |
| 13 | fc0d1d217857 | 1275 | 2018-01-01 | 2018-01-02 → 2018-12-31 |
| 14 | cbf2f1c63f6e | 1276 | 2019-01-01 | 2019-01-02 → 2019-12-31 |
| 15 | 886521964b77 | 1277 | 2020-01-01 | 2020-01-02 → 2020-12-31 |
| 16 | 7ddcd4a4ec05 | 1278 | 2021-01-01 | 2021-01-04 → 2021-12-31 |
| 17 | eb92ab80b825 | 1279 | 2022-01-01 | 2022-01-03 → 2022-12-30 |
| 18 | 7cace02a327c | 1280 | 2023-01-01 | 2023-01-03 → 2023-12-29 |
| 19 | c84ad5a600eb | 1281 | 2024-01-01 | 2024-01-02 → 2024-12-31 |
| 20 | 1301fff4bc45 | 1282 | 2025-01-01 | 2025-01-02 → 2025-12-31 |
Appendix A2 Registration record
What this record does and does not establish. Every window in this study is historical: the data existed before the study began, so this is sequential sealing on past windows, not pre-registration in the clinical-trial sense, and no procedure could make it so. What the platform does enforce is order, each step's specification was frozen and hashed before that step was scored, and the walk cannot advance past a step that was never run or close one with a result registered for a different window. The two timestamp columns below are the evidence: read them together and each seal precedes its own run, and each run precedes the next seal. A study whose seals all post-date its runs would show it here. Wall-clock spacing between seals varies with the author's schedule and queue latency; the ordering, not the tempo, is the claim.
“A COMPARATIVE study, Radar-tilted blend vs Fixed 34/33/33 blend, walked on the same registered out-of-sample windows. Radar-tilted blend: S&P 500, rebalanced quarterly across the selected basket, conditioned on the wired regime classifier, and run out-of-sample from the anchor, whatever the design estimates from history is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. Fixed 34/33/33 blend: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor, whatever the design estimates from history is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. The arms differ in: 2 places, VIX Regime, removed in Fixed 34/33/33 blend; Regime Tilt (radar), removed in Fixed 34/33/33 blend. NOTE: with more than one difference, an out-of-sample gap cannot be attributed to any single change. The contrast under test: whether Radar-tilted blend generates better risk-adjusted returns than Fixed 34/33/33 blend over the identical out-of-sample windows.”
The same hypothesis was registered independently at every step, hashed before each step's out-of-sample window was scored:
| # | Anchor | Registered at (UTC) | Run completed (UTC) |
|---|---|---|---|
| 1 | 2006-01-01 | 2026-08-17 09:17:35 | 2026-08-17 09:34:19 |
| 2 | 2007-01-01 | 2026-08-17 09:34:24 | 2026-08-17 09:53:05 |
| 3 | 2008-01-01 | 2026-08-17 09:53:11 | 2026-08-17 10:09:55 |
| 4 | 2009-01-01 | 2026-08-17 10:10:00 | 2026-08-17 10:30:45 |
| 5 | 2010-01-01 | 2026-08-17 10:30:50 | 2026-08-17 10:51:31 |
| 6 | 2011-01-01 | 2026-08-17 10:51:37 | 2026-08-17 11:12:59 |
| 7 | 2012-01-01 | 2026-08-17 11:13:04 | 2026-08-17 11:31:26 |
| 8 | 2013-01-01 | 2026-08-17 11:31:32 | 2026-08-17 11:53:33 |
| 9 | 2014-01-01 | 2026-08-17 11:53:38 | 2026-08-17 12:16:02 |
| 10 | 2015-01-01 | 2026-08-17 12:16:07 | 2026-08-17 12:39:32 |
| 11 | 2016-01-01 | 2026-08-17 12:39:37 | 2026-08-17 12:59:59 |
| 12 | 2017-01-01 | 2026-08-17 13:00:04 | 2026-08-17 13:24:54 |
| 13 | 2018-01-01 | 2026-08-17 13:24:59 | 2026-08-17 13:50:04 |
| 14 | 2019-01-01 | 2026-08-17 13:50:10 | 2026-08-17 14:56:29 |
| 15 | 2020-01-01 | 2026-08-17 14:56:34 | 2026-08-17 15:17:35 |
| 16 | 2021-01-01 | 2026-08-17 15:17:41 | 2026-08-17 15:43:24 |
| 17 | 2022-01-01 | 2026-08-17 15:43:30 | 2026-08-17 16:08:52 |
| 18 | 2023-01-01 | 2026-08-17 16:08:57 | 2026-08-17 16:34:19 |
| 19 | 2024-01-01 | 2026-08-17 16:34:24 | 2026-08-17 16:55:26 |
| 20 | 2025-01-01 | 2026-08-17 16:55:31 | 2026-08-17 17:20:53 |
Appendix B Per-step diagnostics
Realized in the projection tables below is the risk engine scoring its own forecast: the buy-and-hold return of the segment that followed each rebalance, on the same gross basis the cone was projected on. It is deliberately not the charged, calendar-window total return the study’s tables print, so the two will not reconcile line by line; the cone and its outcome share one basis, which is what a calibration test requires. Each row names its segment’s span so a boundary session is visible.
Names held is the union across the window: the count of distinct instruments the book touched between the window’s first and last session, not the number it held at one time. A book that rotates monthly touches more names than it holds.
What each step's run actually did beyond its return: capital allocation across lanes and regimes, the portfolio book's rebalancing and cost drag, and how positions were sized. Harvested from the frozen run reports, present where the circuit produced them. Cost drag is the gap between the step's return before and after its trading costs, in percentage points of the step's starting capital, so on a book that trades every session and compounds it can exceed the step's own net return.
Open the full per-step grid (20 steps: every rebalance, capital routing and sizing, per window)
Step 1 · 2006-01-03 → 2006-12-29
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 68 names held · selection: reselect · 0.0% in cash · turnover 3.9× · cost drag 0.39% · 1 name dropped at load (69 selected, 68 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.67% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2006-01-01 → 2006-04-01 | -3.0357% | 10.5158% | 27.4784% | 9.6752% | yes | 1.6827% | 2 / 61 |
| 2006-04-01 → 2006-07-01 | -6.7421% | 8.7898% | 27.0222% | -7.3114% | no | 1.8459% | 6 / 62 |
| 2006-07-01 → 2006-10-01 | -5.7458% | 9.8073% | 28.0404% | -3.178% | yes | 1.8818% | 4 / 62 |
| 2006-10-01 → 2007-01-01 | -6.1385% | 6.7579% | 21.5173% | 9.6669% | yes | 1.4809% | 2 / 62 |
| 2007-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 67 names held · selection: reselect · 0.0% in cash · turnover 4.2× · cost drag 0.42% · 1 name dropped at load (68 selected, 67 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.67% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2006-01-01 → 2006-04-01 | -3.3886% | 10.0245% | 26.7997% | 6.007% | yes | 1.752% | 2 / 61 |
| 2006-04-01 → 2006-07-01 | -6.2739% | 8.1594% | 24.9192% | -6.0709% | yes | 1.7141% | 7 / 62 |
| 2006-07-01 → 2006-10-01 | -5.7475% | 7.3314% | 22.3175% | 1.0685% | yes | 1.5504% | 5 / 62 |
| 2006-10-01 → 2007-01-01 | -6.2902% | 6.343% | 20.7679% | 9.6953% | yes | 1.577% | 0 / 62 |
| 2007-01-01 | no segment follows this rebalance, not scored | ||||||
Step 2 · 2007-01-03 → 2007-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 65 names held · selection: reselect · 0.0% in cash · turnover 3.8× · cost drag 0.38%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 13.36% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2007-01-01 → 2007-04-01 | -5.7292% | 7.3203% | 20.7357% | 5.292% | yes | 1.5076% | 5 / 60 |
| 2007-04-01 → 2007-07-01 | -5.1155% | 6.6799% | 20.0234% | -0.5082% | yes | 1.3519% | 5 / 62 |
| 2007-07-01 → 2007-10-01 | -5.5753% | 5.2806% | 17.4589% | -1.9379% | yes | 1.3042% | 13 / 62 |
| 2007-10-01 → 2008-01-01 | -8.0228% | 5.0336% | 18.5523% | -6.7135% | yes | 1.4999% | 10 / 63 |
| 2008-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 61 names held · selection: reselect · 0.0% in cash · turnover 4.2× · cost drag 0.42% · 1 name dropped at load (62 selected, 61 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 11.34% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2007-01-01 → 2007-04-01 | -6.0766% | 7.6715% | 21.8992% | 8.1089% | yes | 1.579% | 3 / 60 |
| 2007-04-01 → 2007-07-01 | -5.9061% | 6.7521% | 21.202% | 2.4898% | yes | 1.4433% | 2 / 62 |
| 2007-07-01 → 2007-10-01 | -4.3386% | 7.9479% | 21.8981% | -1.3223% | yes | 1.3668% | 13 / 62 |
| 2007-10-01 → 2008-01-01 | -7.4591% | 7.0603% | 22.2812% | -4.6952% | yes | 1.5894% | 10 / 63 |
| 2008-01-01 | no segment follows this rebalance, not scored | ||||||
Step 3 · 2008-01-02 → 2008-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 4 constructions · 46 names held · selection: reselect · 0.0% in cash · turnover 2.7× · cost drag 0.27%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 20.48% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2008-01-01 → 2008-04-01 | -9.5628% | 3.4897% | 16.9746% | -5.0979% | yes | 1.5472% | 13 / 60 |
| 2008-04-01 → 2008-07-01 | -11.7252% | 3.126% | 18.8404% | -3.7119% | yes | 1.8271% | 7 / 63 |
| 2008-07-01 → 2008-10-01 | -14.2945% | 2.1724% | 19.9362% | -1.7792% | yes | 2.0457% | 10 / 63 |
| 2008-10-01 → window end | -18.6644% | -0.6598% | 19.2163% | -22.5073% | no | 2.3654% | 21 / 63 |
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 4 constructions · 65 names held · selection: reselect · 0.0% in cash · turnover 3.6× · cost drag 0.36% · 2 names dropped at load (67 selected, 65 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 19.28% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2008-01-01 → 2008-04-01 | -8.8547% | 5.3743% | 20.2186% | -10.6777% | no | 1.68% | 12 / 60 |
| 2008-04-01 → 2008-07-01 | -11.0487% | 5.6595% | 23.6216% | 1.5751% | yes | 2.02% | 4 / 63 |
| 2008-07-01 → 2008-10-01 | -12.3531% | 5.0278% | 23.8701% | -11.6704% | yes | 2.1141% | 11 / 63 |
| 2008-10-01 → window end | -14.5009% | 2.8948% | 21.8304% | -24.1421% | no | 2.2255% | 21 / 63 |
Step 4 · 2009-01-02 → 2009-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 45 names held · selection: reselect · 0.0% in cash · turnover 2.4× · cost drag 0.24%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.24% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2009-01-01 → 2009-04-01 | -26.2933% | -2.625% | 25.408% | -11.0473% | yes | 3.1312% | 10 / 60 |
| 2009-04-01 → 2009-07-01 | -27.4254% | -4.119% | 26.8772% | 13.9453% | yes | 3.1073% | 3 / 62 |
| 2009-07-01 → 2009-10-01 | -27.9022% | -2.3521% | 28.7731% | 14.5851% | yes | 3.1152% | 0 / 63 |
| 2009-10-01 → 2010-01-01 | -30.6414% | -0.9263% | 37.153% | 4.6589% | yes | 4.0066% | 0 / 63 |
| 2010-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 56 names held · selection: reselect · 0.0% in cash · turnover 3.2× · cost drag 0.32%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 4.84% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2009-01-01 → 2009-04-01 | -23.1207% | -0.5021% | 25.7687% | -12.3058% | yes | 2.6718% | 10 / 60 |
| 2009-04-01 → 2009-07-01 | -24.2792% | -1.7703% | 27.6226% | 12.1238% | yes | 2.8933% | 2 / 62 |
| 2009-07-01 → 2009-10-01 | -28.1538% | -1.1823% | 32.1595% | 14.1247% | yes | 3.428% | 0 / 63 |
| 2009-10-01 → 2010-01-01 | -29.1492% | 0.7109% | 38.7981% | 6.354% | yes | 3.8561% | 0 / 63 |
| 2010-01-01 | no segment follows this rebalance, not scored | ||||||
Step 5 · 2010-01-04 → 2010-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 62 names held · selection: reselect · 0.0% in cash · turnover 3.7× · cost drag 0.37%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.81% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2010-01-01 → 2010-04-01 | -28.138% | 1.8465% | 39.8105% | 8.2259% | yes | 3.757% | 0 / 60 |
| 2010-04-01 → 2010-07-01 | -27.0807% | 2.3899% | 44.055% | -17.6148% | yes | 3.9628% | 2 / 62 |
| 2010-07-01 → 2010-10-01 | -27.6446% | 1.8757% | 39.1904% | 7.4647% | yes | 3.8% | 0 / 63 |
| 2010-10-01 → 2011-01-01 | -23.7944% | 4.3136% | 38.9026% | 11.8906% | yes | 3.3158% | 0 / 63 |
| 2011-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 68 names held · selection: reselect · 0.0% in cash · turnover 4.0× · cost drag 0.4%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.0% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2010-01-01 → 2010-04-01 | -29.6699% | 2.511% | 44.3552% | 8.8093% | yes | 4.0487% | 0 / 60 |
| 2010-04-01 → 2010-07-01 | -28.6304% | 2.796% | 48.3749% | -19.3119% | yes | 4.553% | 0 / 62 |
| 2010-07-01 → 2010-10-01 | -29.0632% | 4.0035% | 47.4411% | 8.7558% | yes | 4.176% | 0 / 63 |
| 2010-10-01 → 2011-01-01 | -26.5928% | 5.7876% | 47.6326% | 13.7996% | yes | 4.202% | 0 / 63 |
| 2011-01-01 | no segment follows this rebalance, not scored | ||||||
Step 6 · 2011-01-03 → 2011-12-30
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 71 names held · selection: reselect · 0.0% in cash · turnover 5.0× · cost drag 0.5%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.45% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2011-01-01 → 2011-04-01 | -14.1345% | 8.9027% | 41.1581% | 6.8767% | yes | 2.8106% | 0 / 61 |
| 2011-04-01 → 2011-07-01 | -9.5838% | 12.7904% | 40.8822% | 2.0839% | yes | 2.6002% | 0 / 62 |
| 2011-07-01 → 2011-10-01 | -7.5353% | 12.5633% | 34.6821% | -21.7819% | no | 2.1093% | 13 / 63 |
| 2011-10-01 → 2012-01-01 | -14.2601% | 2.5749% | 22.8434% | 15.897% | yes | 2.2833% | 3 / 62 |
| 2012-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 69 names held · selection: reselect · 0.0% in cash · turnover 4.4× · cost drag 0.44% · 1 name dropped at load (70 selected, 69 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.47% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2011-01-01 → 2011-04-01 | -14.0781% | 10.6854% | 45.9294% | 4.8904% | yes | 3.1305% | 1 / 61 |
| 2011-04-01 → 2011-07-01 | -9.7412% | 14.971% | 46.6553% | -0.1967% | yes | 2.8994% | 0 / 62 |
| 2011-07-01 → 2011-10-01 | -6.8496% | 9.9086% | 27.8096% | -18.1206% | no | 1.8687% | 13 / 63 |
| 2011-10-01 → 2012-01-01 | -12.5146% | 4.9448% | 26.0218% | 12.6174% | yes | 2.2752% | 7 / 62 |
| 2012-01-01 | no segment follows this rebalance, not scored | ||||||
Step 7 · 2012-01-03 → 2012-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 4 constructions · 63 names held · selection: reselect · 0.0% in cash · turnover 4.7× · cost drag 0.47% · 1 name dropped at load (64 selected, 63 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.03% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2012-01-01 → 2012-04-01 | -11.2848% | 4.4213% | 24.7553% | 13.0804% | yes | 2.1375% | 0 / 61 |
| 2012-04-01 → 2012-07-01 | -7.7251% | 9.3425% | 29.695% | -3.5301% | yes | 1.9933% | 5 / 62 |
| 2012-07-01 → 2012-10-01 | -12.4177% | 3.6459% | 22.7759% | 1.5097% | yes | 2.0655% | 0 / 62 |
| 2012-10-01 → window end | -10.6921% | 5.6797% | 26.9941% | 1.1487% | yes | 2.1812% | 0 / 61 |
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 4 constructions · 63 names held · selection: reselect · 0.0% in cash · turnover 4.2× · cost drag 0.42% · 1 name dropped at load (64 selected, 63 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.63% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2012-01-01 → 2012-04-01 | -10.5806% | 5.9352% | 27.4633% | 14.1337% | yes | 2.1473% | 0 / 61 |
| 2012-04-01 → 2012-07-01 | -9.2089% | 8.053% | 28.7269% | -2.831% | yes | 2.0798% | 4 / 62 |
| 2012-07-01 → 2012-10-01 | -11.58% | 4.4764% | 23.5682% | 2.0167% | yes | 1.9894% | 0 / 62 |
| 2012-10-01 → window end | -11.917% | 5.5365% | 28.558% | 2.3511% | yes | 2.1869% | 0 / 61 |
Step 8 · 2013-01-02 → 2013-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 78 names held · selection: reselect · 0.0% in cash · turnover 6.0× · cost drag 0.6%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.02% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2013-01-01 → 2013-04-01 | -11.0583% | 5.744% | 22.6622% | 10.4072% | yes | 1.8638% | 1 / 59 |
| 2013-04-01 → 2013-07-01 | -11.1743% | 9.4839% | 32.489% | 5.2386% | yes | 2.3137% | 2 / 63 |
| 2013-07-01 → 2013-10-01 | -13.1901% | 5.8302% | 26.7908% | 5.9745% | yes | 2.2509% | 1 / 63 |
| 2013-10-01 → 2014-01-01 | -4.1277% | 11.6102% | 28.2073% | 9.715% | yes | 1.7719% | 1 / 63 |
| 2014-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 68 names held · selection: reselect · 0.0% in cash · turnover 4.6× · cost drag 0.46%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.82% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2013-01-01 → 2013-04-01 | -11.2335% | 6.9035% | 25.3843% | 11.9704% | yes | 1.9903% | 2 / 59 |
| 2013-04-01 → 2013-07-01 | -10.6479% | 8.4763% | 29.4678% | 5.5616% | yes | 2.2431% | 2 / 63 |
| 2013-07-01 → 2013-10-01 | -13.4074% | 7.4316% | 30.7833% | 6.7718% | yes | 2.3491% | 1 / 63 |
| 2013-10-01 → 2014-01-01 | -4.6699% | 10.6137% | 26.6811% | 7.8466% | yes | 1.7613% | 2 / 63 |
| 2014-01-01 | no segment follows this rebalance, not scored | ||||||
Step 9 · 2014-01-02 → 2014-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 76 names held · selection: reselect · 0.0% in cash · turnover 4.7× · cost drag 0.47%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.85% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2014-01-01 → 2014-04-01 | -3.4289% | 12.4913% | 29.2196% | 4.8337% | yes | 1.7573% | 3 / 60 |
| 2014-04-01 → 2014-07-01 | -1.3729% | 14.2764% | 32.5221% | 3.2082% | yes | 1.6972% | 6 / 62 |
| 2014-07-01 → 2014-10-01 | -2.8093% | 11.8802% | 27.2064% | -0.6606% | yes | 1.5827% | 4 / 63 |
| 2014-10-01 → 2015-01-01 | -4.2609% | 7.3032% | 19.0647% | 13.5873% | yes | 1.2887% | 4 / 63 |
| 2015-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 71 names held · selection: reselect · 0.0% in cash · turnover 4.8× · cost drag 0.48%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.65% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2014-01-01 → 2014-04-01 | -4.4316% | 10.3907% | 25.8412% | 2.6791% | yes | 1.5668% | 3 / 60 |
| 2014-04-01 → 2014-07-01 | -6.0761% | 7.5186% | 23.1777% | 1.0021% | yes | 1.6543% | 3 / 62 |
| 2014-07-01 → 2014-10-01 | -3.2626% | 10.3168% | 24.3583% | 2.4426% | yes | 1.5664% | 2 / 63 |
| 2014-10-01 → 2015-01-01 | -3.1367% | 9.7093% | 22.9063% | 10.124% | yes | 1.4375% | 6 / 63 |
| 2015-01-01 | no segment follows this rebalance, not scored | ||||||
Step 10 · 2015-01-02 → 2015-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 58 names held · selection: reselect · 0.0% in cash · turnover 3.7× · cost drag 0.37%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.06% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2015-01-01 → 2015-04-01 | -5.8054% | 5.5232% | 16.9926% | 1.9782% | yes | 1.2328% | 5 / 60 |
| 2015-04-01 → 2015-07-01 | -2.0696% | 9.5816% | 22.6993% | -1.3543% | yes | 1.3653% | 3 / 62 |
| 2015-07-01 → 2015-10-01 | -5.8289% | 5.8326% | 17.7239% | -5.9516% | no | 1.35% | 7 / 63 |
| 2015-10-01 → 2016-01-01 | -8.7054% | 3.1291% | 15.2564% | 0.7176% | yes | 1.4411% | 5 / 63 |
| 2016-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 64 names held · selection: reselect · 0.0% in cash · turnover 3.6× · cost drag 0.36%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 9.68% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2015-01-01 → 2015-04-01 | -3.5917% | 8.5489% | 20.8996% | 2.1932% | yes | 1.3142% | 5 / 60 |
| 2015-04-01 → 2015-07-01 | -2.6525% | 9.3712% | 22.9632% | 0.3367% | yes | 1.4236% | 2 / 62 |
| 2015-07-01 → 2015-10-01 | -3.4867% | 8.5902% | 20.9187% | -6.5078% | no | 1.3501% | 10 / 63 |
| 2015-10-01 → 2016-01-01 | -6.8306% | 6.0168% | 19.2738% | 2.7582% | yes | 1.4722% | 7 / 63 |
| 2016-01-01 | no segment follows this rebalance, not scored | ||||||
Step 11 · 2016-01-04 → 2016-12-30
Radar-tilted blend
Portfolio book, rebalanced quarterly · 4 constructions · 78 names held · selection: reselect · 0.0% in cash · turnover 5.1× · cost drag 0.51% · 1 name dropped at load (79 selected, 78 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.65% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2016-01-01 → 2016-04-01 | -8.8288% | 2.7181% | 14.4719% | 5.181% | yes | 1.3426% | 8 / 60 |
| 2016-04-01 → 2016-07-01 | -6.2578% | 6.207% | 19.0161% | -0.3326% | yes | 1.401% | 2 / 63 |
| 2016-07-01 → 2016-10-01 | -6.1798% | 6.6517% | 19.8799% | 3.7683% | yes | 1.4142% | 3 / 63 |
| 2016-10-01 → window end | -7.1637% | 5.5383% | 20.0676% | 1.0677% | yes | 1.5325% | 1 / 62 |
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 4 constructions · 69 names held · selection: reselect · 0.0% in cash · turnover 4.0× · cost drag 0.4% · 1 name dropped at load (70 selected, 69 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.65% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2016-01-01 → 2016-04-01 | -7.219% | 5.5274% | 18.6198% | 0.503% | yes | 1.4637% | 9 / 60 |
| 2016-04-01 → 2016-07-01 | -6.3565% | 5.5714% | 17.7711% | -0.8082% | yes | 1.3194% | 3 / 63 |
| 2016-07-01 → 2016-10-01 | -7.6075% | 4.7813% | 17.5243% | 0.4452% | yes | 1.3459% | 1 / 63 |
| 2016-10-01 → window end | -8.3922% | 4.3131% | 18.8702% | 1.0611% | yes | 1.606% | 1 / 62 |
Step 12 · 2017-01-03 → 2017-12-29
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 75 names held · selection: reselect · 0.0% in cash · turnover 4.4× · cost drag 0.44%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.43% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2017-01-01 → 2017-04-01 | -11.9267% | 2.4733% | 20.8916% | 3.2926% | yes | 1.9414% | 1 / 61 |
| 2017-04-01 → 2017-07-01 | -10.3173% | 6.1343% | 25.7267% | 3.998% | yes | 2.1087% | 1 / 62 |
| 2017-07-01 → 2017-10-01 | -10.4212% | 5.543% | 24.471% | 7.532% | yes | 2.1459% | 2 / 62 |
| 2017-10-01 → 2018-01-01 | -7.3692% | 7.6956% | 25.3201% | 3.4499% | yes | 1.9092% | 2 / 62 |
| 2018-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 72 names held · selection: reselect · 0.0% in cash · turnover 4.5× · cost drag 0.45%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.81% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2017-01-01 → 2017-04-01 | -11.2699% | 1.4637% | 17.4574% | 4.3941% | yes | 1.7339% | 0 / 61 |
| 2017-04-01 → 2017-07-01 | -7.9718% | 5.6622% | 21.4135% | 1.6775% | yes | 1.7366% | 1 / 62 |
| 2017-07-01 → 2017-10-01 | -9.9328% | 3.5877% | 19.2347% | 8.6174% | yes | 1.8077% | 1 / 62 |
| 2017-10-01 → 2018-01-01 | -8.7043% | 5.5549% | 22.1442% | 5.5559% | yes | 1.932% | 0 / 62 |
| 2018-01-01 | no segment follows this rebalance, not scored | ||||||
Step 13 · 2018-01-02 → 2018-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 69 names held · selection: reselect · 0.0% in cash · turnover 4.2× · cost drag 0.42%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 12.55% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2018-01-01 → 2018-04-01 | -5.7923% | 8.0322% | 22.3434% | 3.931% | yes | 1.6118% | 6 / 60 |
| 2018-04-01 → 2018-07-01 | -6.392% | 6.3477% | 19.4736% | 8.8275% | yes | 1.3967% | 5 / 63 |
| 2018-07-01 → 2018-10-01 | -5.7716% | 6.3987% | 20.2256% | 10.3252% | yes | 1.4485% | 1 / 62 |
| 2018-10-01 → 2019-01-01 | -2.3905% | 9.8027% | 23.6036% | -20.7487% | no | 1.282% | 19 / 62 |
| 2019-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 66 names held · selection: reselect · 0.0% in cash · turnover 3.9× · cost drag 0.39%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 12.96% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2018-01-01 → 2018-04-01 | -6.5966% | 6.506% | 19.9971% | 1.2098% | yes | 1.5746% | 6 / 60 |
| 2018-04-01 → 2018-07-01 | -4.7496% | 9.0763% | 23.4299% | 7.2622% | yes | 1.4057% | 5 / 63 |
| 2018-07-01 → 2018-10-01 | -5.2602% | 6.9641% | 20.851% | 9.2537% | yes | 1.5395% | 1 / 62 |
| 2018-10-01 → 2019-01-01 | -3.8432% | 8.3351% | 22.1405% | -20.5812% | no | 1.3566% | 20 / 62 |
| 2019-01-01 | no segment follows this rebalance, not scored | ||||||
Step 14 · 2019-01-02 → 2019-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 74 names held · selection: reselect · 0.0% in cash · turnover 5.3× · cost drag 0.53%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 4.84% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2019-01-01 → 2019-04-01 | -8.8875% | 3.22% | 15.6094% | 16.5654% | no | 1.4158% | 3 / 60 |
| 2019-04-01 → 2019-07-01 | -6.2448% | 5.7172% | 19.2887% | -0.9547% | yes | 1.4329% | 4 / 62 |
| 2019-07-01 → 2019-10-01 | -4.942% | 6.1569% | 17.4065% | -1.2489% | yes | 1.3031% | 5 / 63 |
| 2019-10-01 → 2020-01-01 | -8.2993% | 4.8339% | 18.4464% | 9.0434% | yes | 1.6363% | 0 / 63 |
| 2020-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 71 names held · selection: reselect · 0.0% in cash · turnover 4.4× · cost drag 0.44%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.24% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2019-01-01 → 2019-04-01 | -8.7711% | 4.9234% | 19.1396% | 13.3402% | yes | 1.5611% | 3 / 60 |
| 2019-04-01 → 2019-07-01 | -6.9038% | 5.6032% | 19.8783% | -2.9171% | yes | 1.4998% | 5 / 62 |
| 2019-07-01 → 2019-10-01 | -5.7261% | 5.3349% | 16.5517% | 0.6352% | yes | 1.2797% | 5 / 63 |
| 2019-10-01 → 2020-01-01 | -7.6004% | 5.2904% | 18.6102% | 7.1961% | yes | 1.7922% | 0 / 63 |
| 2020-01-01 | no segment follows this rebalance, not scored | ||||||
Step 15 · 2020-01-02 → 2020-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 4 constructions · 67 names held · selection: reselect · 0.0% in cash · turnover 3.5× · cost drag 0.35%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 12.05% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2020-01-01 → 2020-04-01 | -7.8417% | 6.8416% | 25.5518% | -21.9946% | no | 2.0833% | 16 / 61 |
| 2020-04-01 → 2020-07-01 | -21.6003% | -2.803% | 20.6518% | 29.9649% | no | 2.4671% | 11 / 62 |
| 2020-07-01 → 2020-10-01 | -15.2782% | 5.7349% | 29.415% | 11.9773% | yes | 2.4724% | 1 / 63 |
| 2020-10-01 → window end | -15.2082% | 5.5172% | 28.8087% | 9.7631% | yes | 2.4139% | 2 / 63 |
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 4 constructions · 68 names held · selection: reselect · 0.0% in cash · turnover 4.2× · cost drag 0.42%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 10.44% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2020-01-01 → 2020-04-01 | -8.2222% | 5.9811% | 24.0048% | -21.0299% | no | 1.9654% | 16 / 61 |
| 2020-04-01 → 2020-07-01 | -20.4457% | -0.8872% | 23.6376% | 32.7637% | no | 2.5813% | 7 / 62 |
| 2020-07-01 → 2020-10-01 | -13.4148% | 8.2087% | 32.6085% | 9.615% | yes | 2.4023% | 1 / 63 |
| 2020-10-01 → window end | -14.6111% | 8.2284% | 34.3488% | 7.0589% | yes | 2.5935% | 2 / 63 |
Step 16 · 2021-01-04 → 2021-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 67 names held · selection: reselect · 0.0% in cash · turnover 4.9× · cost drag 0.49%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.02% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2021-01-01 → 2021-04-01 | -13.8531% | 7.3283% | 31.0555% | 4.9504% | yes | 2.4015% | 2 / 60 |
| 2021-04-01 → 2021-07-01 | -13.8245% | 8.0636% | 35.6895% | 9.0672% | yes | 2.2824% | 1 / 62 |
| 2021-07-01 → 2021-10-01 | -20.5499% | 12.9436% | 55.6688% | -0.8171% | yes | 3.2486% | 1 / 63 |
| 2021-10-01 → 2022-01-01 | -13.7486% | 10.4728% | 38.4513% | 8.4484% | yes | 2.2558% | 1 / 63 |
| 2022-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 74 names held · selection: reselect · 0.0% in cash · turnover 4.6× · cost drag 0.46% · 1 name dropped at load (75 selected, 74 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.02% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2021-01-01 → 2021-04-01 | -15.0938% | 8.1922% | 34.8418% | 5.1598% | yes | 2.7168% | 3 / 60 |
| 2021-04-01 → 2021-07-01 | -18.579% | 11.2499% | 52.2828% | 8.7982% | yes | 3.0315% | 1 / 62 |
| 2021-07-01 → 2021-10-01 | -20.5569% | 10.3202% | 48.8404% | -3.8976% | yes | 3.29% | 0 / 63 |
| 2021-10-01 → 2022-01-01 | -16.2244% | 11.8652% | 45.6246% | 4.1282% | yes | 2.9476% | 1 / 63 |
| 2022-01-01 | no segment follows this rebalance, not scored | ||||||
Step 17 · 2022-01-03 → 2022-12-30
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 54 names held · selection: reselect · 0.0% in cash · turnover 2.9× · cost drag 0.29%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.1% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2022-01-01 → 2022-04-01 | -11.3417% | 9.386% | 37.5799% | -8.0768% | yes | 2.1168% | 5 / 61 |
| 2022-04-01 → 2022-07-01 | -15.2498% | 8.6648% | 42.5334% | -16.8232% | no | 2.5126% | 8 / 61 |
| 2022-07-01 → 2022-10-01 | -10.7683% | 8.6867% | 30.1082% | -4.1251% | yes | 2.1853% | 2 / 63 |
| 2022-10-01 → 2023-01-01 | -12.2675% | 6.4574% | 29.3241% | 13.9142% | yes | 2.1015% | 5 / 62 |
| 2023-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 61 names held · selection: reselect · 0.0% in cash · turnover 3.2× · cost drag 0.32%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.07% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2022-01-01 → 2022-04-01 | -13.7728% | 10.7338% | 45.4986% | -6.2325% | yes | 2.5518% | 2 / 61 |
| 2022-04-01 → 2022-07-01 | -16.7223% | 10.1368% | 49.4334% | -17.0044% | no | 2.7459% | 8 / 61 |
| 2022-07-01 → 2022-10-01 | -12.6144% | 11.9588% | 40.3517% | -0.0336% | yes | 2.4685% | 3 / 63 |
| 2022-10-01 → 2023-01-01 | -14.3638% | 9.2688% | 39.621% | 8.518% | yes | 2.8167% | 2 / 62 |
| 2023-01-01 | no segment follows this rebalance, not scored | ||||||
Step 18 · 2023-01-03 → 2023-12-29
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 67 names held · selection: reselect · 0.0% in cash · turnover 4.6× · cost drag 0.46%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.22% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2023-01-01 → 2023-04-01 | -9.6493% | 10.6061% | 37.9324% | 3.4604% | yes | 2.3292% | 2 / 61 |
| 2023-04-01 → 2023-07-01 | -10.8833% | 5.1177% | 25.8799% | 5.0227% | yes | 1.918% | 1 / 61 |
| 2023-07-01 → 2023-10-01 | -14.4228% | 4.9692% | 28.9085% | -6.8122% | yes | 2.4304% | 0 / 62 |
| 2023-10-01 → 2024-01-01 | -15.4278% | 1.3471% | 21.577% | 15.6605% | yes | 2.0082% | 0 / 62 |
| 2024-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 71 names held · selection: reselect · 0.0% in cash · turnover 4.2× · cost drag 0.42%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.81% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2023-01-01 → 2023-04-01 | -11.4722% | 12.2435% | 45.4378% | 1.488% | yes | 2.7967% | 1 / 61 |
| 2023-04-01 → 2023-07-01 | -9.6983% | 6.5899% | 27.7402% | 5.5834% | yes | 1.971% | 0 / 61 |
| 2023-07-01 → 2023-10-01 | -14.1406% | 4.3781% | 27.0351% | -4.5694% | yes | 2.2566% | 0 / 62 |
| 2023-10-01 → 2024-01-01 | -17.0875% | 2.4724% | 26.8027% | 17.0442% | yes | 2.3801% | 1 / 62 |
| 2024-01-01 | no segment follows this rebalance, not scored | ||||||
Step 19 · 2024-01-02 → 2024-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 4 constructions · 69 names held · selection: reselect · 0.0% in cash · turnover 5.1× · cost drag 0.51%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 3.63% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2024-01-01 → 2024-04-01 | -19.3769% | 4.5256% | 32.3337% | 18.6613% | yes | 2.8493% | 0 / 60 |
| 2024-04-01 → 2024-07-01 | -13.1452% | 9.178% | 37.4214% | 1.3522% | yes | 2.6944% | 1 / 62 |
| 2024-07-01 → 2024-10-01 | -7.6291% | 11.7601% | 32.9736% | 5.1315% | yes | 1.7643% | 7 / 63 |
| 2024-10-01 → window end | -8.7702% | 7.1844% | 24.1578% | 0.4954% | yes | 1.6517% | 1 / 63 |
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 4 constructions · 64 names held · selection: reselect · 0.0% in cash · turnover 4.4× · cost drag 0.44%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.82% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2024-01-01 → 2024-04-01 | -17.8733% | 3.6023% | 27.9458% | 16.332% | yes | 2.5804% | 0 / 60 |
| 2024-04-01 → 2024-07-01 | -12.4495% | 6.6087% | 29.9643% | -3.2841% | yes | 2.1692% | 0 / 62 |
| 2024-07-01 → 2024-10-01 | -8.0621% | 9.3473% | 28.0861% | 8.4761% | yes | 1.6795% | 6 / 63 |
| 2024-10-01 → window end | -8.293% | 9.0928% | 27.8094% | 0.7212% | yes | 1.8591% | 1 / 63 |
Step 20 · 2025-01-02 → 2025-12-31
Radar-tilted blend
Portfolio book, rebalanced quarterly · 5 constructions · 50 names held · selection: reselect · 0.0% in cash · turnover 3.1× · cost drag 0.31%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 7.72% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2025-01-01 → 2025-04-01 | -4.9237% | 8.5672% | 21.6531% | -4.6048% | yes | 1.4355% | 9 / 59 |
| 2025-04-01 → 2025-07-01 | -6.6561% | 4.8521% | 19.0389% | 9.5707% | yes | 1.5746% | 7 / 61 |
| 2025-07-01 → 2025-10-01 | -6.9659% | 6.4157% | 20.2927% | 4.5435% | yes | 1.4167% | 1 / 63 |
| 2025-10-01 → 2026-01-01 | -9.3961% | 6.4525% | 23.3137% | 5.1183% | yes | 1.643% | 2 / 63 |
| 2026-01-01 | no segment follows this rebalance, not scored | ||||||
Fixed 34/33/33 blend
Portfolio book, rebalanced quarterly · 5 constructions · 62 names held · selection: reselect · 0.0% in cash · turnover 3.8× · cost drag 0.38%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.94% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2025-01-01 → 2025-04-01 | -5.2786% | 10.6763% | 26.485% | -6.1707% | no | 1.624% | 10 / 59 |
| 2025-04-01 → 2025-07-01 | -4.5069% | 7.4549% | 22.2281% | 13.5401% | yes | 1.4914% | 7 / 61 |
| 2025-07-01 → 2025-10-01 | -5.7366% | 9.9677% | 26.5626% | 5.157% | yes | 1.5624% | 0 / 63 |
| 2025-10-01 → 2026-01-01 | -8.3993% | 10.5957% | 31.3362% | 5.5556% | yes | 1.7674% | 5 / 63 |
| 2026-01-01 | no segment follows this rebalance, not scored | ||||||