
The Frog in the Pan Says Keep the Steady Climbers. In the S&P 500, It Works the Other Way Around
Momentum investors buy last year's winners. A well-known refinement, the frog in the pan of Da, Gurun and Warachka (2014), also looks at how a winner went up. A stock that climbed a little on most days is said to be a better buy than one that rose in a few big jumps, because news that arrives slowly is noticed late and keeps pushing the price. Alpha Architect's momentum method is built on it.
We tested it in the S&P 500 every quarter from 2006 to 2025. Last year's top 10% performers were split in two by how they rose, the steady climbers and the big jumpers, and each half was held until the next quarter. All of last year's winners together ran beside them, and SPY was the benchmark.
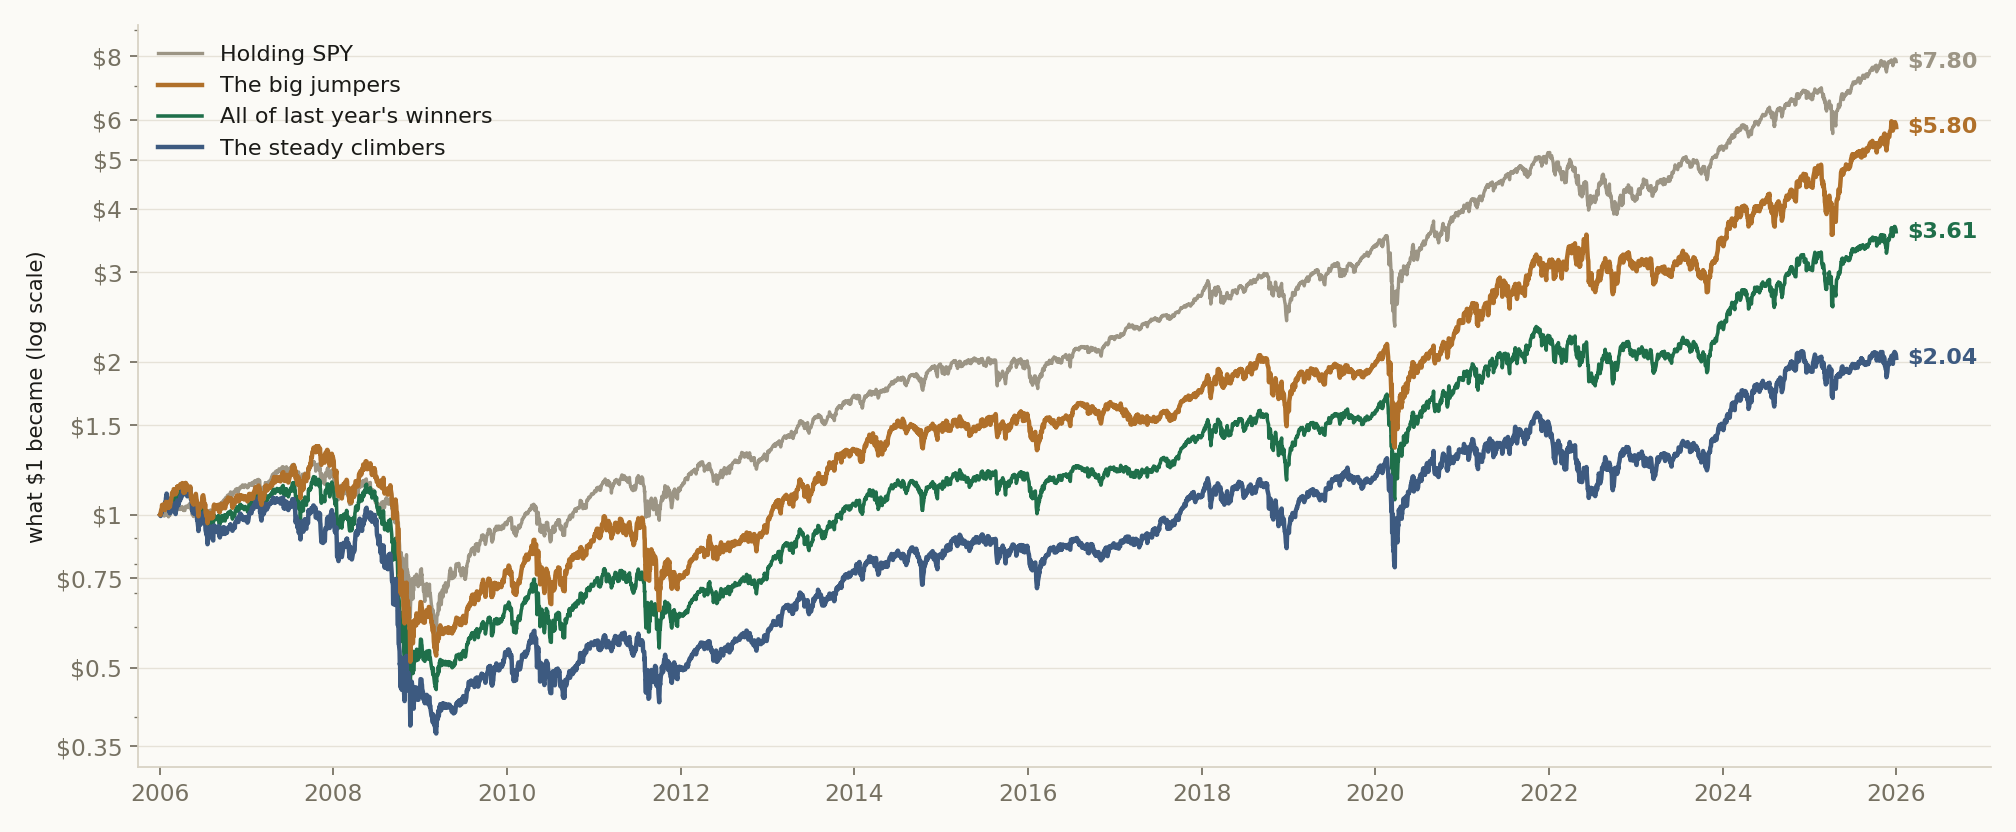
The rule ran backwards. The big jumpers beat the steady climbers in all but five of the twenty years and ended with nearly three times as much money, with or without dividends. None of the three beat simply holding SPY. All three fell about half in the 2008 crash, much further than the index, and never made the ground back. Our price data misses about a third of the index's members in 2006, the companies that later left it, and which half they would have joined is unknown.
Why this one
A momentum investor owns last year's winners. Some add a second question, about how the winner won. The idea comes from a well-known study by Da, Gurun and Warachka, nicknamed the frog in the pan after the frog that does not notice the water warming. News that arrives a little at a time is noticed late, so a steady climb keeps going. A big jump is news everyone saw, so it is priced at once.
Investors act on this with real money. Alpha Architect's momentum method takes the strongest stocks and then keeps the half that climbed most steadily. The rule was found across the whole US market, small companies included. This paper checks whether it holds in the large companies most people own, after costs, year by year, from 2006 to 2025.
How the split works
Every quarter, the S&P 500's members on that day are ranked by how much they rose over the past year, leaving out the latest month, the usual momentum measure. The top 10% are last year's winners. Holding all of them is plain momentum.
Then each winner gets a smoothness reading from its daily closes over the same year: the share of days it went up minus the share of days it went down. A stock that rose a little on most days reads high. One that made its gain on a few big days, and went down almost as often as up, reads low. The higher half of the winners are the steady climbers, the lower half the big jumpers: two groups of the same size from the same winners, never overlapping. Each group is bought in equal amounts and held until the next quarter, when everything is chosen again.
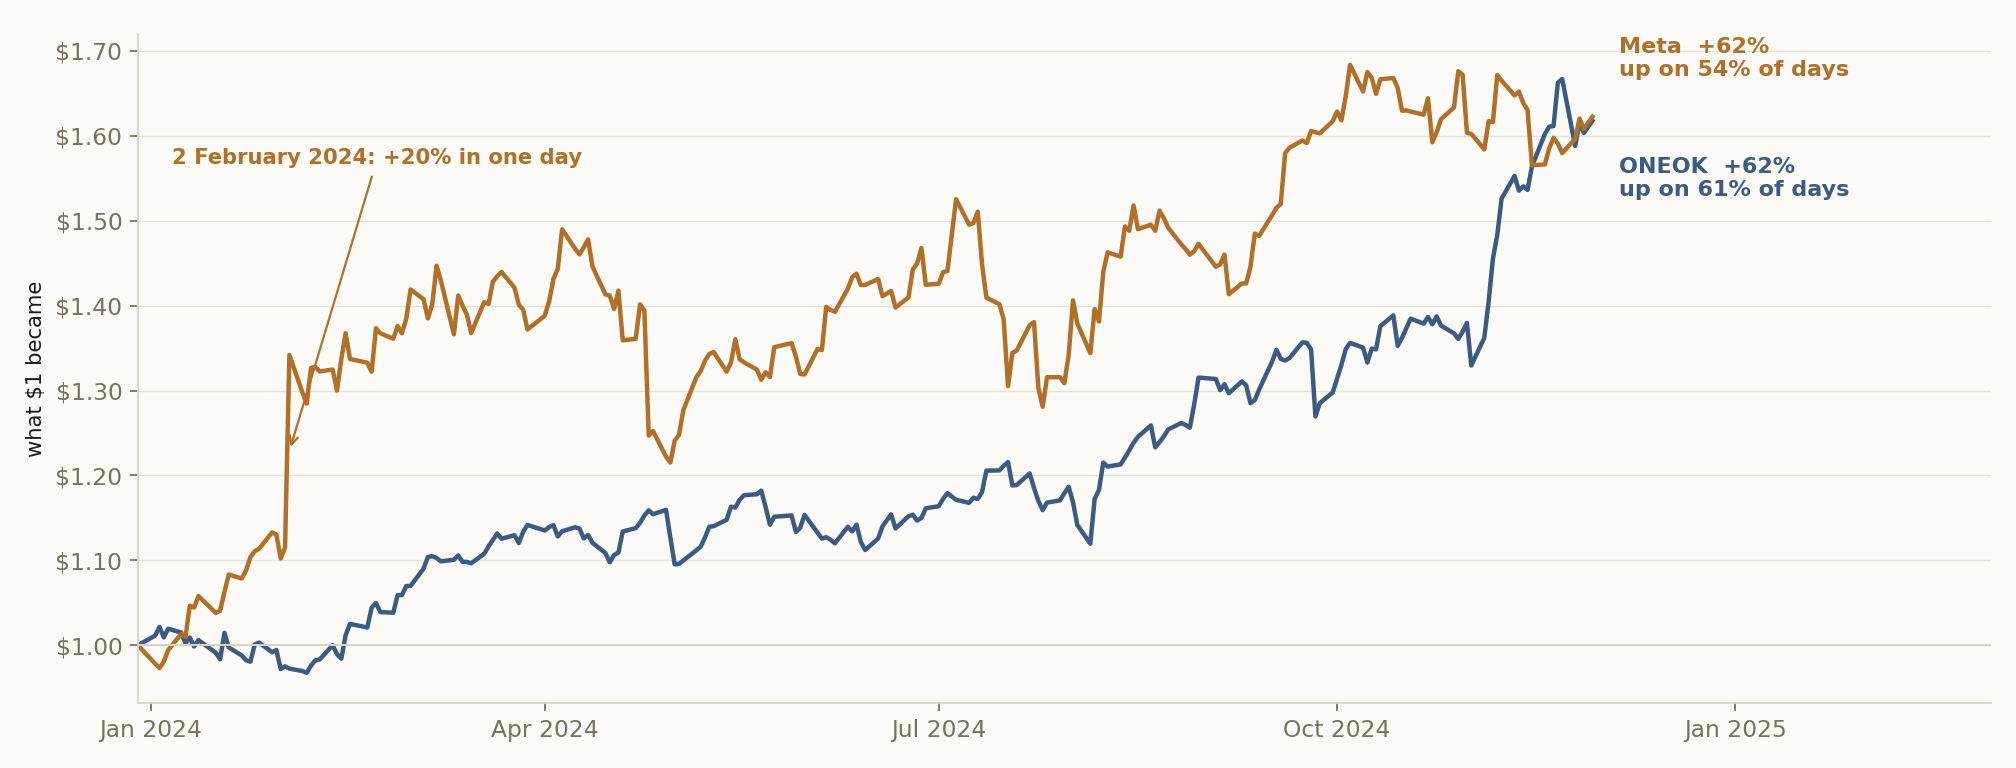
The chart below shows two of last year's winners at the start of 2025. ONEOK and Meta both rose 62% over the year the rule reads. ONEOK went up on three days in five and never gained 5% in a single day: a steady climber. Meta went up on just over half its days, and one day in February 2024, after its earnings, added a fifth to its price: a big jumper. The frog in the pan keeps ONEOK and drops Meta.
1 Methodology, in detail (click to open)
1 Methodology
Universe. The S&P 500 as its members stood on each re-selection day, every member with a price history in our data.
Last year's winners. Each member's gain over the past year leaving out the latest month (12-1 momentum, Jegadeesh and Titman 1993), read from the closes up to the re-selection day. The top 10% of the members by that gain: about 35 stocks in 2006 and 50 from 2020, as the price data fills in.
The split. For each winner, the share of trading days in the same window it went up minus the share it went down, from -1 to 1: the sign-adjusted reverse of the information discreteness of Da, Gurun and Warachka (2014), so a high reading is a steady climb. The winners are ordered by it; the higher half are the steady climbers and the lower half the big jumpers, each the floor of half the winners, so an odd count leaves its middle name out of both. On the platform's Smooth Climb Pick these are Keep: the steadier half and Keep: the jumpier half.
The portfolios. Each group is bought at equal weight at the next close after the re-selection day and held to the next quarterly re-selection. Returns include dividends, SPY's too. Every trade pays 0.1% of its value.
The walk. Twenty one-year windows from the first trading day of 2006 to the end of 2025, every setting fixed before the first window ran. Two comparisons, both reported: the steady climbers against all of last year's winners, and the big jumpers against all of them; all of them is the same portfolio in both. The steady climbers' own walk is the second test in Every test, in numbers, further down. A first walk of the same two comparisons started in 2010; its sixteen years are the last sixteen here, unchanged.
One continuous path. Each yearly test starts in cash and buys at the close of its first trading day, so the tests joined end to end would miss the first trading day of every year, for all four lines. Our figures and tables carry each portfolio through that day with the stocks it held at the close before, and SPY with its own closes, so SPY matches its own record. The race starts at the close of 3 January 2006, when the first portfolios were bought, so SPY's 2006 runs from that close too and sits a little below its calendar-year return. The platform's yearly records further down leave the first trading days out. On that basis the big jumpers also led in 2024, by under a point, and every other year comes out the same.
Without dividends. Table 3's second column takes the dividends out of each portfolio's daily path from the same walk and keeps the trading costs; SPY is its price alone.
2 Results
2.1 Headline
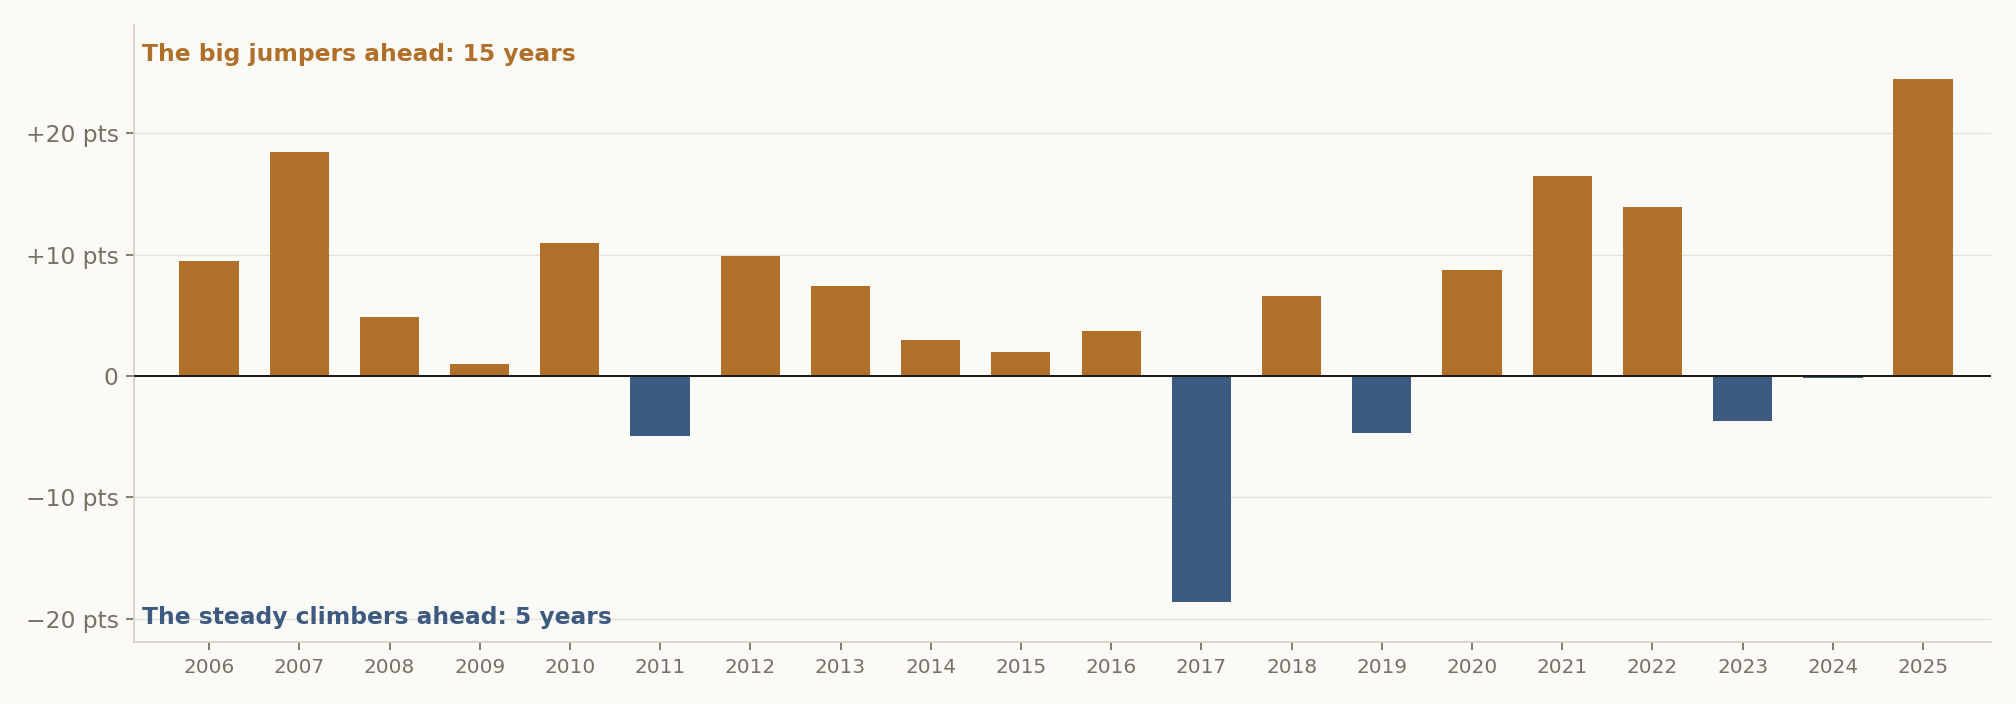
Table 1. Each year's return, 2006 to 2015: last year's top 10% of the S&P 500 split every quarter into the big jumpers and the steady climbers, all of last year's winners together, and holding SPY. Dividends included for all four; the three portfolios pay 0.1% on every trade.
| Year | Big jumpers | Steady climbers | All winners | Holding SPY |
|---|---|---|---|---|
| 2006 | +7.8% | −1.7% | +3.0% | +13.8% |
| 2007 | +20.1% | +1.6% | +10.3% | +5.1% |
| 2008 | −50.0% | −54.9% | −52.2% | −36.8% |
| 2009 | +18.5% | +17.5% | +20.1% | +26.4% |
| 2010 | +15.5% | +4.5% | +10.8% | +15.1% |
| 2011 | −15.3% | −10.4% | −12.8% | +1.9% |
| 2012 | +25.9% | +16.0% | +20.7% | +16.0% |
| 2013 | +42.2% | +34.8% | +38.0% | +32.3% |
| 2014 | +9.5% | +6.5% | +7.6% | +13.5% |
| 2015 | +5.5% | +3.5% | +4.9% | +1.3% |
Table 2. The same for 2016 to 2025.
| Year | Big jumpers | Steady climbers | All winners | Holding SPY |
|---|---|---|---|---|
| 2016 | +4.5% | +0.8% | +2.8% | +12.0% |
| 2017 | +7.1% | +25.7% | +16.1% | +21.7% |
| 2018 | −7.7% | −14.3% | −11.0% | −4.6% |
| 2019 | +22.9% | +27.6% | +25.7% | +31.2% |
| 2020 | +22.2% | +13.5% | +17.4% | +18.4% |
| 2021 | +28.8% | +12.3% | +20.5% | +28.7% |
| 2022 | −0.6% | −14.5% | −7.4% | −18.2% |
| 2023 | +12.9% | +16.6% | +14.9% | +26.2% |
| 2024 | +27.2% | +27.4% | +27.6% | +24.9% |
| 2025 | +30.6% | +6.1% | +18.6% | +17.7% |
Table 3. What $1 became from 2006 to 2025, with dividends and without them; the three portfolios pay their trading costs either way. Every line is lower without dividends, and the order and the counts of years stay the same.
| For each $1 | With dividends | Without dividends |
|---|---|---|
| Holding SPY | $7.80 10.8% a year | $5.38 8.8% a year |
| Big jumpers | $5.80 9.2% a year | $4.41 7.7% a year |
| All winners | $3.61 6.6% a year | $2.79 5.3% a year |
| Steady climbers | $2.04 3.6% a year | $1.60 2.4% a year |
| Big jumpers ahead of steady | 15 of 20 years | 15 of 20 years |
| Big jumpers ahead of SPY | 10 of 20 years | 10 of 20 years |
Table 4. Growth a year, the worst fall from a high, and the typical size of a year's ups and downs (the standard deviation of daily returns, scaled to a year), all with dividends, on the continuous daily path. The big jumpers swung about as much as the steady climbers and fell less at their worst.
| 2006 to 2025 | Growth a year | Worst fall | Yearly swing |
|---|---|---|---|
| Holding SPY | 10.8% | −55% | 19% |
| Big jumpers | 9.2% | −62% | 25% |
| All winners | 6.6% | −62% | 24% |
| Steady climbers | 3.6% | −67% | 25% |
Sections 2.2 to 4, the full record: every year, every test, and how each one was run (click to open)
The registration names the two groups compared The jumpier half and All of last year's top 10%; this paper calls them The big jumpers and All of last year's winners.
2.2 Per-step results
| # | Out-of-sample window | The big jumpers SR | All of last year's winners SR |
|---|---|---|---|
| 1 | 2006-01-03 → 2006-12-29 | 0.51 | 0.26 |
| 2 | 2007-01-03 → 2007-12-31 | 0.99 | 0.59 |
| 3 | 2008-01-02 → 2008-12-31 | -1.26 | -1.24 |
| 4 | 2009-01-02 → 2009-12-31 | 0.69 | 0.76 |
| 5 | 2010-01-04 → 2010-12-31 | 0.58 | 0.43 |
| 6 | 2011-01-03 → 2011-12-30 | -0.39 | -0.34 |
| 7 | 2012-01-03 → 2012-12-31 | 1.45 | 1.32 |
| 8 | 2013-01-02 → 2013-12-31 | 1.94 | 1.92 |
| 9 | 2014-01-02 → 2014-12-31 | 0.63 | 0.55 |
| 10 | 2015-01-02 → 2015-12-31 | 0.39 | 0.36 |
| 11 | 2016-01-04 → 2016-12-30 | 0.47 | 0.39 |
| 12 | 2017-01-03 → 2017-12-29 | 0.53 | 1.20 |
| 13 | 2018-01-02 → 2018-12-31 | -0.32 | -0.46 |
| 14 | 2019-01-02 → 2019-12-31 | 1.49 | 1.81 |
| 15 | 2020-01-02 → 2020-12-31 | 0.69 | 0.58 |
| 16 | 2021-01-04 → 2021-12-31 | 1.15 | 0.97 |
| 17 | 2022-01-03 → 2022-12-30 | 0.04 | -0.18 |
| 18 | 2023-01-03 → 2023-12-29 | 0.91 | 1.08 |
| 19 | 2024-01-02 → 2024-12-31 | 1.39 | 1.48 |
| 20 | 2025-01-02 → 2025-12-31 | 1.11 | 0.83 |
2.2b Every test, in numbers
Every test this paper registered, two rows each, the paper’s own test first.
| Walk | Windows | Span | Growth | CAGR | Worst drawdown | Pooled Sharpe |
|---|---|---|---|---|---|---|
| jumpier · The jumpier half (this paper, the one the platform opens) | 20 | 2006-01-03 → 2025-12-31 | +436.3% | +8.8% | -62.2% | 0.47 |
| jumpier · All of last year's top 10% (this paper, the one the platform opens) | 20 | 2006-01-03 → 2025-12-31 | +245.4% | +6.4% | -63.0% | 0.38 |
| steadier · The steadier half | 20 | 2006-01-03 → 2025-12-31 | +101.2% | +3.6% | -68.1% | 0.27 |
| steadier · All of last year's top 10% | 20 | 2006-01-03 → 2025-12-31 | +245.4% | +6.4% | -63.0% | 0.38 |
| platform reference (SPY) (benchmark) | 2006-01-03 → 2025-12-31 | +628.8% | +10.4% | -56.1% |
2.3 Search accounting
This paper's search is a declared family: the paper's 2 walks, counted at N = 2 evaluated books. Every member is either a registered walk with its own hypothesis and frozen record, or a derived average computed from those frozen records; every member is reported, in the family table, and none was selected away. The count is declared by the author rather than derived from one project's ledger, because the members are sibling registered studies; the declaration names them and is frozen in this artifact. What the source strategy's author searched before publishing is not knowable from here and is not counted. The registered per-step record below still guarantees each window's hypothesis was hashed and registered before that window was scored.
2.4 The comparison
Both arms trade the same registered windows, so their returns can be PAIRED: inside each window the two return series are inner-joined date by date and the difference rThe big jumpers − rAll of last year's winners is the object under test. Because this is ONE pre-declared contrast, frozen at registration before any window was scored, the paired statistic needs no multiple-testing deflation; the arm-level records carry the declared family count of §2.3 as their search accounting, and this contrast, registered per window before scoring, is not multiplied by it.
In the table: Arm A = The big jumpers · Arm B = All of last year's winners.
| # | Window | Paired bars | Arm A | Arm B | Δ | Leader |
|---|---|---|---|---|---|---|
| 1 | 2006-01-04 → 2006-12-29 | 250 | +7.8% | +3.0% | +4.8 pp | Arm A |
| 2 | 2007-01-04 → 2007-12-31 | 250 | +20.4% | +11.0% | +9.4 pp | Arm A |
| 3 | 2008-01-03 → 2008-12-31 | 252 | -49.3% | -51.4% | +2.2 pp | Arm A |
| 4 | 2009-01-05 → 2009-12-31 | 251 | +14.1% | +14.8% | -0.8 pp | Arm B |
| 5 | 2010-01-05 → 2010-12-31 | 251 | +13.5% | +8.6% | +4.8 pp | Arm A |
| 6 | 2011-01-04 → 2011-12-30 | 251 | -17.1% | -14.2% | -2.9 pp | Arm B |
| 7 | 2012-01-04 → 2012-12-31 | 249 | +24.8% | +20.1% | +4.7 pp | Arm A |
| 8 | 2013-01-03 → 2013-12-31 | 251 | +37.7% | +34.0% | +3.7 pp | Arm A |
| 9 | 2014-01-03 → 2014-12-31 | 251 | +10.1% | +8.3% | +1.9 pp | Arm A |
| 10 | 2015-01-05 → 2015-12-31 | 251 | +5.3% | +4.6% | +0.6 pp | Arm A |
| 11 | 2016-01-05 → 2016-12-30 | 251 | +6.3% | +4.8% | +1.4 pp | Arm A |
| 12 | 2017-01-04 → 2017-12-29 | 250 | +6.1% | +15.0% | -9.0 pp | Arm B |
| 13 | 2018-01-03 → 2018-12-31 | 250 | -8.9% | -11.9% | +3.0 pp | Arm A |
| 14 | 2019-01-03 → 2019-12-31 | 251 | +23.2% | +26.2% | -3.0 pp | Arm B |
| 15 | 2020-01-03 → 2020-12-31 | 252 | +20.6% | +16.0% | +4.6 pp | Arm A |
| 16 | 2021-01-05 → 2021-12-31 | 251 | +30.1% | +21.8% | +8.3 pp | Arm A |
| 17 | 2022-01-04 → 2022-12-30 | 250 | -2.7% | -7.7% | +5.0 pp | Arm A |
| 18 | 2023-01-04 → 2023-12-29 | 249 | +15.6% | +17.9% | -2.3 pp | Arm B |
| 19 | 2024-01-03 → 2024-12-31 | 251 | +31.0% | +30.8% | +0.1 pp | Arm A |
| 20 | 2025-01-03 → 2025-12-31 | 249 | +30.3% | +18.0% | +12.2 pp | Arm A |
Paired Sharpe of the difference track: 0.43 · block bootstrap (2000 paths, block 10, seed 1234): P(The big jumpers beats All of last year's winners) = 97.5%.
Window win-rate. The big jumpers led 15 of 20 windows (75.0%), All of last year's winners led 5, and the mean window gap of +2.44 pp points the same way. Widest single window: 2025 at +12.2 pp.
3 The circuit
The strategy is a circuit of platform primitives, frozen when the study is registered. Below is the circuit as wired on the canvas, the objective it encodes and how the search runs through it, followed by the mathematics each primitive actually computes, the same formulas the execution engine runs. The complete parameterisation is preserved in the study ledger (Appendix A).
The sentence below is the registration record, generated when the circuit was registered and printed verbatim; the authored description of the design is Section 1.
A COMPARATIVE study: The jumpier half vs All of last year's top 10%, walked on the same registered out-of-sample windows. The jumpier half: S&P 500, the jumpier half of last year's top 10% performers by Momentum (12-1), rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. All of last year's top 10%: S&P 500, all of last year's top 10% performers by Momentum (12-1), rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. The arms differ in: Smooth Climb Pick, Keep: The jumpier half → All of them. The contrast under test: whether The jumpier half generates better risk-adjusted returns than All of last year's top 10% over the identical out-of-sample windows.
Every block in this study is a card from the platform's catalog: the S&P 500 as its members stood at each date, the Price Loader, Momentum 12-1, the Smooth Climb Pick (Pool: last year's top 10% performers; Keep: all of them, the steadier half or the jumpier half), the Transaction Cost card and the Portfolio Forward Test, which chooses again every quarter. A reader can rebuild every test and change any setting.
Envelopes show counts, ratios, dates, and the parameters the author chose. Full price and per-name data series are not republished: the underlying market data is licensed to QuanterLab. Point figures quoted in the prose, a named holding's return over a stated span, are summary facts derived from public market prices, not redistributed series.
The objective and the search
The jumpier half
| Universe | S&P 500 index constituents. |
|---|---|
| Selection | metric across Momentum (12-1). |
| Validation & out-of-sample | portfolio forward test (holds the weights it is given, re-set at each rebalance) (1y horizon from the anchor, quarterly rebalance, each decision traded at the next day's close, dividends counted); overlays: Transaction Cost. |
| Other components | Select: Smooth Climb Pick. |
All of last year's top 10%
The specification is identical to The jumpier half's table above, row for row; the one registered difference between the arms is itemized below.
What differs between the arms, one difference; the comparison is clean:
- paramSmooth Climb Pick, Keep: The jumpier half → All of them
Everything else is held identical, so an out-of-sample gap between the arms is attributable to this one change.
Cost elements are wired into the circuit, the realised drag is reported per step in Appendix B.
Show the mathematics, 6 primitives, formulas and parity notes
3.1 Universe
The starting set of tickers, resolved point-in-time from the index change-log, so names delisted or removed later still compete on the dates they traded.
Before any math, you need a list of stocks. An index preset (S&P 500, Nasdaq-100, Dow 30) is reconstructed as it stood ON your anchor date by replaying the historical add/drop change-log backwards, so a 2018 backtest sees the 2018 membership, not today's winners.
Start from today's constituents and un-apply every membership change after the anchor t:
\mathcal{U}(t) = \mathcal{U}_{\text{now}} \;\ominus\; \{\text{adds after } t\} \;\oplus\; \{\text{drops after } t\}3.2 Price Loader
Bulk OHLCV fetch for the whole universe, point-in-time, no future bars.
Momentum, volatility, trend, every price-based metric needs history. This loads open/high/low/close/volume for all names in parallel, clipped so nothing after the anchor can leak in. The lookback window is derived automatically from the deepest metric you wired.
It loads exactly enough history for the hungriest downstream metric plus a warm-up buffer:
W = \max_k(\text{lookback}_k) + \text{buffer}, \qquad \text{bars} \le \text{anchor } t3.3 Filter Mom 12 1
Classic 12–1 momentum, last year's return, skipping the most recent month.
The workhorse of cross-sectional momentum. Measure the return from 12 months ago to 1 month ago; the 1-month skip avoids the well-known short-term reversal effect that would otherwise contaminate the signal.
m_{12\text{–}1} = \frac{P_{t-21}}{P_{t-252}} - 13.4 Smooth Climb Pick
Smooth Climb Pick: last year's winners, split by how they won.
Two stocks can both be up 40% on the year. One rose a little on most days; the other sat still and then jumped on a handful of days. Pool sets which winners are looked at (last year's top performers by 12-1 momentum); Keep holds all of them, the steadier half or the jumpier half, two equal halves that never overlap. Da, Gurun and Warachka (2014) found that smooth climbers keep climbing longer, because investors are slow to notice news that arrives a little at a time.
\text{smooth} = \operatorname{sign}(R_{12-1})\,\big(\%\text{ up days} - \%\text{ down days}\big) \in [-1,\,1]3.5 Portfolio Backtest
Replay the portfolio forward, rebalanced, point-in-time, with costs.
Holds the basket and rebalances on schedule, re-selecting and re-optimizing point-in-time at each rebalance (so it only ever uses information available then), and reports the equity curve, Sharpe, drawdown and trade stats, optionally net of cost and risk overlays.
E_t = E_{t-1}\big(1 + \mathbf w_{t}^{\top}\mathbf r_t - \text{costs}_t\big)\text{DD}_t = \frac{E_t}{\max_{\tau\le t}E_\tau} - 1, \qquad \text{MaxDD} = \min_t \text{DD}_t\text{charge}_t \;=\; \text{loan}_t \cdot \frac{\text{spread}}{252}, \qquad \text{loan}_t = \begin{cases}\max(0,\,-\text{cash}_t) & \text{institutional (netted)}\\ \max(0,\,\text{long MV}_t - E_t) & \text{retail (no netting)}\end{cases}3.6 Transaction Cost
Charge for trading, slippage + commission on every turn.
Real trading isn't free. This deducts a cost proportional to how much you trade (turnover), in basis points, so the backtest reflects net, not gross, performance.
\text{cost}_t = \frac{\text{bps}}{10{,}000}\;\times\;\text{turnover}_t, \qquad \text{turnover}_t = \tfrac12\sum_i \lvert w_{i,t}-w_{i,t^-}\rvert4 Projection calibration, pooled across the walk
Every rebalance carried a Monte Carlo cone and a 95% VaR estimated before the segment it is scored against. Two questions, pooled over the whole study: did realized outcomes land inside the band as often as the band claims, and were VaR breaches as frequent as 5%?
This section is produced by the forward tester itself: every portfolio backtest fits the cone and the VaR estimate at each rebalance and scores them against the segment that followed. It does not require, and this circuit does not contain, a Monte Carlo primitive; that primitive is a separate, standalone analysis.
| Arm | Steps | Rebalances | In band | Coverage | Expected | VaR days | Breach rate | Expected |
|---|---|---|---|---|---|---|---|---|
| The big jumpers | 20 | 95 | 71 / 80 | 88.8% ±3.53 | 90.0% | 4951 | 6.12% ±0.341 | 5.0% |
| All of last year's winners | 20 | 95 | 68 / 80 | 85.0% ±3.99 | 90.0% | 4951 | 6.58% ±0.352 | 5.0% |
± values are binomial standard errors on the estimate. A coverage figure below the expected band means the projection was over-confident; a breach rate above 5% means the same of the risk model. Both forecasts used only data prior to the segment scored.
5 Discussion
5.1 Findings
The year-by-year chart shows the result. Each bar is the big jumpers' return minus the steady climbers' in one year, and the bars sit above the line in all but five of the twenty years. The steady climbers were ahead only in 2011, 2017, 2019, 2023 and, by a fifth of a point, 2024.
Over the twenty years $1 in the big jumpers became $5.80, in all of last year's winners $3.61, and in the steady climbers $2.04 (the growth chart, Tables 1 and 2). Keeping the steady climbers, as the rule says, cost money against plain momentum, and keeping the big jumpers added it. The big jumpers also trade more than the whole group, so costs work against them, and they still came out ahead.
Holding SPY made $7.80 and beat all three. The gap opened in 2008 and 2009. The three portfolios fell about half in 2008, much further than the index, and rose less in the 2009 rebound. After the crash the big jumpers grew almost as fast as SPY but never caught up.
Dividends change nothing here. Without them every line is lower, and the order and the count of years stay the same (Table 3).
5.2 Interpretation
This paper does not test why the rule ran backwards in the S&P 500. Two explanations fit the result. The frog in the pan rests on slow news being noticed late, and the largest companies are followed by dozens of analysts and every news desk, so little slow news is left to notice late. And a big jump in a large company often comes from news that changes the business, an earnings surprise or a new product, and research on earnings has long found that prices keep drifting the same way for weeks after such news.
The obvious objection is risk: a portfolio of jumpy stocks should swing more. It did not. Day to day the big jumpers moved about as much as the steady climbers, and their worst fall was smaller (Table 4). The falling years agree. Momentum lost money in 2008, 2011, 2018 and 2022, and the big jumpers lost less than the steady climbers in three of the four, 2008 included.
The crash years repeat an old pattern. At the start of 2008 last year's winners included National Oilwell Varco, Transocean, Freeport-McMoRan and Deere, riding the commodity boom, and they fell further than the index when the boom broke. At the start of 2009 they included Walmart, General Mills, Amgen and Southern Company, the stocks that had fallen least, and when the market turned they rose least. Daniel and Moskowitz (2016) call this a momentum crash. It hit all three portfolios alike, and none of them made the ground back.
A plain rule reads one thing about a stock and applies it in every kind of market; nothing in it could tell 2008 from the years around it. Our earlier test of a VIX circuit breaker on momentum stepped aside in 2008 and then missed every recovery that followed.
Part of the lead in 2025 may come from the AI build-out, which arrived as earnings jumps; a rule that waits for a steady climb is built to miss moves like that.
The original study measured the whole market, small companies included, over earlier decades, and Alpha Architect draws from a wider pool than the S&P 500.
Enter the lab
Both comparisons are circuits on the platform, built from catalog cards: the S&P 500 as its members stood at each date, the Price Loader, Momentum 12-1, the Smooth Climb Pick and the Portfolio Forward Test. The Smooth Climb Pick's two settings are the whole rule. Pool: last year's top 10% performers. Keep: all of them, the steadier half or the jumpier half. Open one, widen the pool to the top 20% or keep the other half, and run your own test. Add a VIX Regime card, which labels each day calm, choppy or stressed, to see which kind of market each year was, or a Regime Filter to try a switch of your own.
5.3 Limitations
Our price data does not hold the companies that later left the S&P 500, so a winner that collapsed and was removed is missing from the quarters it would have been held. The gap is widest in the early years: in 2006 about a third of the index's members have no price in our data, and from 2020 nearly all of them do, so the pool of winners grew from about 35 stocks to 50. Which half a missing company would have joined, this data cannot say. The missing companies most likely flatter all three momentum portfolios against SPY, whose record is complete, so the SPY result stands; only the order between the two halves is at risk. Each half holds 16 to 25 stocks, so single names move it more than a broad portfolio. Every trade pays 0.1% of its value; choosing again every quarter trades a lot, and a higher cost would lower all three. The smoothness reading uses one window, the same year as the momentum measure, fixed before the walk; no other window was tried.
Computed, not featured
The run produced the results below. The author chose not to feature them in this paper; they were computed all the same, are part of the frozen record, and are reproducible from the study's frozen circuit.
- The measurement ladder, 20 windows. The forward tester, per window: the same walk chained price-only, with dividends and net of costs, against the benchmark measured both ways.
References
- Gelman, A., & Loken, E. (2013). The garden of forking paths: Why multiple comparisons can be a problem, even when there is no “fishing expedition.” Working paper, Columbia University.
- Harvey, C. R., Liu, Y., & Zhu, H. (2016). … and the Cross-Section of Expected Returns. Review of Financial Studies, 29(1), 5–68. doi:10.1093/rfs/hhv059
- Lo, A. W. (2002). The Statistics of Sharpe Ratios. Financial Analysts Journal, 58(4), 36–52. doi:10.2469/faj.v58.n4.2453
- Da, Gurun and Warachka (2014), Frog in the Pan: Continuous Information and Momentum, Review of Financial Studies 27(7): 2171-2218. Winners whose gains came from many small moves kept winning longer. https://doi.org/10.1093/rfs/hhu003
- Jegadeesh and Titman (1993), Returns to Buying Winners and Selling Losers: Implications for Stock Market Efficiency, Journal of Finance 48(1): 65-91. The momentum measure used to find last year's winners. https://doi.org/10.1111/j.1540-6261.1993.tb04702.x
- Gray and Vogel (2016), Quantitative Momentum: A Practitioner's Guide to Building a Momentum-Based Stock Selection System, Wiley. The strongest stocks first, then the steadier half.
- Daniel and Moskowitz (2016), Momentum Crashes, Journal of Financial Economics 122(2): 221-247. After a market falls, last year's winners lag the rebound. https://doi.org/10.1016/j.jfineco.2015.12.002
- Bernard and Thomas (1989), Post-Earnings-Announcement Drift: Delayed Price Response or Risk Premium?, Journal of Accounting Research 27: 1-36. Prices keep drifting the same way after earnings news. https://doi.org/10.2307/2491062
Appendix A Reproducibility in QuanterLab
Each step is backed by a frozen run report. The study is re-derivable from the ledger below.
| # | Commit | Report | Anchor | OOS window |
|---|---|---|---|---|
| 1 | 1abcef2993f2 | 14435 | 2006-01-01 | 2006-01-03 → 2006-12-29 |
| 2 | e8ae2eb8a23a | 14438 | 2007-01-01 | 2007-01-03 → 2007-12-31 |
| 3 | 43044ff5bdae | 14439 | 2008-01-01 | 2008-01-02 → 2008-12-31 |
| 4 | ef1bd799f0f1 | 14441 | 2009-01-01 | 2009-01-02 → 2009-12-31 |
| 5 | 62ec3351b0d2 | 14443 | 2010-01-01 | 2010-01-04 → 2010-12-31 |
| 6 | 83a7d8f72bd0 | 14445 | 2011-01-01 | 2011-01-03 → 2011-12-30 |
| 7 | 40d444665925 | 14447 | 2012-01-01 | 2012-01-03 → 2012-12-31 |
| 8 | 23569d00f6d8 | 14449 | 2013-01-01 | 2013-01-02 → 2013-12-31 |
| 9 | 53d5dcefc992 | 14451 | 2014-01-01 | 2014-01-02 → 2014-12-31 |
| 10 | 866ef0f24aff | 14453 | 2015-01-01 | 2015-01-02 → 2015-12-31 |
| 11 | c65025741a7b | 14455 | 2016-01-01 | 2016-01-04 → 2016-12-30 |
| 12 | 80d140ec7d0e | 14458 | 2017-01-01 | 2017-01-03 → 2017-12-29 |
| 13 | 808aa34a1c10 | 14460 | 2018-01-01 | 2018-01-02 → 2018-12-31 |
| 14 | c4d320e457e7 | 14462 | 2019-01-01 | 2019-01-02 → 2019-12-31 |
| 15 | 1019b844e7a7 | 14463 | 2020-01-01 | 2020-01-02 → 2020-12-31 |
| 16 | 6425ed2169b1 | 14465 | 2021-01-01 | 2021-01-04 → 2021-12-31 |
| 17 | 46e279f074d3 | 14468 | 2022-01-01 | 2022-01-03 → 2022-12-30 |
| 18 | 3ec5de95b1f9 | 14469 | 2023-01-01 | 2023-01-03 → 2023-12-29 |
| 19 | c065d04dac10 | 14471 | 2024-01-01 | 2024-01-02 → 2024-12-31 |
| 20 | 9769133dc2d1 | 14473 | 2025-01-01 | 2025-01-02 → 2025-12-31 |
Appendix A2 Registration record
What this record does and does not establish. Every window in this study is historical: the data existed before the study began, so this is sequential registration on past windows, not pre-registration in the clinical-trial sense, and no procedure could make it so. What the platform does enforce is order, each step's specification was frozen and hashed before that step was scored, and the walk cannot advance past a step that was never run or close one with a result registered for a different window. The two timestamp columns below are the evidence: read them together and each registration precedes its own run, and each run precedes the next registration. A study whose registrations all post-date its runs would show it here. Wall-clock spacing between registrations varies with the author's schedule and queue latency; the ordering, not the tempo, is the claim.
“A COMPARATIVE study: The jumpier half vs All of last year's top 10%, walked on the same registered out-of-sample windows. The jumpier half: S&P 500, the jumpier half of last year's top 10% performers by Momentum (12-1), rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. All of last year's top 10%: S&P 500, all of last year's top 10% performers by Momentum (12-1), rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. The arms differ in: Smooth Climb Pick, Keep: The jumpier half → All of them. The contrast under test: whether The jumpier half generates better risk-adjusted returns than All of last year's top 10% over the identical out-of-sample windows.”
The same hypothesis was registered independently at every step, hashed before each step's out-of-sample window was scored:
| # | Anchor | Registered at (UTC) | Run completed (UTC) |
|---|---|---|---|
| 1 | 2006-01-01 | 2026-10-07 11:58:27 | 2026-10-07 12:03:15 |
| 2 | 2007-01-01 | 2026-10-07 12:03:15 | 2026-10-07 12:07:10 |
| 3 | 2008-01-01 | 2026-10-07 12:07:10 | 2026-10-07 12:09:31 |
| 4 | 2009-01-01 | 2026-10-07 12:09:31 | 2026-10-07 12:12:39 |
| 5 | 2010-01-01 | 2026-10-07 12:12:39 | 2026-10-07 12:14:03 |
| 6 | 2011-01-01 | 2026-10-07 12:14:03 | 2026-10-07 12:15:27 |
| 7 | 2012-01-01 | 2026-10-07 12:15:27 | 2026-10-07 12:16:39 |
| 8 | 2013-01-01 | 2026-10-07 12:16:39 | 2026-10-07 12:18:08 |
| 9 | 2014-01-01 | 2026-10-07 12:18:08 | 2026-10-07 12:19:35 |
| 10 | 2015-01-01 | 2026-10-07 12:19:35 | 2026-10-07 12:21:03 |
| 11 | 2016-01-01 | 2026-10-07 12:21:03 | 2026-10-07 12:22:26 |
| 12 | 2017-01-01 | 2026-10-07 12:22:27 | 2026-10-07 12:24:03 |
| 13 | 2018-01-01 | 2026-10-07 12:24:03 | 2026-10-07 12:25:44 |
| 14 | 2019-01-01 | 2026-10-07 12:25:44 | 2026-10-07 12:27:24 |
| 15 | 2020-01-01 | 2026-10-07 12:27:24 | 2026-10-07 12:28:49 |
| 16 | 2021-01-01 | 2026-10-07 12:28:49 | 2026-10-07 12:30:30 |
| 17 | 2022-01-01 | 2026-10-07 12:30:30 | 2026-10-07 12:32:12 |
| 18 | 2023-01-01 | 2026-10-07 12:32:12 | 2026-10-07 12:33:54 |
| 19 | 2024-01-01 | 2026-10-07 12:33:54 | 2026-10-07 12:35:22 |
| 20 | 2025-01-01 | 2026-10-07 12:35:23 | 2026-10-07 12:37:09 |
Appendix B Per-step diagnostics
Realized in the projection tables below is the risk engine scoring its own forecast: the buy-and-hold return of the segment that followed each rebalance, on the same gross basis the cone was projected on. It is deliberately not the charged, calendar-window total return the study’s tables print, so the two will not reconcile line by line; the cone and its outcome share one basis, which is what a calibration test requires. Each row names its segment’s span so a boundary session is visible.
Names held is the union across the window: the count of distinct instruments the book touched between the window’s first and last session, not the number it held at one time. A book that rotates monthly touches more names than it holds.
What each step's run actually did beyond its return: capital allocation across lanes and regimes, the portfolio book's rebalancing and cost drag, and how positions were sized. Harvested from the frozen run reports, present where the circuit produced them. Cost drag is the gap between the step's return before and after its trading costs, in percentage points of the step's starting capital, so on a book that trades every session and compounds it can exceed the step's own net return.
Open the full per-step grid (20 steps: every rebalance, capital routing and sizing, per window)
Step 1 · 2006-01-03 → 2006-12-29
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 46 names held · selection: reselect · 0.4% in cash · turnover 5.3× · cost drag 0.53% · 1 name dropped at load (47 selected, 46 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.88% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2006-01-01 → 2006-04-01 | -4.3328% | 8.1838% | 23.7225% | 11.3174% | yes | 1.4367% | 1 / 61 |
| 2006-04-01 → 2006-07-01 | -7.5431% | 6.6858% | 23.207% | -4.888% | yes | 1.7287% | 8 / 62 |
| 2006-07-01 → 2006-10-01 | -8.4335% | 7.5019% | 26.3282% | -3.8227% | yes | 1.9391% | 5 / 62 |
| 2006-10-01 → 2007-01-01 | -6.4259% | 6.5811% | 21.4879% | 4.0042% | yes | 1.4684% | 3 / 62 |
| 2007-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 81 names held · selection: reselect · 0.4% in cash · turnover 4.2× · cost drag 0.42% · 1 name dropped at load (82 selected, 81 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.88% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2006-01-01 → 2006-04-01 | -2.4028% | 10.3894% | 26.2737% | 10.2395% | yes | 1.5788% | 2 / 61 |
| 2006-04-01 → 2006-07-01 | -5.8455% | 8.6412% | 25.4613% | -6.2511% | no | 1.7292% | 7 / 62 |
| 2006-07-01 → 2006-10-01 | -6.7787% | 9.2388% | 28.1265% | -5.3863% | yes | 1.9193% | 5 / 62 |
| 2006-10-01 → 2007-01-01 | -5.3844% | 6.6776% | 20.3613% | 5.3021% | yes | 1.3565% | 3 / 62 |
| 2007-01-01 | no segment follows this rebalance, not scored | ||||||
Step 2 · 2007-01-03 → 2007-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 54 names held · selection: reselect · 0.4% in cash · turnover 6.0× · cost drag 0.6% · 1 name dropped at load (55 selected, 54 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 10.53% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2007-01-01 → 2007-04-01 | -6.2418% | 7.9214% | 22.6356% | 3.3675% | yes | 1.5179% | 4 / 60 |
| 2007-04-01 → 2007-07-01 | -6.1399% | 7.4811% | 23.1759% | 4.0876% | yes | 1.592% | 2 / 62 |
| 2007-07-01 → 2007-10-01 | -4.4983% | 9.1809% | 24.9166% | 5.2325% | yes | 1.5557% | 10 / 62 |
| 2007-10-01 → 2008-01-01 | -5.7854% | 9.9437% | 26.5694% | -0.0049% | yes | 1.7379% | 10 / 63 |
| 2008-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 89 names held · selection: reselect · 0.4% in cash · turnover 4.8× · cost drag 0.48% · 1 name dropped at load (90 selected, 89 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 13.36% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2007-01-01 → 2007-04-01 | -4.9158% | 7.8402% | 20.9071% | 3.8675% | yes | 1.387% | 6 / 60 |
| 2007-04-01 → 2007-07-01 | -4.8273% | 6.8839% | 20.1172% | 1.5725% | yes | 1.3735% | 4 / 62 |
| 2007-07-01 → 2007-10-01 | -3.6176% | 8.8607% | 23.0415% | 0.9058% | yes | 1.3426% | 14 / 62 |
| 2007-10-01 → 2008-01-01 | -5.7885% | 10.8625% | 28.6035% | -2.2777% | yes | 1.8066% | 9 / 63 |
| 2008-01-01 | no segment follows this rebalance, not scored | ||||||
Step 3 · 2008-01-02 → 2008-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 4 constructions · 55 names held · selection: reselect · 0.4% in cash · turnover 4.5× · cost drag 0.45% · 1 name dropped at load (56 selected, 55 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 25.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 21.69% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2008-01-01 → 2008-04-01 | -8.3721% | 8.5829% | 26.6923% | -13.443% | no | 2.0884% | 16 / 60 |
| 2008-04-01 → 2008-07-01 | -11.4766% | 6.1436% | 25.2566% | 1.9273% | yes | 2.1375% | 4 / 63 |
| 2008-07-01 → 2008-10-01 | -12.3361% | 6.8116% | 27.9013% | -22.6271% | no | 2.332% | 13 / 63 |
| 2008-10-01 → window end | -12.195% | 5.0934% | 23.8144% | -26.614% | no | 2.0873% | 21 / 63 |
All of last year's winners
Portfolio book, rebalanced quarterly · 4 constructions · 88 names held · selection: reselect · 0.4% in cash · turnover 3.3× · cost drag 0.33% · 1 name dropped at load (89 selected, 88 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 25.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 20.08% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2008-01-01 → 2008-04-01 | -7.4795% | 9.3301% | 27.2358% | -12.6121% | no | 1.9292% | 13 / 60 |
| 2008-04-01 → 2008-07-01 | -11.6709% | 6.8563% | 27.124% | 5.8426% | yes | 2.2199% | 2 / 63 |
| 2008-07-01 → 2008-10-01 | -12.2673% | 8.5081% | 31.7195% | -28.6003% | no | 2.46% | 13 / 63 |
| 2008-10-01 → window end | -13.438% | 4.7973% | 24.7602% | -25.9865% | no | 2.1809% | 22 / 63 |
Step 4 · 2009-01-02 → 2009-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 62 names held · selection: reselect · 0.4% in cash · turnover 5.5× · cost drag 0.55%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 3.23% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2009-01-01 → 2009-04-01 | -19.6724% | 1.8451% | 26.3534% | -11.6675% | yes | 2.4614% | 8 / 60 |
| 2009-04-01 → 2009-07-01 | -19.4062% | 0.0861% | 24.4494% | 6.8795% | yes | 2.4064% | 0 / 62 |
| 2009-07-01 → 2009-10-01 | -29.8595% | -0.7288% | 36.2757% | 12.249% | yes | 3.5356% | 0 / 63 |
| 2009-10-01 → 2010-01-01 | -28.2134% | 1.9908% | 40.4992% | 10.596% | yes | 3.5549% | 0 / 63 |
| 2010-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 104 names held · selection: reselect · 0.4% in cash · turnover 4.6× · cost drag 0.46%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.82% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2009-01-01 → 2009-04-01 | -20.0628% | 1.0696% | 25.076% | -11.1608% | yes | 2.4082% | 7 / 60 |
| 2009-04-01 → 2009-07-01 | -19.4098% | -0.2189% | 23.6952% | 4.968% | yes | 2.4249% | 0 / 62 |
| 2009-07-01 → 2009-10-01 | -28.6811% | -0.4682% | 34.895% | 10.6221% | yes | 3.6692% | 0 / 63 |
| 2009-10-01 → 2010-01-01 | -29.5653% | 1.078% | 40.5202% | 11.3062% | yes | 3.9042% | 0 / 63 |
| 2010-01-01 | no segment follows this rebalance, not scored | ||||||
Step 5 · 2010-01-04 → 2010-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 56 names held · selection: reselect · 0.4% in cash · turnover 5.1× · cost drag 0.51%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.0% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2010-01-01 → 2010-04-01 | -31.9894% | 1.8737% | 47.0603% | 6.3348% | yes | 4.7801% | 0 / 60 |
| 2010-04-01 → 2010-07-01 | -39.0586% | 1.3258% | 68.9707% | -15.9507% | yes | 6.8248% | 0 / 62 |
| 2010-07-01 → 2010-10-01 | -35.7228% | 2.497% | 56.8751% | 21.2059% | yes | 5.5185% | 0 / 63 |
| 2010-10-01 → 2011-01-01 | -30.9089% | 6.4935% | 58.0188% | 6.3654% | yes | 5.1578% | 0 / 63 |
| 2011-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 94 names held · selection: reselect · 0.4% in cash · turnover 4.1× · cost drag 0.41%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.0% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2010-01-01 → 2010-04-01 | -33.0911% | 1.5499% | 48.3544% | 4.3313% | yes | 5.0782% | 0 / 60 |
| 2010-04-01 → 2010-07-01 | -37.8242% | 1.7967% | 67.144% | -17.2234% | yes | 6.5193% | 0 / 62 |
| 2010-07-01 → 2010-10-01 | -36.5141% | 2.3659% | 58.2695% | 14.2564% | yes | 5.5114% | 0 / 63 |
| 2010-10-01 → 2011-01-01 | -28.2107% | 6.8573% | 53.5909% | 10.0966% | yes | 4.5104% | 0 / 63 |
| 2011-01-01 | no segment follows this rebalance, not scored | ||||||
Step 6 · 2011-01-03 → 2011-12-30
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 52 names held · selection: reselect · 0.4% in cash · turnover 4.7× · cost drag 0.47%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.85% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2011-01-01 → 2011-04-01 | -20.9687% | 11.4185% | 62.0941% | 5.3084% | yes | 4.777% | 0 / 61 |
| 2011-04-01 → 2011-07-01 | -9.1687% | 17.2372% | 51.5444% | -1.2856% | yes | 3.3332% | 0 / 62 |
| 2011-07-01 → 2011-10-01 | -12.316% | 11.5702% | 38.9888% | -30.1788% | no | 2.7351% | 11 / 63 |
| 2011-10-01 → 2012-01-01 | -12.7454% | 7.2683% | 32.0311% | 13.694% | yes | 2.7015% | 6 / 62 |
| 2012-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 93 names held · selection: reselect · 0.4% in cash · turnover 4.0× · cost drag 0.4%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.47% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2011-01-01 → 2011-04-01 | -17.0171% | 12.1834% | 55.9025% | 3.3715% | yes | 4.191% | 0 / 61 |
| 2011-04-01 → 2011-07-01 | -9.2007% | 15.3375% | 46.711% | -1.8463% | yes | 3.0917% | 0 / 62 |
| 2011-07-01 → 2011-10-01 | -10.0089% | 12.0908% | 36.9487% | -25.9333% | no | 2.4743% | 14 / 63 |
| 2011-10-01 → 2012-01-01 | -11.878% | 7.2137% | 30.5903% | 13.8192% | yes | 2.3556% | 7 / 62 |
| 2012-01-01 | no segment follows this rebalance, not scored | ||||||
Step 7 · 2012-01-03 → 2012-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 4 constructions · 66 names held · selection: reselect · 0.4% in cash · turnover 6.3× · cost drag 0.63%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.03% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2012-01-01 → 2012-04-01 | -9.1104% | 7.2668% | 28.529% | 12.4658% | yes | 2.0606% | 0 / 61 |
| 2012-04-01 → 2012-07-01 | -9.7852% | 7.9486% | 29.3033% | -0.3232% | yes | 2.1565% | 5 / 62 |
| 2012-07-01 → 2012-10-01 | -10.9849% | 5.9165% | 26.1544% | 3.0972% | yes | 1.961% | 0 / 62 |
| 2012-10-01 → window end | -12.3699% | 6.9053% | 32.8153% | 4.8432% | yes | 2.5611% | 0 / 61 |
All of last year's winners
Portfolio book, rebalanced quarterly · 4 constructions · 103 names held · selection: reselect · 0.4% in cash · turnover 4.8× · cost drag 0.48%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.63% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2012-01-01 → 2012-04-01 | -9.2437% | 7.1291% | 28.3897% | 11.5297% | yes | 2.0313% | 0 / 61 |
| 2012-04-01 → 2012-07-01 | -8.6032% | 8.2307% | 28.2912% | -1.9469% | yes | 2.0286% | 4 / 62 |
| 2012-07-01 → 2012-10-01 | -10.0293% | 6.2353% | 25.5615% | 4.7146% | yes | 1.9123% | 0 / 62 |
| 2012-10-01 → window end | -10.5642% | 7.4845% | 31.3672% | 1.9973% | yes | 2.3612% | 0 / 61 |
Step 8 · 2013-01-02 → 2013-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 54 names held · selection: reselect · 0.4% in cash · turnover 5.5× · cost drag 0.55% · 1 name dropped at load (55 selected, 54 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.02% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2013-01-01 → 2013-04-01 | -14.5255% | 7.2662% | 30.3323% | 10.1288% | yes | 2.5366% | 2 / 59 |
| 2013-04-01 → 2013-07-01 | -13.4402% | 7.2087% | 30.3097% | 1.6104% | yes | 2.4774% | 2 / 63 |
| 2013-07-01 → 2013-10-01 | -17.3384% | 5.8951% | 32.7372% | 12.5048% | yes | 2.7241% | 1 / 63 |
| 2013-10-01 → 2014-01-01 | -13.8093% | 8.5474% | 33.96% | 7.5828% | yes | 2.3986% | 0 / 63 |
| 2014-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 101 names held · selection: reselect · 0.4% in cash · turnover 4.6× · cost drag 0.46% · 1 name dropped at load (102 selected, 101 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.82% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2013-01-01 → 2013-04-01 | -13.3618% | 7.103% | 28.4656% | 11.2864% | yes | 2.3305% | 2 / 59 |
| 2013-04-01 → 2013-07-01 | -11.6932% | 8.9898% | 32.052% | -0.3745% | yes | 2.3254% | 2 / 63 |
| 2013-07-01 → 2013-10-01 | -16.5457% | 7.2857% | 34.9106% | 8.1233% | yes | 2.7861% | 1 / 63 |
| 2013-10-01 → 2014-01-01 | -5.5702% | 11.3895% | 29.5014% | 9.2725% | yes | 1.9933% | 2 / 63 |
| 2014-01-01 | no segment follows this rebalance, not scored | ||||||
Step 9 · 2014-01-02 → 2014-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 54 names held · selection: reselect · 0.4% in cash · turnover 5.0× · cost drag 0.5% · 1 name dropped at load (55 selected, 54 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 4.84% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2014-01-01 → 2014-04-01 | -7.2081% | 10.3371% | 29.1377% | 4.6631% | yes | 2.1025% | 2 / 60 |
| 2014-04-01 → 2014-07-01 | -3.5812% | 12.7336% | 31.9289% | 6.1929% | yes | 1.8792% | 3 / 62 |
| 2014-07-01 → 2014-10-01 | -5.0992% | 9.9914% | 25.8388% | -4.5555% | yes | 1.7374% | 1 / 63 |
| 2014-10-01 → 2015-01-01 | -2.0632% | 13.0576% | 28.8763% | 2.1826% | yes | 1.7016% | 6 / 63 |
| 2015-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 97 names held · selection: reselect · 0.4% in cash · turnover 4.0× · cost drag 0.4% · 1 name dropped at load (98 selected, 97 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 7.66% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2014-01-01 → 2014-04-01 | -4.7068% | 10.5153% | 26.4432% | 4.5138% | yes | 1.7672% | 3 / 60 |
| 2014-04-01 → 2014-07-01 | -1.2569% | 13.1631% | 29.7919% | 4.0529% | yes | 1.6143% | 4 / 62 |
| 2014-07-01 → 2014-10-01 | -3.7945% | 11.1476% | 26.7913% | -3.8364% | no | 1.6277% | 3 / 63 |
| 2014-10-01 → 2015-01-01 | -2.5565% | 11.2611% | 25.5659% | 1.5128% | yes | 1.5718% | 9 / 63 |
| 2015-01-01 | no segment follows this rebalance, not scored | ||||||
Step 10 · 2015-01-02 → 2015-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 65 names held · selection: reselect · 0.4% in cash · turnover 5.5× · cost drag 0.55%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.47% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2015-01-01 → 2015-04-01 | -3.1171% | 11.3793% | 26.4219% | 0.4534% | yes | 1.438% | 4 / 60 |
| 2015-04-01 → 2015-07-01 | -2.9045% | 9.3494% | 23.2349% | 0.6707% | yes | 1.391% | 4 / 62 |
| 2015-07-01 → 2015-10-01 | -4.1706% | 8.198% | 20.8665% | -5.4657% | no | 1.4007% | 10 / 63 |
| 2015-10-01 → 2016-01-01 | -5.7042% | 9.4563% | 25.4003% | 7.149% | yes | 1.5353% | 3 / 63 |
| 2016-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 99 names held · selection: reselect · 0.4% in cash · turnover 3.7× · cost drag 0.37%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 9.68% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2015-01-01 → 2015-04-01 | -2.9693% | 9.4138% | 22.029% | 2.6248% | yes | 1.4624% | 5 / 60 |
| 2015-04-01 → 2015-07-01 | -1.9508% | 9.4659% | 22.2902% | 0.4184% | yes | 1.3492% | 4 / 62 |
| 2015-07-01 → 2015-10-01 | -1.9856% | 10.4096% | 23.0774% | -6.9355% | no | 1.3717% | 9 / 63 |
| 2015-10-01 → 2016-01-01 | -5.2928% | 8.9616% | 23.826% | 5.5658% | yes | 1.4981% | 6 / 63 |
| 2016-01-01 | no segment follows this rebalance, not scored | ||||||
Step 11 · 2016-01-04 → 2016-12-30
The big jumpers
Portfolio book, rebalanced quarterly · 4 constructions · 65 names held · selection: reselect · 0.4% in cash · turnover 5.2× · cost drag 0.52% · 1 name dropped at load (66 selected, 65 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.24% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2016-01-01 → 2016-04-01 | -7.9522% | 8.0809% | 25.0563% | 2.1617% | yes | 1.7448% | 8 / 60 |
| 2016-04-01 → 2016-07-01 | -6.4375% | 6.8028% | 20.5067% | 0.6776% | yes | 1.4314% | 3 / 63 |
| 2016-07-01 → 2016-10-01 | -6.2102% | 7.0282% | 20.7261% | 3.5544% | yes | 1.4555% | 1 / 63 |
| 2016-10-01 → window end | -10.2812% | 3.3737% | 19.2049% | 0.2051% | yes | 1.6529% | 1 / 62 |
All of last year's winners
Portfolio book, rebalanced quarterly · 4 constructions · 112 names held · selection: reselect · 0.4% in cash · turnover 4.3× · cost drag 0.43% · 1 name dropped at load (113 selected, 112 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.05% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2016-01-01 → 2016-04-01 | -6.3238% | 8.1443% | 23.2174% | 1.7592% | yes | 1.5678% | 9 / 60 |
| 2016-04-01 → 2016-07-01 | -5.0709% | 7.602% | 20.6307% | 2.25% | yes | 1.3243% | 2 / 63 |
| 2016-07-01 → 2016-10-01 | -4.8764% | 6.9728% | 19.063% | 0.0313% | yes | 1.2733% | 2 / 63 |
| 2016-10-01 → window end | -8.6914% | 4.4014% | 19.4645% | 0.5371% | yes | 1.659% | 2 / 62 |
Step 12 · 2017-01-03 → 2017-12-29
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 69 names held · selection: reselect · 0.4% in cash · turnover 4.8× · cost drag 0.48%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.62% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2017-01-01 → 2017-04-01 | -21.0125% | -1.2782% | 25.9309% | -3.9174% | yes | 2.7559% | 1 / 61 |
| 2017-04-01 → 2017-07-01 | -15.4419% | 3.1844% | 26.0593% | -2.0614% | yes | 2.5306% | 1 / 62 |
| 2017-07-01 → 2017-10-01 | -12.7288% | 3.8156% | 23.621% | 6.228% | yes | 2.045% | 2 / 62 |
| 2017-10-01 → 2018-01-01 | -11.0532% | 5.9342% | 26.2942% | 5.87% | yes | 2.0735% | 0 / 62 |
| 2018-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 118 names held · selection: reselect · 0.4% in cash · turnover 4.2× · cost drag 0.42%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.21% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2017-01-01 → 2017-04-01 | -15.907% | 1.2371% | 23.9636% | 0.126% | yes | 2.4746% | 0 / 61 |
| 2017-04-01 → 2017-07-01 | -14.3618% | 4.0234% | 26.4985% | 0.71% | yes | 2.4616% | 1 / 62 |
| 2017-07-01 → 2017-10-01 | -10.7283% | 5.3074% | 24.343% | 7.2935% | yes | 2.1135% | 2 / 62 |
| 2017-10-01 → 2018-01-01 | -8.1429% | 6.9832% | 24.7106% | 6.507% | yes | 1.8886% | 0 / 62 |
| 2018-01-01 | no segment follows this rebalance, not scored | ||||||
Step 13 · 2018-01-02 → 2018-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 67 names held · selection: reselect · 0.4% in cash · turnover 5.3× · cost drag 0.53%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 13.77% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2018-01-01 → 2018-04-01 | -6.62% | 8.0627% | 23.3947% | 4.4768% | yes | 1.6939% | 6 / 60 |
| 2018-04-01 → 2018-07-01 | -3.3416% | 10.7156% | 25.3127% | 5.2993% | yes | 1.3456% | 4 / 63 |
| 2018-07-01 → 2018-10-01 | -2.8169% | 10.1758% | 24.9967% | 7.9785% | yes | 1.3779% | 5 / 62 |
| 2018-10-01 → 2019-01-01 | -2.6435% | 9.6493% | 23.5798% | -21.7023% | no | 1.2498% | 19 / 62 |
| 2019-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 107 names held · selection: reselect · 0.4% in cash · turnover 3.9× · cost drag 0.39%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 14.57% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2018-01-01 → 2018-04-01 | -5.3493% | 7.8168% | 21.3597% | 2.8474% | yes | 1.5004% | 6 / 60 |
| 2018-04-01 → 2018-07-01 | -2.4684% | 11.3335% | 25.6186% | 4.3988% | yes | 1.3694% | 4 / 63 |
| 2018-07-01 → 2018-10-01 | -3.0719% | 9.6391% | 24.106% | 6.1747% | yes | 1.3282% | 5 / 62 |
| 2018-10-01 → 2019-01-01 | -1.9616% | 9.5971% | 22.5981% | -20.5659% | no | 1.1377% | 21 / 62 |
| 2019-01-01 | no segment follows this rebalance, not scored | ||||||
Step 14 · 2019-01-02 → 2019-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 69 names held · selection: reselect · 0.4% in cash · turnover 5.9× · cost drag 0.59%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.24% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2019-01-01 → 2019-04-01 | -8.3092% | 6.2109% | 21.3872% | 13.5271% | yes | 1.6617% | 3 / 60 |
| 2019-04-01 → 2019-07-01 | -6.3613% | 5.8103% | 19.6489% | 1.0582% | yes | 1.4516% | 5 / 62 |
| 2019-07-01 → 2019-10-01 | -5.5984% | 6.8945% | 19.7257% | -1.073% | yes | 1.491% | 4 / 63 |
| 2019-10-01 → 2020-01-01 | -4.9271% | 6.8219% | 18.7999% | 4.2868% | yes | 1.3806% | 1 / 63 |
| 2020-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 117 names held · selection: reselect · 0.4% in cash · turnover 4.7× · cost drag 0.47%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.05% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2019-01-01 → 2019-04-01 | -6.9367% | 5.9918% | 19.2884% | 14.8599% | yes | 1.4988% | 3 / 60 |
| 2019-04-01 → 2019-07-01 | -4.995% | 6.4614% | 19.3781% | 2.062% | yes | 1.3477% | 4 / 62 |
| 2019-07-01 → 2019-10-01 | -4.2446% | 6.8177% | 18.0185% | 1.028% | yes | 1.1895% | 5 / 63 |
| 2019-10-01 → 2020-01-01 | -4.4278% | 6.1746% | 16.8675% | 2.5072% | yes | 1.1848% | 3 / 63 |
| 2020-01-01 | no segment follows this rebalance, not scored | ||||||
Step 15 · 2020-01-02 → 2020-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 4 constructions · 70 names held · selection: reselect · 0.4% in cash · turnover 4.7× · cost drag 0.47%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.84% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2020-01-01 → 2020-04-01 | -8.5437% | 5.6645% | 23.7042% | -21.3685% | no | 2.0406% | 15 / 61 |
| 2020-04-01 → 2020-07-01 | -18.2286% | 1.8978% | 27.1404% | 31.5718% | no | 2.5382% | 4 / 62 |
| 2020-07-01 → 2020-10-01 | -12.5956% | 7.7779% | 30.4753% | 6.5268% | yes | 2.0948% | 2 / 63 |
| 2020-10-01 → window end | -17.6803% | 7.0538% | 36.0415% | 15.3738% | yes | 2.7209% | 1 / 63 |
All of last year's winners
Portfolio book, rebalanced quarterly · 4 constructions · 120 names held · selection: reselect · 0.4% in cash · turnover 4.0× · cost drag 0.4%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 10.04% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2020-01-01 → 2020-04-01 | -7.6904% | 5.479% | 22.0074% | -22.1481% | no | 1.8785% | 15 / 61 |
| 2020-04-01 → 2020-07-01 | -17.0642% | 2.2287% | 26.1628% | 31.0014% | no | 2.2839% | 5 / 62 |
| 2020-07-01 → 2020-10-01 | -12.7795% | 8.6663% | 32.7942% | 7.2077% | yes | 2.2152% | 3 / 63 |
| 2020-10-01 → window end | -16.4976% | 7.9998% | 36.5611% | 10.6663% | yes | 2.8646% | 2 / 63 |
Step 16 · 2021-01-04 → 2021-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 68 names held · selection: reselect · 0.4% in cash · turnover 5.5× · cost drag 0.55%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.61% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2021-01-01 → 2021-04-01 | -14.3503% | 10.79% | 39.9751% | 7.1213% | yes | 2.8223% | 4 / 60 |
| 2021-04-01 → 2021-07-01 | -34.1468% | 2.8072% | 60.9144% | 9.1376% | yes | 4.2026% | 0 / 62 |
| 2021-07-01 → 2021-10-01 | -29.4167% | 7.347% | 57.3523% | -0.5594% | yes | 3.7937% | 0 / 63 |
| 2021-10-01 → 2022-01-01 | -24.948% | 10.4972% | 57.2443% | 6.6824% | yes | 3.4732% | 0 / 63 |
| 2022-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 122 names held · selection: reselect · 0.4% in cash · turnover 4.6× · cost drag 0.46%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.81% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2021-01-01 → 2021-04-01 | -13.9253% | 10.6091% | 38.913% | 3.9194% | yes | 2.9309% | 2 / 60 |
| 2021-04-01 → 2021-07-01 | -25.2859% | 7.7852% | 55.8266% | 7.077% | yes | 3.5655% | 0 / 62 |
| 2021-07-01 → 2021-10-01 | -24.9677% | 9.6661% | 55.0279% | -0.4631% | yes | 3.5916% | 0 / 63 |
| 2021-10-01 → 2022-01-01 | -21.4745% | 11.0996% | 52.4645% | 5.7119% | yes | 3.3309% | 0 / 63 |
| 2022-01-01 | no segment follows this rebalance, not scored | ||||||
Step 17 · 2022-01-03 → 2022-12-30
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 61 names held · selection: reselect · 0.4% in cash · turnover 4.2× · cost drag 0.42%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.07% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2022-01-01 → 2022-04-01 | -19.7693% | 10.5384% | 56.828% | 4.4634% | yes | 3.1647% | 1 / 61 |
| 2022-04-01 → 2022-07-01 | -20.1416% | 9.0702% | 53.2791% | -14.6451% | yes | 3.1006% | 6 / 61 |
| 2022-07-01 → 2022-10-01 | -10.829% | 10.3596% | 34.0476% | -4.3574% | yes | 2.0998% | 6 / 63 |
| 2022-10-01 → 2023-01-01 | -9.9304% | 9.8229% | 34.0627% | 7.9274% | yes | 2.2177% | 2 / 62 |
| 2023-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 113 names held · selection: reselect · 0.4% in cash · turnover 3.5× · cost drag 0.35%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.88% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2022-01-01 → 2022-04-01 | -14.1329% | 11.1691% | 47.369% | -2.5127% | yes | 2.6888% | 2 / 61 |
| 2022-04-01 → 2022-07-01 | -15.5212% | 9.057% | 44.1151% | -16.1662% | no | 2.5354% | 8 / 61 |
| 2022-07-01 → 2022-10-01 | -11.1615% | 10.8345% | 35.6139% | -2.6084% | yes | 2.3054% | 5 / 63 |
| 2022-10-01 → 2023-01-01 | -10.0698% | 8.4578% | 30.9451% | 7.8925% | yes | 2.1656% | 2 / 62 |
| 2023-01-01 | no segment follows this rebalance, not scored | ||||||
Step 18 · 2023-01-03 → 2023-12-29
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 74 names held · selection: reselect · 0.4% in cash · turnover 5.1× · cost drag 0.51%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.22% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2023-01-01 → 2023-04-01 | -7.9446% | 10.3745% | 34.5556% | 0.1291% | yes | 2.2745% | 1 / 61 |
| 2023-04-01 → 2023-07-01 | -10.8392% | 5.3914% | 26.4979% | 3.75% | yes | 2.1184% | 1 / 61 |
| 2023-07-01 → 2023-10-01 | -15.9905% | 4.5315% | 30.2321% | -6.7913% | yes | 2.7049% | 0 / 62 |
| 2023-10-01 → 2024-01-01 | -19.5666% | 1.3396% | 27.8512% | 16.8763% | yes | 2.7105% | 1 / 62 |
| 2024-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 125 names held · selection: reselect · 0.4% in cash · turnover 4.4× · cost drag 0.44%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.81% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2023-01-01 → 2023-04-01 | -7.8221% | 10.8386% | 35.545% | 0.2004% | yes | 2.1552% | 1 / 61 |
| 2023-04-01 → 2023-07-01 | -9.1275% | 5.7788% | 24.8539% | 3.9708% | yes | 1.8537% | 1 / 61 |
| 2023-07-01 → 2023-10-01 | -14.6149% | 4.6497% | 28.4126% | -5.3493% | yes | 2.446% | 0 / 62 |
| 2023-10-01 → 2024-01-01 | -17.1578% | 2.7507% | 27.6033% | 16.521% | yes | 2.5176% | 0 / 62 |
| 2024-01-01 | no segment follows this rebalance, not scored | ||||||
Step 19 · 2024-01-02 → 2024-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 4 constructions · 65 names held · selection: reselect · 0.4% in cash · turnover 5.5× · cost drag 0.55%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 3.23% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2024-01-01 → 2024-04-01 | -22.5611% | 1.4107% | 29.5669% | 17.4432% | yes | 2.9842% | 0 / 60 |
| 2024-04-01 → 2024-07-01 | -16.2724% | 5.4336% | 32.9448% | 2.284% | yes | 2.6464% | 0 / 62 |
| 2024-07-01 → 2024-10-01 | -10.9871% | 10.7105% | 35.0822% | 1.4482% | yes | 2.2223% | 6 / 63 |
| 2024-10-01 → window end | -9.2265% | 11.0305% | 33.4248% | 4.7179% | yes | 2.0648% | 2 / 63 |
All of last year's winners
Portfolio book, rebalanced quarterly · 4 constructions · 111 names held · selection: reselect · 0.4% in cash · turnover 4.5× · cost drag 0.45%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 3.63% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2024-01-01 → 2024-04-01 | -19.4041% | 3.4682% | 29.8304% | 17.1915% | yes | 2.7341% | 0 / 60 |
| 2024-04-01 → 2024-07-01 | -12.6057% | 7.9813% | 33.5821% | 2.4193% | yes | 2.3539% | 1 / 62 |
| 2024-07-01 → 2024-10-01 | -8.9287% | 10.6709% | 32.2042% | 5.4222% | yes | 1.9188% | 6 / 63 |
| 2024-10-01 → window end | -6.1319% | 11.3754% | 30.1764% | 1.7256% | yes | 1.7943% | 2 / 63 |
Step 20 · 2025-01-02 → 2025-12-31
The big jumpers
Portfolio book, rebalanced quarterly · 5 constructions · 62 names held · selection: reselect · 0.4% in cash · turnover 4.9× · cost drag 0.49%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.94% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2025-01-01 → 2025-04-01 | -4.4237% | 12.6822% | 29.7727% | -8.3281% | no | 1.8453% | 11 / 59 |
| 2025-04-01 → 2025-07-01 | -5.7664% | 9.6955% | 29.4824% | 27.0616% | yes | 1.9666% | 5 / 61 |
| 2025-07-01 → 2025-10-01 | -7.906% | 11.4261% | 32.5773% | 6.8242% | yes | 1.7536% | 0 / 63 |
| 2025-10-01 → 2026-01-01 | -9.4119% | 12.0181% | 35.9565% | 8.462% | yes | 1.848% | 6 / 63 |
| 2026-01-01 | no segment follows this rebalance, not scored | ||||||
All of last year's winners
Portfolio book, rebalanced quarterly · 5 constructions · 108 names held · selection: reselect · 0.4% in cash · turnover 4.0× · cost drag 0.4%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.13% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2025-01-01 → 2025-04-01 | -3.1106% | 11.8239% | 26.4539% | -4.3741% | no | 1.5554% | 11 / 59 |
| 2025-04-01 → 2025-07-01 | -3.3189% | 8.4048% | 22.83% | 14.6033% | yes | 1.3788% | 5 / 61 |
| 2025-07-01 → 2025-10-01 | -4.5411% | 11.2269% | 27.8698% | 6.556% | yes | 1.4005% | 0 / 63 |
| 2025-10-01 → 2026-01-01 | -7.1137% | 13.5126% | 36.2956% | 3.5717% | yes | 2.0194% | 4 / 63 |
| 2026-01-01 | no segment follows this rebalance, not scored | ||||||