
Tracking Fund Managers from SEC Filings, Three Ways
Money managers have a difficult task. They manage other people's money, which is a massive responsibility, and therefore the field is highly regulated. The rules stand against cartel-like operations and against pump and dump operations in shallow assets and markets. It is well defined what a manager can buy and how. This includes that they have to show what they hold in SEC filings, four times a year, and from two such reports anyone can read what was bought and what was sold.
This has inspired many people to track fund managers from their SEC filings. Of course this brings a layer of delay, but it is the best a retail investor can do who has no access to the board rooms of these companies.
Money managers are often criticised for shady operations, but they are actually well tamed, and one can say even quite restricted. This is no surprise for people who know the history: the investment trusts of the twenties, the mutual funds caught trading after the bell, Madoff. These were lessons, and every lesson learned came back as a regulation for the industry.
With all the best intentions and regulations there is still something that cannot be avoided, and that is peer communication. There are still concentrations in the field, perhaps because of this, perhaps because of the general market narrative. It is hard to say that something funny is going on, and this can be observed in our study as well.
What we did in this study was to follow the managers from their reports, unfortunately with a realistic delay, because just like you we do not have microphones in their board rooms. We did it in three ways, over twenty years, to show what it means for a retail investor who has the idea of following the big funds. In short, such an investor ended up about where the whole index ended up. The one basket that pulled ahead, in the years after the pandemic, was the basket of what the managers sold.
One idea, three followers
Imagine a retail investor with a simple idea. The big funds have analysts, models and a seat in front of every chief executive. He has none of that. But four times a year the law makes the funds show their hands, so he decides to do what they do. He will read the reports and buy what the best of them just bought.
We played this investor for twenty years, and we gave him two neighbours. The first neighbour does the opposite and buys what the same managers just sold. The second follows every big firm, trading desks included, and not only the stock pickers. Three ways of following the same reports. This is their story, and after each part we say what it meant.
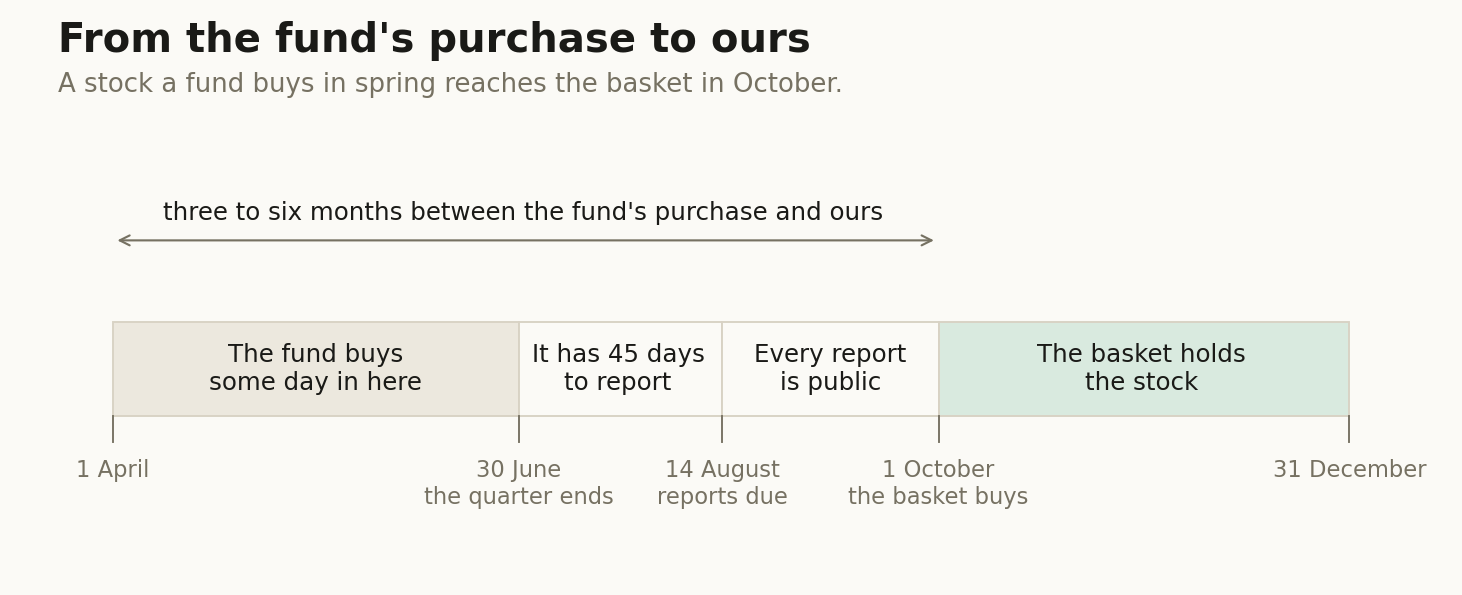
The managers have forty-five days after the end of a quarter to file, and they take them. In the last ten years almost two out of three reports on our list became public on the very last day. Nobody shows a hand one day earlier than the law asks.
So the reports arrive together, in the middle of February, May, August and November, and by the evening the websites carry the headlines: this one bought, that one sold. Our follower reads them and acts on the first day of the next quarter, as somebody with a job and a brokerage app does.
What it meant: the follower never sees a decision. He sees a photograph, taken six weeks earlier, of trades that can be four and a half months old. Figure 2 shows the calendar. Three to six months lie between the fund's purchase and his.
Nvidia and Meta: two adventures
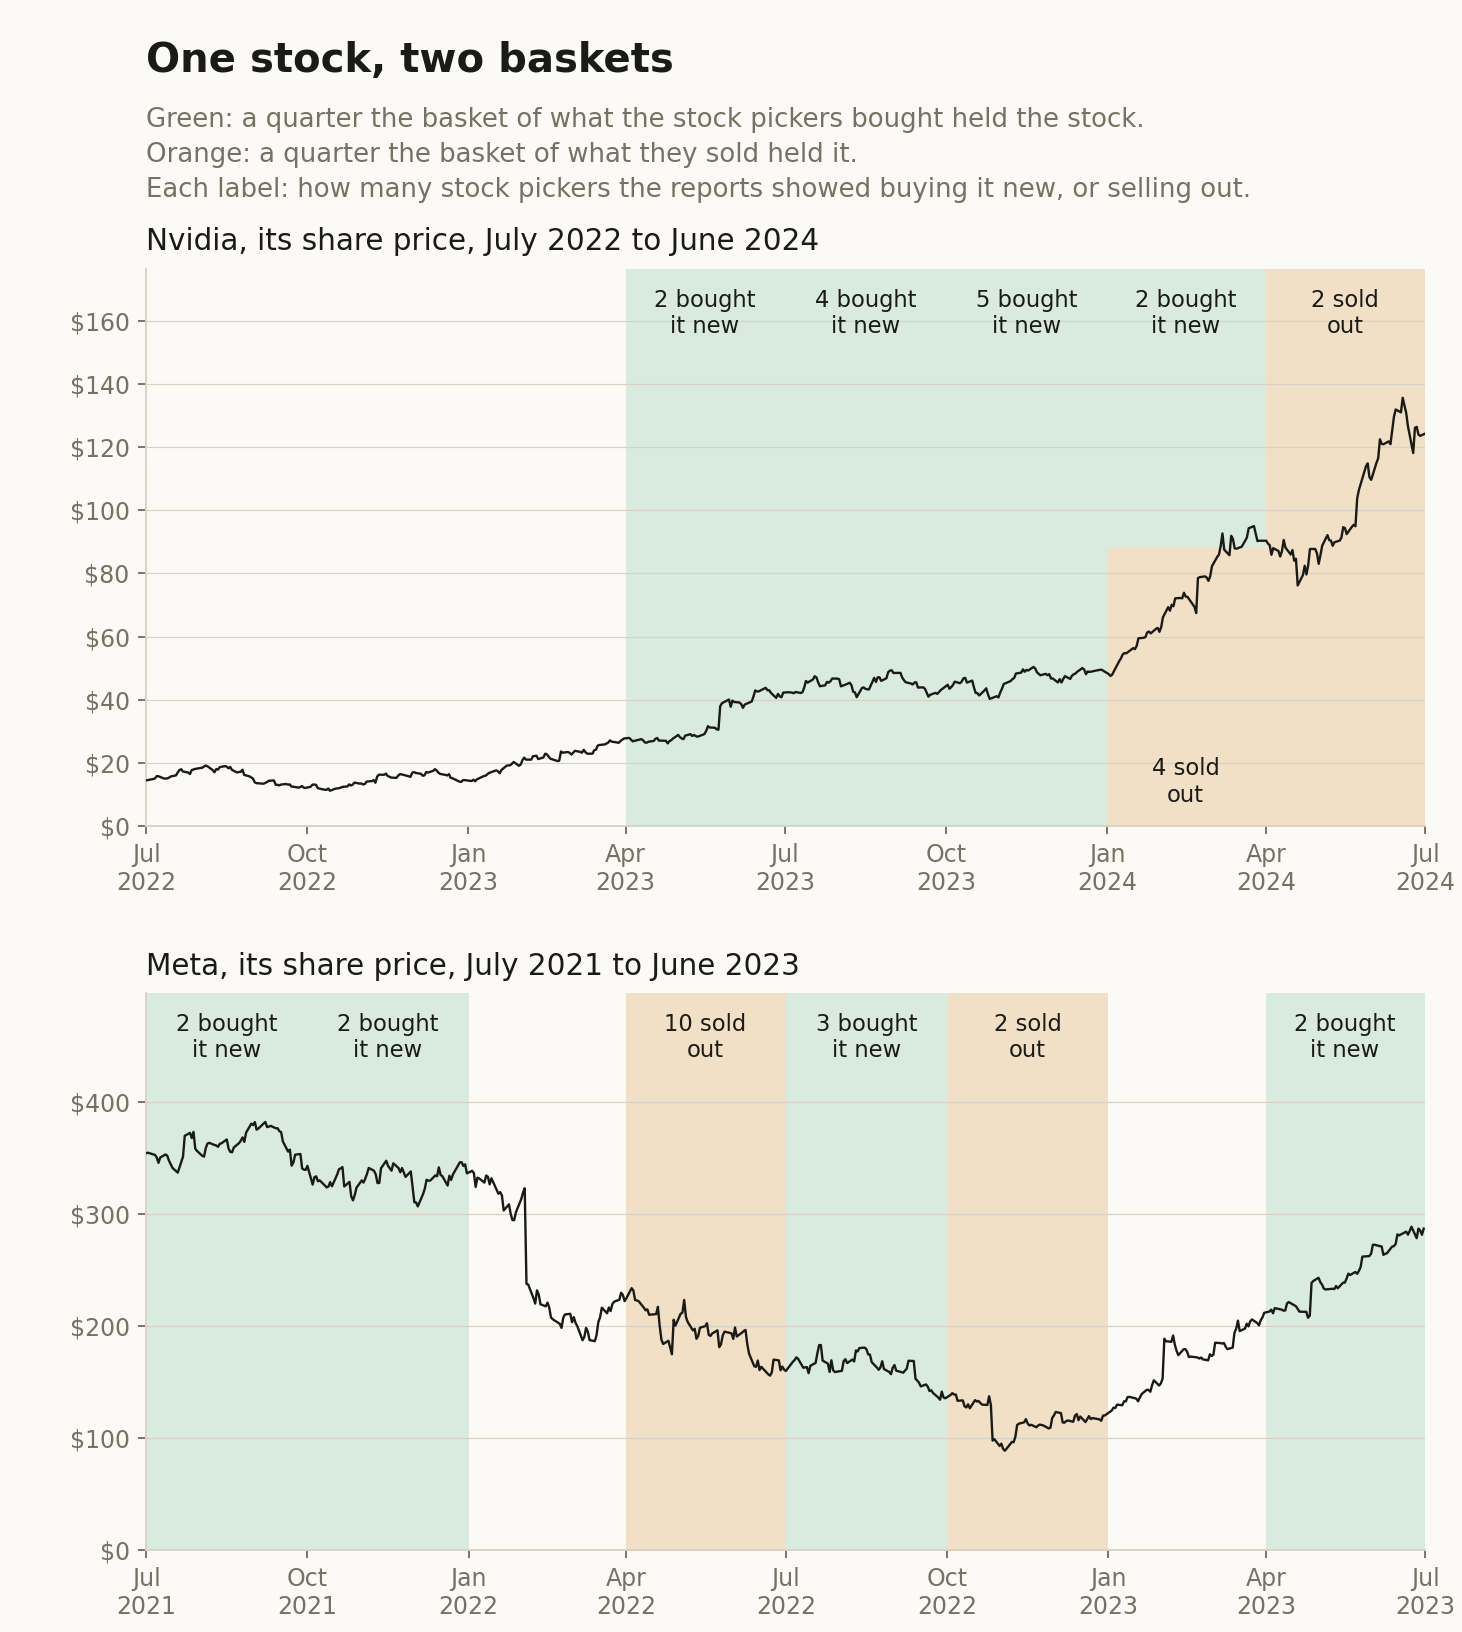
Figure 1 tells the first adventure. Early in the artificial intelligence boom two of the stock pickers bought Nvidia for the first time. A quarter later four more did, then five more. Our follower, always a season behind, bought it too and held it for a year.
Then the reports turned. Four of the five who had bought it new in the spring were out again by the autumn. The follower read that in November, and at the start of the year his neighbour, the one who buys what they sell, picked Nvidia up. Over the next six months the share more than doubled, and the neighbour's whole basket made about three times what the index made.
What it meant: a manager who sells is not saying that the stock will fall. These four had just watched it more than triple in a year. Whatever their reasons were, the stock went on without them.
The second adventure went the other way. In one quarter ten stock pickers sold out of Meta together. The neighbour, true to his rule, bought what they had dropped, and this time the sellers were right. The share kept falling. It fell further when three stock pickers bought it new on the way down and our follower went in with them. A few months later it found its low and turned.
What it meant: the same signal, managers leaving together, was a warning for Meta and nothing of the kind for Nvidia. The report cannot tell the two cases apart, and so the follower cannot either.
How we kept score for the three followers
The list. We follow sixty-five firms that a retail investor might want to copy. Berkshire Hathaway, Pershing Square, Baupost, Appaloosa, Third Point and Greenlight are on it, with others known for picking stocks, and so are the large trading firms such as Renaissance, Citadel, Two Sigma and Millennium. Not all of them were filing twenty years ago. The first reports we read come from about half as many firms.
Bought and sold. The report does not say "we bought". It shows a holding. So we put two reports of the same firm side by side. A stock that is in the new report and was not in the one before was bought new. A stock that was in the report before and is gone from the new one was sold out. We read a report only from the day it became public, never earlier.
The stock pickers. A trading desk reports thousands of stocks and hundreds of new ones every quarter, so "two firms bought it new" would mostly mean two trading desks. Because of this we call a firm a stock picker in a quarter when its report for that quarter holds five hundred stocks or fewer. In a usual quarter that is all but about eight of the firms.
The three baskets. We count firms and not dollars. A stock enters a basket when at least two firms did the same thing in the same quarter. The follower's basket is the S&P 500 stocks that at least two stock pickers bought new. The first neighbour's basket is the S&P 500 stocks that at least two stock pickers sold out of. Nobody advertises this one. It is here because a test of what the managers buy needs something to stand against, and the cleanest thing to stand against is what the same managers threw out. The second neighbour's basket is the S&P 500 stocks that at least two of all the followed firms bought new, trading desks included, which makes a much longer list.
The money. On the first trading day of each quarter a basket is built again from the newest reports, each stock gets an equal share, and it is held for the quarter. Dividends are counted and trading costs are charged on every change. The S&P 500 is the list as it stood on each day, with the companies that later left it. The yardstick is the same five hundred stocks held in equal parts, because the baskets hold their stocks in equal parts too.
The quarter everybody sold, and the year they shopped elsewhere
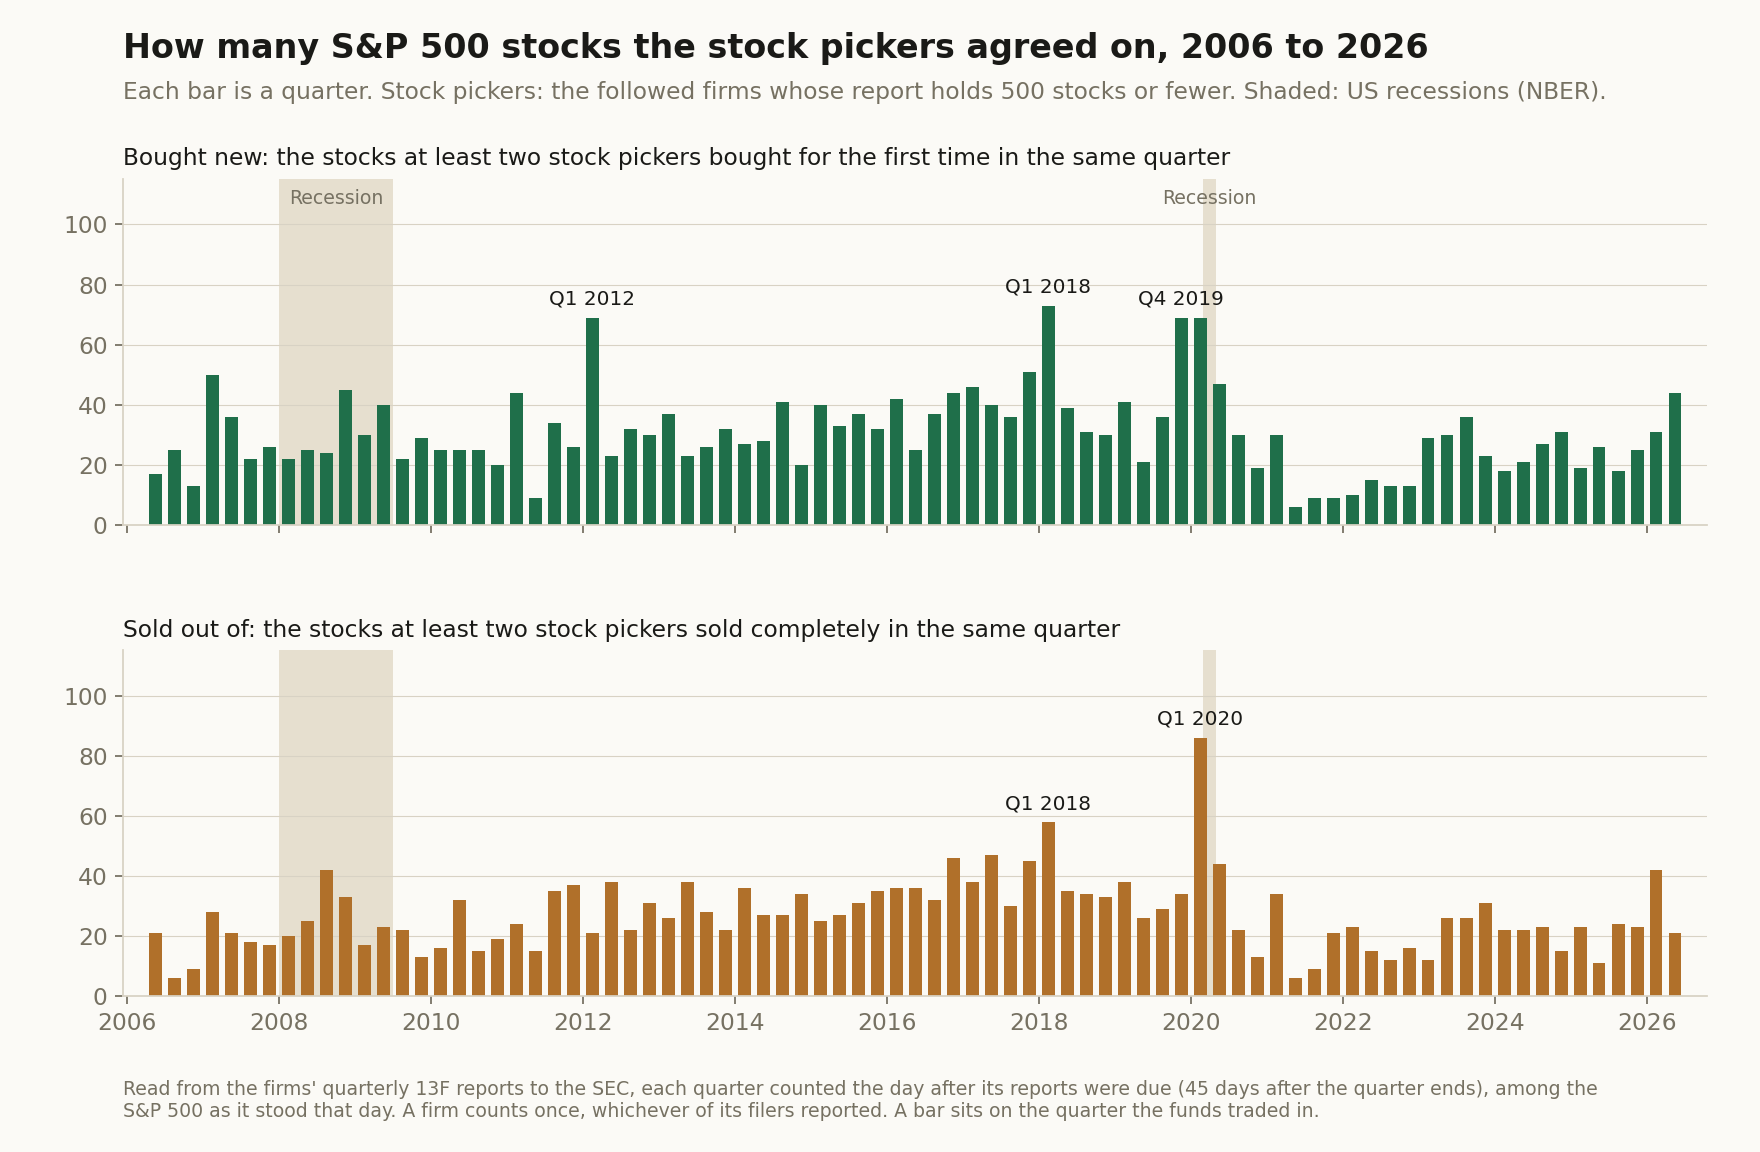
Managers talk to each other. They sit at the same conferences, read the same research and hear the same story from the market, and no regulation can stop that or should. So how often do they end up in the same stock at the same time? Figure 3 counts it for every quarter of the twenty years. The green bars are the S&P 500 stocks that at least two stock pickers bought for the first time in that quarter, the orange bars the stocks that at least two sold completely.
In a usual quarter the answer is between twenty-five and thirty stocks out of five hundred, on either side. This is a concentration, but it is hard to call it a herd, and nothing in it says that something funny is going on.
Two moments stand out. In the quarter the pandemic hit, the stock pickers sold out of more stocks at once than in any other quarter of the twenty years, and it was the quarter in which the market made its low. A year later, in the year of the listing boom, they bought about as many new names as ever, but most of them outside the S&P 500. For a few quarters our follower's basket held fewer than ten stocks, because inside the index there was almost nothing the stock pickers agreed on.
What it meant: the managers stand in a crowd too. They left the most stocks in the quarter prices were lowest, and when a new fashion arrived they followed it out of the index and left the follower with an almost empty basket.
Twenty years later
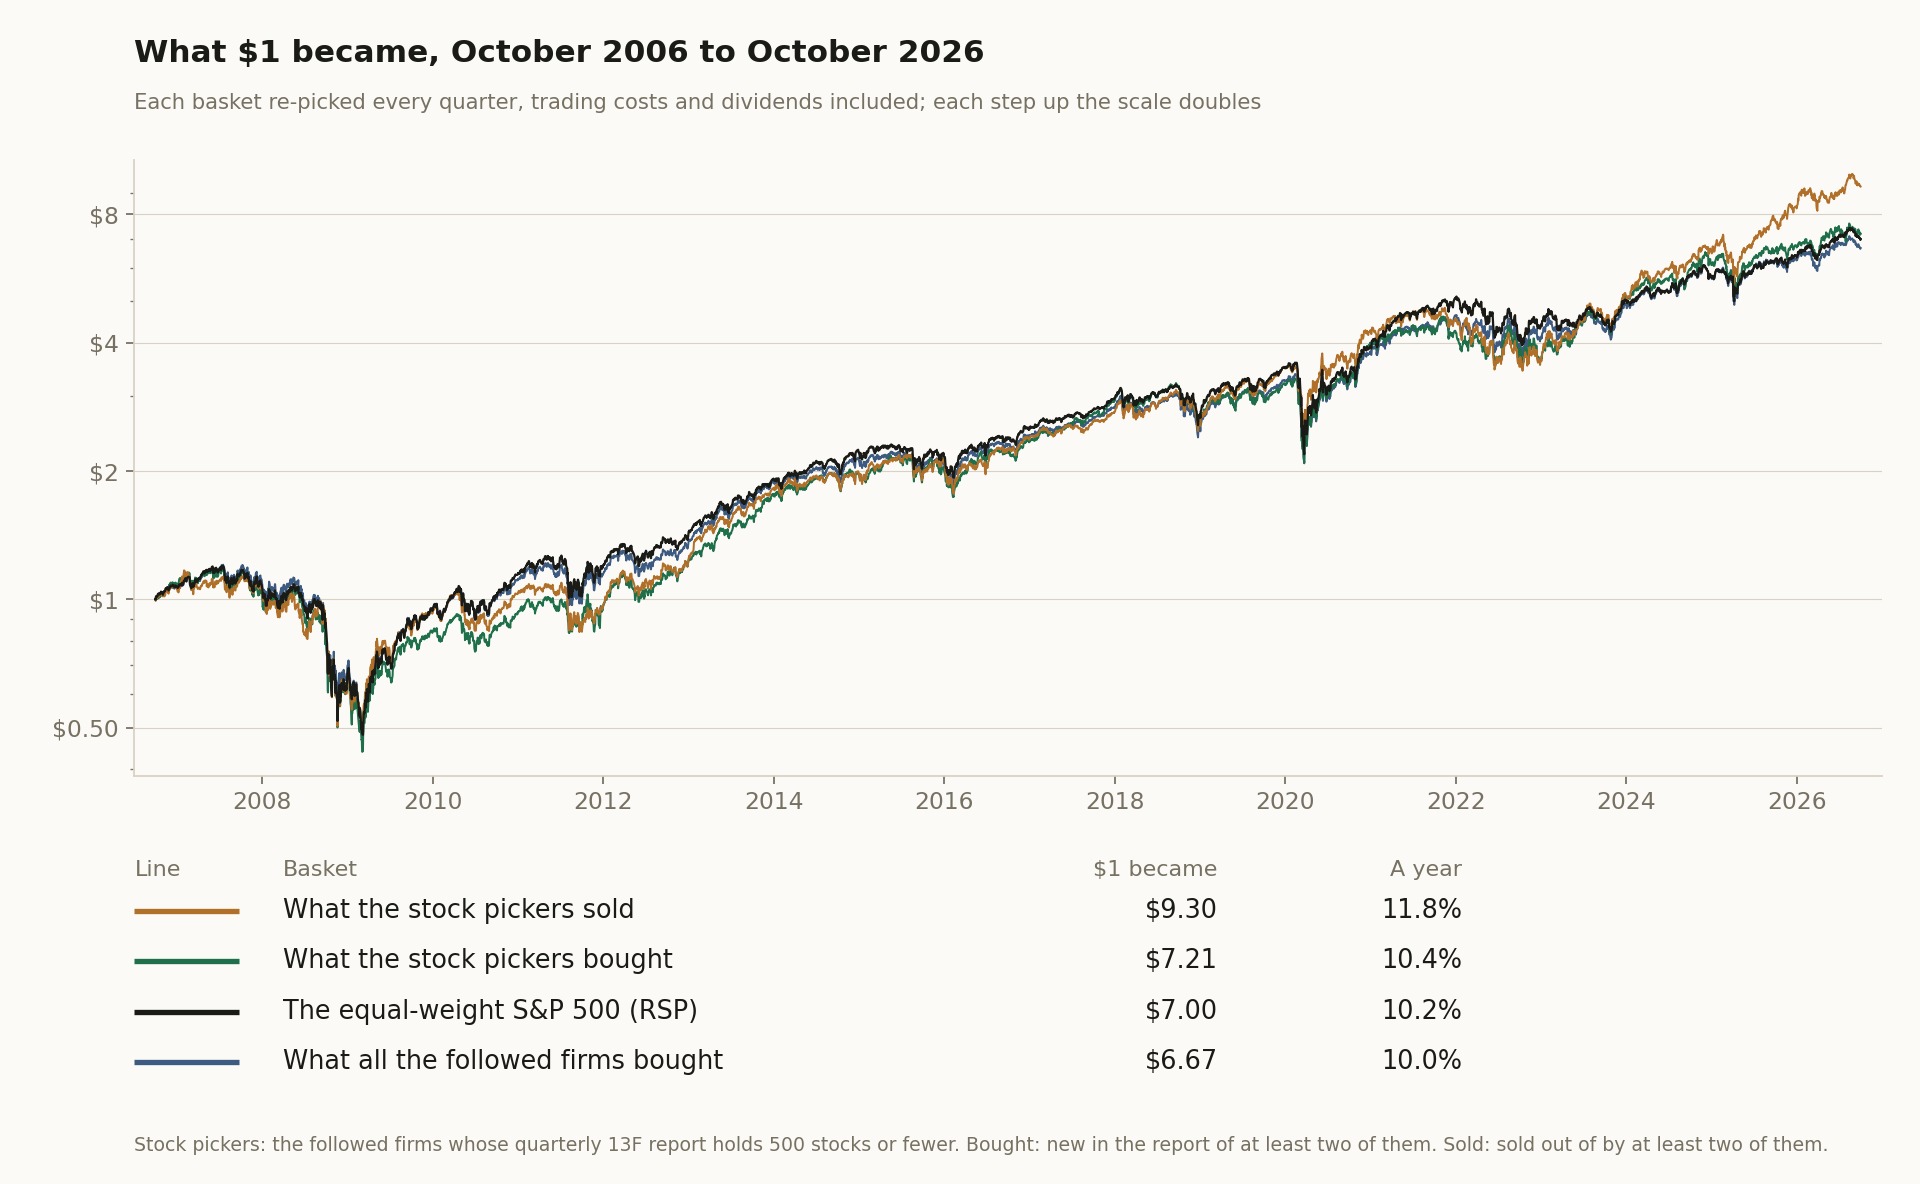
Figure 4 is the end of the story. It follows one dollar of each follower and one dollar in the index. For most of the twenty years the four lines cannot be told apart. The three followers went through the same two crashes as the index, and each came out with about the same money as somebody who had bought all five hundred stocks in equal parts and never read a report.
The orange line is the surprise. It is the neighbour who bought what the stock pickers sold. After the first sixteen years he stood behind the index, like the other two. He pulled away in the years after the pandemic.
There is an argument for why it happened then. When a fund sells out of a stock, somebody buys it. Since the pandemic that somebody is more and more often a regular person. Trading became free of commission, the market arrived on every phone, and the share of regular people in the daily trading of American stocks about doubled. A stock the professionals walk away from is not left alone any more. The reports cannot prove this, and twenty years are too short to rule out chance, but it fits what the line shows.
What it meant: following the big funds from their reports did no harm and brought no advantage. And if the argument holds, the retail investor has become a character in the story himself. He is the buyer on the other side when a fund sells.
1 Methodology, in detail (click to open)
1 Methodology
The design was fixed before the first run. It has two parts, because one run compares two baskets: what the stock pickers bought against what they sold, and what the stock pickers bought against what all the followed firms bought. Each part is 20 one-year runs, one starting on 1 October of every year from 2006 to 2025, and the years are chained into one line. Inside a year the basket is rebuilt on the first trading day of each calendar quarter.
The firms are the 65 that the data library follows; a firm with several filers counts once, and a report counts from the day it became public. At each pick the card reads the newest quarter whose reports were all due by that day, so the pick on 1 October reads the quarter that ended on 30 June. A firm is a stock picker in a quarter when its report for that quarter holds 500 securities or fewer; in a usual quarter 52 firms are, and 8 are not. A stock must be a member of the S&P 500 on the day of the pick, as the index stood that day.
In the 42 quarters from 2016 on, 64% of the firms' reports became public on the due day itself and 82% in its last three days. Each basket holds its stocks in equal parts, counts dividends, and pays 0.10% spread, 0.05% slippage and 0.02% market impact on every trade. A quarter with no stock would be held in cash; there was none. The yardstick is RSP, the fund that holds the S&P 500 in equal parts, with its dividends.
How large must a gap be before it means something? We took the 20 yearly differences between two lines and compared their average with their spread from year to year. What the stock pickers sold beat what they bought by 1.6 points a year on average, with a spread of 6.9 points; a gap of that size appears by chance about one time in three (t = 1.0, where the usual line is 2.1). Against RSP the three baskets averaged 0.3 points a year ahead (what the stock pickers bought), 1.9 points ahead (what they sold) and 0.3 points behind (what all the followed firms bought), with spreads of 5.9, 8.8 and 3.2 points (t = 0.3, 1.0 and 0.4). None reaches the line. In the six months of the Nvidia story, January to June 2024, the basket of what the stock pickers sold made 14.7% and RSP 5.0%.
2 Results
Findings
From October 2006 to October 2026, with dividends and trading costs, $1 in the equal-weight S&P 500 (RSP) became $7.00. In the basket of what the stock pickers bought it became $7.21, in the basket of what they sold $9.30, and in the basket of what all the followed firms bought $6.67. After the first sixteen years all three baskets stood behind RSP ($3.72, $3.52 and $3.84 against $4.03); the lead of what the stock pickers sold was made in the four years since.
2.1 Headline
Table 1. Each basket and the yardstick from October 2006 to October 2026, with dividends and trading costs. Worst fall is the deepest fall from a high over the twenty years. Stocks a year is how many different stocks a basket held in a usual year; at one time it held about 30, 24 and 114.
| Basket | $1 became | A year | Worst fall | Years ahead of RSP | Stocks a year |
|---|---|---|---|---|---|
| What the stock pickers bought | $7.21 | 10.4% | −63.0% | 10 of 20 | about 106 |
| What the stock pickers sold | $9.30 | 11.8% | −57.4% | 12 of 20 | about 100 |
| What all the followed firms bought | $6.67 | 10.0% | −60.0% | 8 of 20 | about 326 |
| The equal-weight S&P 500 (RSP) | $7.00 | 10.2% | −59.8% |
Sections 2.2 to 4, the full record: every year, every test, and how each one was run (click to open)
The registration names the two groups compared What at least two stock pickers bought new and What at least two stock pickers sold out of; this paper calls them What the stock pickers bought and What the stock pickers sold.
2.2 Per-step results
| # | Out-of-sample window | What the stock pickers bought SR | What the stock pickers sold SR | What all the followed firms bought SR |
|---|---|---|---|---|
| 1 | 2006-10-02 → 2007-10-01 | 0.96 | 0.77 | 1.26 |
| 2 | 2007-10-01 → 2008-09-30 | -0.83 | -0.52 | -0.85 |
| 3 | 2008-10-01 → 2009-10-01 | 0.16 | 0.10 | 0.17 |
| 4 | 2009-10-01 → 2010-10-01 | 0.58 | 0.64 | 0.91 |
| 5 | 2010-10-01 → 2011-09-30 | 0.05 | -0.26 | -0.05 |
| 6 | 2011-10-03 → 2012-09-28 | 1.27 | 1.87 | 1.46 |
| 7 | 2012-10-01 → 2013-10-01 | 2.45 | 2.66 | 2.35 |
| 8 | 2013-10-01 → 2014-10-01 | 1.68 | 1.15 | 1.32 |
| 9 | 2014-10-01 → 2015-10-01 | 0.17 | 0.17 | 0.15 |
| 10 | 2015-10-01 → 2016-09-30 | 0.93 | 0.99 | 1.06 |
| 11 | 2016-10-03 → 2017-09-29 | 2.22 | 1.70 | 1.75 |
| 12 | 2017-10-02 → 2018-10-01 | 1.23 | 1.30 | 1.06 |
| 13 | 2018-10-01 → 2019-10-01 | -0.29 | 0.28 | 0.09 |
| 14 | 2019-10-01 → 2020-09-30 | 0.46 | 0.57 | 0.37 |
| 15 | 2020-10-01 → 2021-10-01 | 1.64 | 1.49 | 1.96 |
| 16 | 2021-10-01 → 2022-09-30 | -0.44 | -0.93 | -0.42 |
| 17 | 2022-10-03 → 2023-09-29 | 0.96 | 1.31 | 0.71 |
| 18 | 2023-10-02 → 2024-09-30 | 1.95 | 2.13 | 2.24 |
| 19 | 2024-10-01 → 2025-10-01 | 0.55 | 1.09 | 0.47 |
| 20 | 2025-10-01 → 2026-10-01 | 0.67 | 1.18 | 0.65 |
2.3 Search accounting
No search record exists for this design. It was not promoted from a recorded evolving search, so the number of alternatives tried before it, on paper, in another tool, or in the author's head, is unknown. Unknown is a different fact from one: a study with no lineage is not a strategy with one trial, it is a strategy with an unrecorded number of them. Accordingly no count of alternatives tried is claimed, and nothing in this paper is corrected for a search that was never recorded; the number that stands is the raw out-of-sample result plus this disclosure. The registered per-step record below (§4) still guarantees each window's hypothesis was hashed and registered before that window was scored.
2.4 The comparison
Both arms trade the same registered windows, so their returns can be PAIRED: inside each window the two return series are inner-joined date by date and the difference rWhat the stock pickers bought − rWhat the stock pickers sold is the object under test. Because this is ONE pre-declared contrast, frozen at registration before any window was scored, the paired statistic needs no multiple-testing deflation, and the per-arm pooled numbers above are likewise uncorrected, because this design has no recorded search to correct against (§2.3). The paired contrast carries that gap differently from the arm levels: it was declared before each window ran and it is scored on the difference, so no window could be read first and scored after. What the timestamps cannot speak to is how this contrast came to be the declared one, which is the limit §2.3 states.
In the table: Arm A = What the stock pickers bought · Arm B = What the stock pickers sold.
| # | Window | Paired bars | Arm A | Arm B | Δ | Leader | What all the followed firms bought |
|---|---|---|---|---|---|---|---|
| 1 | 2006-10-03 → 2007-10-01 | 250 | +14.0% | +11.7% | +2.3 pp | Arm A | +17.8% |
| 2 | 2007-10-02 → 2008-09-30 | 252 | -27.6% | -19.0% | -8.6 pp | Arm B | -24.6% |
| 3 | 2008-10-02 → 2009-10-01 | 252 | -5.5% | -7.9% | +2.4 pp | Arm A | -4.0% |
| 4 | 2009-10-02 → 2010-10-01 | 252 | +10.0% | +11.5% | -1.5 pp | Arm B | +18.7% |
| 5 | 2010-10-04 → 2011-09-30 | 252 | -1.1% | -8.7% | +7.6 pp | Arm A | -3.3% |
| 6 | 2011-10-04 → 2012-09-28 | 250 | +33.6% | +40.0% | -6.4 pp | Arm B | +30.5% |
| 7 | 2012-10-02 → 2013-10-01 | 250 | +39.3% | +42.3% | -3.0 pp | Arm B | +34.5% |
| 8 | 2013-10-02 → 2014-10-01 | 252 | +22.6% | +14.2% | +8.4 pp | Arm A | +14.8% |
| 9 | 2014-10-02 → 2015-10-01 | 252 | +1.4% | +1.4% | +0.0 pp | tie | +1.0% |
| 10 | 2015-10-02 → 2016-09-30 | 252 | +15.4% | +17.6% | -2.2 pp | Arm B | +16.3% |
| 11 | 2016-10-04 → 2017-09-29 | 250 | +22.6% | +15.7% | +6.8 pp | Arm A | +15.2% |
| 12 | 2017-10-03 → 2018-10-01 | 251 | +16.3% | +17.1% | -0.8 pp | Arm B | +12.4% |
| 13 | 2018-10-02 → 2019-10-01 | 251 | -6.6% | +3.4% | -10.0 pp | Arm B | +0.0% |
| 14 | 2019-10-02 → 2020-09-30 | 252 | +10.7% | +14.7% | -4.0 pp | Arm B | +6.9% |
| 15 | 2020-10-02 → 2021-10-01 | 252 | +30.9% | +27.4% | +3.5 pp | Arm A | +33.8% |
| 16 | 2021-10-04 → 2022-09-30 | 251 | -12.5% | -23.4% | +10.8 pp | Arm A | -10.6% |
| 17 | 2022-10-04 → 2023-09-29 | 249 | +20.5% | +29.3% | -8.8 pp | Arm B | +12.1% |
| 18 | 2023-10-03 → 2024-09-30 | 250 | +33.2% | +37.6% | -4.5 pp | Arm B | +33.9% |
| 19 | 2024-10-02 → 2025-10-01 | 250 | +10.4% | +23.9% | -13.6 pp | Arm B | +7.5% |
| 20 | 2025-10-02 → 2026-10-01 | 251 | +10.1% | +20.8% | -10.7 pp | Arm B | +7.8% |
Paired Sharpe of the difference track: -0.12 · block bootstrap (2000 paths, block 10, seed 1234): P(What the stock pickers bought beats What the stock pickers sold) = 31.1%.
Window win-rate. What the stock pickers bought led 7 of 20 windows (35.0%), What the stock pickers sold led 12, and 1 windows were ties, and the mean window gap of -1.60 pp points the same way. Widest single window: 2024 at -13.6 pp.
| Period | Windows | What the stock pickers bought | What the stock pickers sold | Mean gap | What the stock pickers bought led |
|---|---|---|---|---|---|
| All windows | 20 | +11.88% | +13.49% | -1.60 pp | 7/20 |
| Before 2010 | 4 | -2.25% | -0.91% | -1.34 pp | 2/4 |
| 2010 onward | 16 | +15.42% | +17.09% | -1.67 pp | 5/16 |
3 The circuit
The strategy is a circuit of platform primitives, frozen when the study is registered. Below is the circuit as wired on the canvas, the objective it encodes and how the search runs through it, followed by the mathematics each primitive actually computes, the same formulas the execution engine runs. The complete parameterisation is preserved in the study ledger (Appendix A).
The sentence below is the registration record, generated when the circuit was registered and printed verbatim; the authored description of the design is Section 1.
A COMPARATIVE study: What at least two stock pickers bought new vs What at least two stock pickers sold out of, walked on the same registered out-of-sample windows. What at least two stock pickers bought new: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. What at least two stock pickers sold out of: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. The arms differ in: What big funds hold, Keep stocks the funds: Bought new → Sold out of. The contrast under test: whether What at least two stock pickers bought new generates better risk-adjusted returns than What at least two stock pickers sold out of over the identical out-of-sample windows.
Every block in this study is a card from the platform's catalog: the Universe card's S&P 500 as it stood on each date, the SEC card What big funds hold with its settings for bought new or sold out of, how many funds and which funds, and the Portfolio Forward Test re-picking every quarter with its Transaction Cost card.
Envelopes show counts, ratios, dates, and the parameters the author chose. Full price and per-name data series are not republished: the underlying market data is licensed to QuanterLab. Point figures quoted in the prose, a named holding's return over a stated span, are summary facts derived from public market prices, not redistributed series.
The objective and the search
What at least two stock pickers bought new
| Universe | S&P 500 index constituents. |
|---|---|
| Validation & out-of-sample | portfolio forward test (holds the weights it is given, re-set at each rebalance) (1y horizon from the anchor, quarterly rebalance, dividends counted); overlays: Transaction Cost. |
| Other components | Sec: What big funds hold. |
What at least two stock pickers sold out of
The specification is identical to What at least two stock pickers bought new's table above, row for row; the one registered difference between the arms is itemized below.
What differs between the arms, one difference; the comparison is clean:
- paramWhat big funds hold, Keep stocks the funds: Bought new → Sold out of
Companion book. What all the followed firms bought comes from a companion run of the identical configuration on its own registered anchor schedule. Its results run through this paper's tables under its own name.
Everything else is held identical, so an out-of-sample gap between the arms is attributable to this one change.
Cost elements are wired into the circuit, the realised drag is reported per step in Appendix B.
Show the mathematics, 4 primitives, formulas and parity notes
3.1 Universe
The starting set of tickers, resolved point-in-time from the index change-log, so names delisted or removed later still compete on the dates they traded.
Before any math, you need a list of stocks. An index preset (S&P 500, Nasdaq-100, Dow 30) is reconstructed as it stood ON your anchor date by replaying the historical add/drop change-log backwards, so a 2018 backtest sees the 2018 membership, not today's winners.
Start from today's constituents and un-apply every membership change after the anchor t:
\mathcal{U}(t) = \mathcal{U}_{\text{now}} \;\ominus\; \{\text{adds after } t\} \;\oplus\; \{\text{drops after } t\}3.2 Sec Fund Holdings
What the well-known funds bought new, added to or sold out of, once their reports were public.
Each quarter the well-known funds report on Form 13F what they held at its end, due 45 days later. On the run date the card reads the last quarter whose reports were due, and only the reports already public that day. A stock counts for a fund when it holds shares now and held none the quarter before (bought new), holds more shares than before (added to), or held shares before and none now (sold out of). A fund counts once, whichever of its firm’s filers reported, its older ones included. It keeps the stocks at least so many funds moved; with Crowding, only those in the third of the list held by the fewest, or the most, of all 13F filers.
q(t)=\max\{q:\ \text{due}(q)\le t\},\qquad \text{due}(q)=q+45\ \text{days}c_i(t)=\big|\{g:\ \text{a manager of firm } g \text{ moved } i \text{ in } q(t),\ \text{its report public by } t\}\big|3.3 Portfolio Backtest
Replay the portfolio forward, rebalanced, point-in-time, with costs.
Holds the basket and rebalances on schedule, re-selecting and re-optimizing point-in-time at each rebalance (so it only ever uses information available then), and reports the equity curve, Sharpe, drawdown and trade stats, optionally net of cost and risk overlays.
E_t = E_{t-1}\big(1 + \mathbf w_{t}^{\top}\mathbf r_t - \text{costs}_t\big)\text{DD}_t = \frac{E_t}{\max_{\tau\le t}E_\tau} - 1, \qquad \text{MaxDD} = \min_t \text{DD}_t\text{charge}_t \;=\; \text{loan}_t \cdot \frac{\text{spread}}{252}, \qquad \text{loan}_t = \begin{cases}\max(0,\,-\text{cash}_t) & \text{institutional (netted)}\\ \max(0,\,\text{long MV}_t - E_t) & \text{retail (no netting)}\end{cases}\mathbf w_k = \{\, w_{k,i} : i \in \text{held} \,\}, \qquad \text{cash}_k = 1 - \textstyle\sum_{i \in \text{held}} w_{k,i}3.4 Transaction Cost
Charge for trading, slippage + commission on every turn.
Real trading isn't free. This deducts a cost proportional to how much you trade (turnover), in basis points, so the backtest reflects net, not gross, performance.
\text{cost}_t = \frac{\text{bps}}{10{,}000}\;\times\;\text{turnover}_t, \qquad \text{turnover}_t = \tfrac12\sum_i \lvert w_{i,t}-w_{i,t^-}\rvert4 Projection calibration, pooled across the walk
Every rebalance carried a Monte Carlo cone and a 95% VaR estimated before the segment it is scored against. Two questions, pooled over the whole study: did realized outcomes land inside the band as often as the band claims, and were VaR breaches as frequent as 5%?
This section is produced by the forward tester itself: every portfolio backtest fits the cone and the VaR estimate at each rebalance and scores them against the segment that followed. It does not require, and this circuit does not contain, a Monte Carlo primitive; that primitive is a separate, standalone analysis.
| Arm | Steps | Rebalances | In band | Coverage | Expected | VaR days | Breach rate | Expected |
|---|---|---|---|---|---|---|---|---|
| What the stock pickers bought | 20 | 95 | 73 / 80 | 91.2% ±3.16 | 90.0% | 4950 | 5.68% ±0.329 | 5.0% |
| What the stock pickers sold | 20 | 95 | 73 / 80 | 91.2% ±3.16 | 90.0% | 4950 | 5.68% ±0.329 | 5.0% |
| What all the followed firms bought (companion run) | 20 | 95 | 73 / 80 | 91.2% ±3.16 | 90.0% | 4782 | 5.71% ±0.336 | 5.0% |
± values are binomial standard errors on the estimate. A coverage figure below the expected band means the projection was over-confident; a breach rate above 5% means the same of the risk model. Both forecasts used only data prior to the segment scored.
5 Discussion
5.1 Interpretation
Every rule in this field has a lesson behind it. The investment trusts of the twenties were run for the people who managed them, and by the time Congress had them studied half were gone. Out of that came the law that still governs every fund sold to the public. Early in this century mutual funds were caught letting favoured clients trade after the bell, and since then every fund must have a compliance officer. Madoff brought surprise visits by an outside accountant to the managers who keep their clients' money themselves. And managers who act together on one company count as one group before the law and, once they hold more than a twentieth of it, must report as one. This is the rule against the quiet cartel.
The quarterly report of this study is such a rule too. It has a dull name, Form 13F, and Congress wrote it in the seventies. Any manager who decides over a hundred million dollars or more of listed American shares must file a list of them with the SEC, four times a year. Pension funds, insurers, banks and hedge funds all file. So does Berkshire Hathaway.
People usually read this list as the manager's portfolio, but it is one photograph of one part of it. It shows the shares held on the last day of the quarter. It does not show when they were bought, at what price, or whether they were sold again the next morning. It leaves out short positions, cash, ordinary bonds and shares listed outside the United States. A manager can hold a stock for ten weeks between two photographs and never appear with it.
Options are the best trap. The form asks for them by the value of the shares under them, and what was paid for the options is nowhere in it. A few summers ago headlines announced that Michael Burry, the investor from The Big Short, had bet more than a billion and a half dollars against the market. His report listed put options on two index funds, written down, as the form asks, at the value of the shares they covered. What he had paid for them was not in the filing. His firm is one of the firms on our list.
And a manager who does not want company can ask for privacy. The SEC may let a holding stay off the public list for a while, and the best known user of that rule is the most copied investor of all. Not long ago Berkshire Hathaway kept one purchase out of two quarterly reports while it was still buying. When the name came out, an insurer called Chubb, the share jumped.
What it meant: the report is a tool of the regulator. It was built so that the public can see what the big money holds, and it does that well. Nobody built it to be a shopping list.
People usually take a test like this as a test of the managers, but it is a test of the report. A manager's result comes from the whole portfolio, from how large each position is and from when it is opened and closed, and the quarterly list of new names carries none of that. Earlier research that copied one investor's whole reported portfolio, Berkshire Hathaway's, over thirty years found that it paid well. Following the newest names of many managers for a quarter at a time is a different thing.
So where does this story stop? The reports are worth reading. They are the only public view of what these managers hold, and Figure 3 shows that they move with the big events. As a ready-made stock list for a retail investor, read once a quarter and followed, they gave about what holding everything gave. What stays open is the faster follower who acts on the day a report comes out, the size of each position, and the single manager followed for years. These are different tests, and the cards to build them are in the lab.
5.2 Limitations
The 65 firms were chosen with today's knowledge of who became well known; a manager who failed early and was forgotten is not on the list, and we cannot size what that does to the baskets. The first reports come from 34 firms and the last from 65, so the early years rest on fewer managers. A share swapped for a new one counts as sold out and bought new: when Google became Alphabet in late 2015 the reports show 14 stock pickers buying Alphabet new in one quarter, and General Electric's reverse split in 2021 put it in both baskets at once. The basket acts on the first day of a quarter, six to seven weeks after the reports are due; a copy made on the due day itself was not tested. In the year from October 2021 the basket of what the stock pickers bought held only 31 different stocks, against about 106 in a usual year, because most of what they bought new that year was outside the S&P 500. That regular people moved the stocks the funds sold is an argument, not a measurement: the reports do not show who bought.
Try it yourself
The three baskets are built from cards anyone can open. On the card What big funds hold you can ask for three funds instead of two, for the stocks the funds added to, or for the funds that hold a hundred stocks or fewer, and run your own version. Every account can open the study's setup, look at each card, and replay any of its twenty years.
References
- U.S. Securities and Exchange Commission. Frequently Asked Questions About Form 13F. Division of Investment Management.
- U.S. Securities and Exchange Commission. Form 13F, Information Required of Institutional Investment Managers, with its instructions.
- U.S. Securities and Exchange Commission. Investment Trusts and Investment Companies: report of the Commission (1938 to 1940), the study behind the Investment Company Act of 1940.
- U.S. Securities and Exchange Commission (2003). Compliance Programs of Investment Companies and Investment Advisers. Final rule, Federal Register, 24 December 2003.
- U.S. Securities and Exchange Commission (2009). Custody of Funds or Securities of Clients by Investment Advisers. Final rule, 30 December 2009.
- Securities Exchange Act of 1934, Section 13(d)(3): persons acting as a group.
- SIFMA Insights (2021). Analyzing Off Exchange Trading: the share of retail investors in US equity volume.
- Martin, G. S., and Puthenpurackal, J. (2008). Imitation is the Sincerest Form of Flattery: Warren Buffett and Berkshire Hathaway. Working paper, SSRN.
- National Bureau of Economic Research. US Business Cycle Expansions and Contractions.
Appendix A Reproducibility in QuanterLab
Each step is backed by a frozen run report. The study is re-derivable from the ledger below.
| # | Commit | Report | Anchor | OOS window |
|---|---|---|---|---|
| 1 | 60ba22d3f5dd | 17250 | 2006-10-01 | 2006-10-02 → 2007-10-01 |
| 2 | 00d169f24637 | 17251 | 2007-10-01 | 2007-10-01 → 2008-09-30 |
| 3 | 39af1b2a8429 | 17252 | 2008-10-01 | 2008-10-01 → 2009-10-01 |
| 4 | 8abd74194c17 | 17253 | 2009-10-01 | 2009-10-01 → 2010-10-01 |
| 5 | 8b1a888f0d82 | 17254 | 2010-10-01 | 2010-10-01 → 2011-09-30 |
| 6 | 40e646d8dd96 | 17255 | 2011-10-01 | 2011-10-03 → 2012-09-28 |
| 7 | e7d20c475592 | 17256 | 2012-10-01 | 2012-10-01 → 2013-10-01 |
| 8 | 6faee5173340 | 17257 | 2013-10-01 | 2013-10-01 → 2014-10-01 |
| 9 | bcf1e60613b0 | 17258 | 2014-10-01 | 2014-10-01 → 2015-10-01 |
| 10 | c42af625f0d2 | 17259 | 2015-10-01 | 2015-10-01 → 2016-09-30 |
| 11 | 30181616a8f6 | 17260 | 2016-10-01 | 2016-10-03 → 2017-09-29 |
| 12 | 16f33dda81f8 | 17261 | 2017-10-01 | 2017-10-02 → 2018-10-01 |
| 13 | 1b5b18c8d7c1 | 17262 | 2018-10-01 | 2018-10-01 → 2019-10-01 |
| 14 | f4a1b1260efa | 17263 | 2019-10-01 | 2019-10-01 → 2020-09-30 |
| 15 | d8701a249779 | 17264 | 2020-10-01 | 2020-10-01 → 2021-10-01 |
| 16 | e6702d263c31 | 17265 | 2021-10-01 | 2021-10-01 → 2022-09-30 |
| 17 | 5b46aa33504d | 17266 | 2022-10-01 | 2022-10-03 → 2023-09-29 |
| 18 | 593019936614 | 17267 | 2023-10-01 | 2023-10-02 → 2024-09-30 |
| 19 | e73592dfe158 | 17268 | 2024-10-01 | 2024-10-01 → 2025-10-01 |
| 20 | 24463494a0e0 | 17269 | 2025-10-01 | 2025-10-01 → 2026-10-01 |
The methods the platform implements, for every study made on it, rest on these works.
- Gelman, A., & Loken, E. (2013). The garden of forking paths: Why multiple comparisons can be a problem, even when there is no “fishing expedition.” Working paper, Columbia University.
- Harvey, C. R., Liu, Y., & Zhu, H. (2016). … and the Cross-Section of Expected Returns. Review of Financial Studies, 29(1), 5–68. doi:10.1093/rfs/hhv059
- Lo, A. W. (2002). The Statistics of Sharpe Ratios. Financial Analysts Journal, 58(4), 36–52. doi:10.2469/faj.v58.n4.2453
Appendix A2 Registration record
What this record does and does not establish. Every window in this study is historical: the data existed before the study began, so this is sequential registration on past windows, not pre-registration in the clinical-trial sense, and no procedure could make it so. What the platform does enforce is order, each step's specification was frozen and hashed before that step was scored, and the walk cannot advance past a step that was never run or close one with a result registered for a different window. The two timestamp columns below are the evidence: read them together and each registration precedes its own run, and each run precedes the next registration. A study whose registrations all post-date its runs would show it here. Wall-clock spacing between registrations varies with the author's schedule and queue latency; the ordering, not the tempo, is the claim.
“A COMPARATIVE study: What at least two stock pickers bought new vs What at least two stock pickers sold out of, walked on the same registered out-of-sample windows. What at least two stock pickers bought new: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. What at least two stock pickers sold out of: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. The arms differ in: What big funds hold, Keep stocks the funds: Bought new → Sold out of. The contrast under test: whether What at least two stock pickers bought new generates better risk-adjusted returns than What at least two stock pickers sold out of over the identical out-of-sample windows.”
The same hypothesis was registered independently at every step, hashed before each step's out-of-sample window was scored:
| # | Anchor | Registered at (UTC) | Run completed (UTC) |
|---|---|---|---|
| 1 | 2006-10-01 | 2026-11-14 14:09:21 | 2026-11-14 14:11:58 |
| 2 | 2007-10-01 | 2026-11-14 14:11:58 | 2026-11-14 14:12:58 |
| 3 | 2008-10-01 | 2026-11-14 14:12:58 | 2026-11-14 14:14:46 |
| 4 | 2009-10-01 | 2026-11-14 14:14:47 | 2026-11-14 14:15:23 |
| 5 | 2010-10-01 | 2026-11-14 14:15:23 | 2026-11-14 14:16:11 |
| 6 | 2011-10-01 | 2026-11-14 14:16:11 | 2026-11-14 14:17:00 |
| 7 | 2012-10-01 | 2026-11-14 14:17:00 | 2026-11-14 14:17:48 |
| 8 | 2013-10-01 | 2026-11-14 14:17:48 | 2026-11-14 14:18:36 |
| 9 | 2014-10-01 | 2026-11-14 14:18:36 | 2026-11-14 14:19:37 |
| 10 | 2015-10-01 | 2026-11-14 14:19:37 | 2026-11-14 14:20:25 |
| 11 | 2016-10-01 | 2026-11-14 14:20:25 | 2026-11-14 14:21:14 |
| 12 | 2017-10-01 | 2026-11-14 14:21:14 | 2026-11-14 14:22:02 |
| 13 | 2018-10-01 | 2026-11-14 14:22:02 | 2026-11-14 14:22:50 |
| 14 | 2019-10-01 | 2026-11-14 14:22:50 | 2026-11-14 14:23:51 |
| 15 | 2020-10-01 | 2026-11-14 14:23:51 | 2026-11-14 14:24:39 |
| 16 | 2021-10-01 | 2026-11-14 14:24:39 | 2026-11-14 14:25:04 |
| 17 | 2022-10-01 | 2026-11-14 14:25:04 | 2026-11-14 14:25:28 |
| 18 | 2023-10-01 | 2026-11-14 14:25:28 | 2026-11-14 14:25:52 |
| 19 | 2024-10-01 | 2026-11-14 14:25:52 | 2026-11-14 14:26:29 |
| 20 | 2025-10-01 | 2026-11-14 14:26:29 | 2026-11-14 14:26:41 |
The companion comparison
This paper reads a second registered study beside its own. Its registration is printed here from its own record, in the same form as the table above: the hypothesis as it was registered, the day it was first locked, the time each window was registered and run, and what each window returned.
What all the followed firms bought
Its hypothesis was first locked on 14 November 2026, before its first window was run that day.
The same hypothesis was registered again, unchanged, at each of its 20 windows:
“A COMPARATIVE study: Bought new by at least two stock pickers vs Bought new by at least two of all the followed firms, walked on the same registered out-of-sample windows. Bought new by at least two stock pickers: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. Bought new by at least two of all the followed firms: S&P 500, rebalanced quarterly across the selected basket, and run out-of-sample from the anchor: anything the design estimates from history, where it estimates at all, is re-estimated at each anchor from pre-anchor data only, and the walk advances through registered out-of-sample windows; its disposition is the realized forward path versus the benchmark. The arms differ in: What big funds hold, Which funds: Holding 500 stocks or fewer → All of them. The contrast under test: whether Bought new by at least two stock pickers generates better risk-adjusted returns than Bought new by at least two of all the followed firms over the identical out-of-sample windows.”
| # | Anchor | Registered at (UTC) | Run completed (UTC) |
|---|---|---|---|
| 1 | 2006-10-01 | 2026-11-14 14:26:55 | 2026-11-14 14:27:31 |
| 2 | 2007-10-01 | 2026-11-14 14:27:31 | 2026-11-14 14:28:08 |
| 3 | 2008-10-01 | 2026-11-14 14:28:08 | 2026-11-14 14:28:32 |
| 4 | 2009-10-01 | 2026-11-14 14:28:32 | 2026-11-14 14:29:08 |
| 5 | 2010-10-01 | 2026-11-14 14:29:08 | 2026-11-14 14:29:33 |
| 6 | 2011-10-01 | 2026-11-14 14:29:33 | 2026-11-14 14:29:57 |
| 7 | 2012-10-01 | 2026-11-14 14:29:57 | 2026-11-14 14:30:21 |
| 8 | 2013-10-01 | 2026-11-14 14:30:22 | 2026-11-14 14:30:46 |
| 9 | 2014-10-01 | 2026-11-14 14:30:46 | 2026-11-14 14:31:22 |
| 10 | 2015-10-01 | 2026-11-14 14:31:22 | 2026-11-14 14:31:47 |
| 11 | 2016-10-01 | 2026-11-14 14:31:47 | 2026-11-14 14:32:35 |
| 12 | 2017-10-01 | 2026-11-14 14:32:35 | 2026-11-14 14:33:12 |
| 13 | 2018-10-01 | 2026-11-14 14:33:13 | 2026-11-14 14:33:49 |
| 14 | 2019-10-01 | 2026-11-14 14:33:49 | 2026-11-14 14:34:38 |
| 15 | 2020-10-01 | 2026-11-14 14:34:38 | 2026-11-14 14:35:51 |
| 16 | 2021-10-01 | 2026-11-14 14:35:51 | 2026-11-14 14:36:39 |
| 17 | 2022-10-01 | 2026-11-14 14:36:39 | 2026-11-14 14:37:28 |
| 18 | 2023-10-01 | 2026-11-14 14:37:28 | 2026-11-14 14:38:16 |
| 19 | 2024-10-01 | 2026-11-14 14:38:16 | 2026-11-14 14:39:05 |
| 20 | 2025-10-01 | 2026-11-14 14:39:05 | 2026-11-14 14:40:05 |
| # | Anchor | Bought new by at least two stock pickers | Bought new by at least two of all the followed firms |
|---|---|---|---|
| 1 | 2006-10-01 | +13.8% | +17.8% |
| 2 | 2007-10-01 | -27.7% | -24.6% |
| 3 | 2008-10-01 | -5.6% | -4.0% |
| 4 | 2009-10-01 | +9.8% | +18.7% |
| 5 | 2010-10-01 | -1.2% | -3.3% |
| 6 | 2011-10-01 | +33.4% | +30.5% |
| 7 | 2012-10-01 | +39.0% | +34.5% |
| 8 | 2013-10-01 | +22.4% | +14.8% |
| 9 | 2014-10-01 | +1.2% | +1.0% |
| 10 | 2015-10-01 | +15.2% | +16.3% |
| 11 | 2016-10-01 | +22.4% | +15.2% |
| 12 | 2017-10-01 | +16.1% | +12.4% |
| 13 | 2018-10-01 | -6.7% | +0.0% |
| 14 | 2019-10-01 | +10.5% | +6.9% |
| 15 | 2020-10-01 | +30.7% | +33.8% |
| 16 | 2021-10-01 | -12.7% | -10.6% |
| 17 | 2022-10-01 | +20.3% | +12.1% |
| 18 | 2023-10-01 | +32.9% | +33.9% |
| 19 | 2024-10-01 | +10.2% | +7.5% |
| 20 | 2025-10-01 | +9.9% | +7.8% |
Appendix B Per-step diagnostics
Realized in the projection tables below is the risk engine scoring its own forecast: the buy-and-hold return of the segment that followed each rebalance, on the same gross basis the cone was projected on. It is deliberately not the charged, calendar-window total return the study’s tables print, so the two will not reconcile line by line; the cone and its outcome share one basis, which is what a calibration test requires. Each row names its segment’s span so a boundary session is visible.
Names held is the union across the window: the count of distinct instruments the book touched between the window’s first and last session, not the number it held at one time. A book that rotates monthly touches more names than it holds.
What each step's run actually did beyond its return: the portfolio book's rebalancing and cost drag. Harvested from the frozen run reports, present where the circuit produced them. Cost drag is the gap between the step's return before and after its trading costs, in percentage points of the step's starting capital, so on a book that trades every session and compounds it can exceed the step's own net return.
Open the full per-step grid (20 steps: every rebalance, per window)
Step 1 · 2006-10-02 → 2007-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 96 names held · selection: reselect · 0.0% in cash · turnover 8.9× · cost drag 1.51% · 11 names dropped at load (107 selected, 96 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 7.32% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2006-10-01 → 2007-01-01 | -6.7083% | 4.0583% | 16.1411% | 8.9029% | yes | 1.3561% | 1 / 62 |
| 2007-01-01 → 2007-04-01 | -7.4841% | 3.6038% | 14.8255% | 2.03% | yes | 1.4017% | 3 / 60 |
| 2007-04-01 → 2007-07-01 | -8.9493% | 2.4882% | 15.4417% | 4.8757% | yes | 1.4367% | 1 / 62 |
| 2007-07-01 → 2007-10-01 | -5.299% | 4.7561% | 15.9467% | -3.3248% | yes | 1.1145% | 13 / 62 |
| 2007-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 65 names held · selection: reselect · 0.0% in cash · turnover 9.5× · cost drag 1.62% · 9 names dropped at load (74 selected, 65 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.91% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2006-10-01 → 2007-01-01 | -7.8554% | 2.1531% | 13.3165% | 6.9836% | yes | 1.2508% | 1 / 62 |
| 2007-01-01 → 2007-04-01 | -15.1922% | 2.6229% | 22.0333% | -0.0714% | yes | 2.1552% | 3 / 60 |
| 2007-04-01 → 2007-07-01 | -8.7044% | 3.0673% | 16.4389% | 3.446% | yes | 1.4554% | 2 / 62 |
| 2007-07-01 → 2007-10-01 | -5.858% | 4.3438% | 15.7203% | -0.2223% | yes | 1.2298% | 11 / 62 |
| 2007-10-01 | no segment follows this rebalance, not scored | ||||||
Step 2 · 2007-10-01 → 2008-09-30
What the stock pickers bought
Portfolio book, rebalanced quarterly · 4 constructions · 81 names held · selection: reselect · 0.0% in cash · turnover 5.5× · cost drag 0.94% · 11 names dropped at load (92 selected, 81 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 16.87% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2007-10-01 → 2008-01-01 | -9.0783% | 3.2703% | 15.9905% | -10.2325% | no | 1.4282% | 12 / 63 |
| 2008-01-01 → 2008-04-01 | -11.9422% | 2.0201% | 16.6156% | -3.3413% | yes | 1.8255% | 14 / 60 |
| 2008-04-01 → 2008-07-01 | -15.4669% | -0.6272% | 15.1688% | -9.5581% | yes | 1.9822% | 6 / 63 |
| 2008-07-01 → window end | -18.4145% | -0.6505% | 18.9046% | -10.5737% | yes | 2.3127% | 10 / 63 |
What the stock pickers sold
Portfolio book, rebalanced quarterly · 4 constructions · 61 names held · selection: reselect · 0.0% in cash · turnover 5.6× · cost drag 0.95% · 6 names dropped at load (67 selected, 61 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 15.66% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2007-10-01 → 2008-01-01 | -7.951% | 3.1403% | 14.418% | -6.419% | yes | 1.3048% | 10 / 63 |
| 2008-01-01 → 2008-04-01 | -10.1515% | 2.6926% | 15.9471% | -10.059% | yes | 1.6578% | 13 / 60 |
| 2008-04-01 → 2008-07-01 | -18.4482% | -0.495% | 19.3058% | -16.8533% | yes | 2.3805% | 7 / 63 |
| 2008-07-01 → window end | -16.4249% | -0.941% | 15.6705% | 7.15% | yes | 2.2076% | 9 / 63 |
Step 3 · 2008-10-01 → 2009-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 115 names held · selection: reselect · 0.0% in cash · turnover 6.7× · cost drag 1.15% · 18 names dropped at load (133 selected, 115 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 12.5% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2008-10-01 → 2009-01-01 | -21.2732% | -0.1508% | 24.0205% | -23.0643% | no | 2.7576% | 20 / 63 |
| 2009-01-01 → 2009-04-01 | -32.0157% | -4.635% | 29.6954% | -13.5293% | yes | 3.5702% | 10 / 60 |
| 2009-04-01 → 2009-07-01 | -30.9292% | -5.5326% | 29.4376% | 19.3651% | yes | 3.7617% | 1 / 62 |
| 2009-07-01 → 2009-10-01 | -34.3364% | -3.0623% | 38.2903% | 18.1157% | yes | 4.2495% | 0 / 63 |
| 2009-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 113 names held · selection: reselect · 0.0% in cash · turnover 6.7× · cost drag 1.14% · 9 names dropped at load (122 selected, 113 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 12.1% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2008-10-01 → 2009-01-01 | -25.7136% | -2.7606% | 24.3075% | -29.1974% | no | 3.2668% | 18 / 63 |
| 2009-01-01 → 2009-04-01 | -30.0266% | -4.3306% | 27.1121% | -4.6185% | yes | 3.3524% | 11 / 60 |
| 2009-04-01 → 2009-07-01 | -36.6884% | -7.1418% | 36.4974% | 24.2384% | yes | 4.647% | 1 / 62 |
| 2009-07-01 → 2009-10-01 | -31.8926% | -1.8523% | 36.9677% | 11.8816% | yes | 4.3896% | 0 / 63 |
| 2009-10-01 | no segment follows this rebalance, not scored | ||||||
Step 4 · 2009-10-01 → 2010-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 102 names held · selection: reselect · 0.0% in cash · turnover 8.8× · cost drag 1.49% · 13 names dropped at load (115 selected, 102 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.4% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2009-10-01 → 2010-01-01 | -28.526% | 0.1069% | 36.1192% | 7.3139% | yes | 3.5191% | 0 / 63 |
| 2010-01-01 → 2010-04-01 | -27.1773% | -0.2755% | 32.6929% | 6.0145% | yes | 3.649% | 0 / 60 |
| 2010-04-01 → 2010-07-01 | -25.4801% | 0.9301% | 36.9416% | -15.5556% | yes | 3.5952% | 1 / 62 |
| 2010-07-01 → 2010-10-01 | -28.5242% | 0.3949% | 36.8659% | 11.813% | yes | 3.686% | 0 / 63 |
| 2010-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 79 names held · selection: reselect · 0.0% in cash · turnover 8.8× · cost drag 1.5% · 12 names dropped at load (91 selected, 79 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.0% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2009-10-01 → 2010-01-01 | -31.2635% | -1.642% | 36.381% | 11.4625% | yes | 3.7229% | 0 / 63 |
| 2010-01-01 → 2010-04-01 | -33.7202% | -1.0774% | 42.3315% | 8.3858% | yes | 4.5566% | 0 / 60 |
| 2010-04-01 → 2010-07-01 | -26.6338% | 0.703% | 38.4805% | -17.3848% | yes | 3.8066% | 0 / 62 |
| 2010-07-01 → 2010-10-01 | -32.1384% | -1.2835% | 38.9471% | 3.8349% | yes | 4.3356% | 0 / 63 |
| 2010-10-01 | no segment follows this rebalance, not scored | ||||||
Step 5 · 2010-10-01 → 2011-09-30
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 85 names held · selection: reselect · 0.0% in cash · turnover 7.0× · cost drag 1.19% · 9 names dropped at load (94 selected, 85 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.22% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2010-10-01 → 2011-01-01 | -32.6458% | 0.361% | 44.3916% | 8.1246% | yes | 4.4733% | 0 / 63 |
| 2011-01-01 → 2011-04-01 | -13.6126% | 7.3773% | 36.1508% | 5.1769% | yes | 2.5926% | 0 / 61 |
| 2011-04-01 → 2011-07-01 | -12.6104% | 7.5709% | 32.5729% | -1.6291% | yes | 2.478% | 0 / 62 |
| 2011-07-01 → 2011-10-01 | -9.05% | 5.8455% | 21.5494% | -16.3896% | no | 1.7893% | 13 / 63 |
| 2011-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 92 names held · selection: reselect · 0.0% in cash · turnover 7.3× · cost drag 1.24% · 8 names dropped at load (100 selected, 92 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.62% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2010-10-01 → 2011-01-01 | -26.2845% | 1.5694% | 36.0604% | 10.8612% | yes | 3.7207% | 0 / 63 |
| 2011-01-01 → 2011-04-01 | -21.4075% | 2.8111% | 37.8404% | 2.2007% | yes | 3.1875% | 0 / 61 |
| 2011-04-01 → 2011-07-01 | -12.0011% | 5.9829% | 27.7804% | -0.4788% | yes | 2.1666% | 1 / 62 |
| 2011-07-01 → 2011-10-01 | -13.2947% | 6.1801% | 27.7338% | -22.1109% | no | 2.224% | 13 / 63 |
| 2011-10-01 | no segment follows this rebalance, not scored | ||||||
Step 6 · 2011-10-03 → 2012-09-28
What the stock pickers bought
Portfolio book, rebalanced quarterly · 4 constructions · 108 names held · selection: reselect · 0.0% in cash · turnover 7.7× · cost drag 1.31% · 5 names dropped at load (113 selected, 108 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 3.24% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2011-10-01 → 2012-01-01 | -18.4596% | 1.5421% | 26.6115% | 4.4478% | yes | 2.8312% | 8 / 62 |
| 2012-01-01 → 2012-04-01 | -16.2374% | 1.3875% | 24.8847% | 15.7194% | yes | 2.6636% | 0 / 61 |
| 2012-04-01 → 2012-07-01 | -16.7832% | 3.4268% | 28.7076% | -9.1155% | yes | 2.8667% | 0 / 62 |
| 2012-07-01 → window end | -15.3147% | 1.8446% | 22.6122% | 6.8361% | yes | 2.2267% | 0 / 62 |
What the stock pickers sold
Portfolio book, rebalanced quarterly · 4 constructions · 112 names held · selection: reselect · 0.0% in cash · turnover 7.8× · cost drag 1.32% · 6 names dropped at load (118 selected, 112 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.83% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2011-10-01 → 2012-01-01 | -13.1242% | 1.7649% | 19.3153% | 13.389% | yes | 1.8949% | 5 / 62 |
| 2012-01-01 → 2012-04-01 | -16.0654% | 1.7417% | 25.5176% | 18.7887% | yes | 2.6513% | 0 / 61 |
| 2012-04-01 → 2012-07-01 | -14.7623% | 2.8181% | 24.1598% | -5.3334% | yes | 2.4881% | 2 / 62 |
| 2012-07-01 → window end | -19.1628% | -0.1493% | 23.4878% | 5.8837% | yes | 2.5914% | 0 / 62 |
Step 7 · 2012-10-01 → 2013-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 109 names held · selection: reselect · 0.0% in cash · turnover 9.6× · cost drag 1.63% · 6 names dropped at load (115 selected, 109 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.22% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2012-10-01 → 2013-01-01 | -12.3346% | 4.1449% | 25.6882% | 8.0081% | yes | 2.2396% | 0 / 61 |
| 2013-01-01 → 2013-04-01 | -12.8628% | 3.329% | 19.5931% | 9.4828% | yes | 1.9087% | 1 / 59 |
| 2013-04-01 → 2013-07-01 | -15.6023% | 2.665% | 22.7539% | 5.3817% | yes | 2.2951% | 2 / 63 |
| 2013-07-01 → 2013-10-01 | -14.2274% | 5.6391% | 27.7464% | 7.9607% | yes | 2.3306% | 0 / 63 |
| 2013-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 114 names held · selection: reselect · 0.0% in cash · turnover 10.0× · cost drag 1.7% · 5 names dropped at load (119 selected, 114 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.63% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2012-10-01 → 2013-01-01 | -13.7954% | 3.0871% | 25.3106% | 3.0299% | yes | 2.2005% | 1 / 61 |
| 2013-01-01 → 2013-04-01 | -12.3998% | 2.7618% | 17.8396% | 16.991% | yes | 1.8928% | 0 / 59 |
| 2013-04-01 → 2013-07-01 | -12.3767% | 4.2273% | 22.101% | 2.6664% | yes | 2.0178% | 2 / 63 |
| 2013-07-01 → 2013-10-01 | -15.8648% | 2.5464% | 22.8314% | 8.3728% | yes | 2.1571% | 1 / 63 |
| 2013-10-01 | no segment follows this rebalance, not scored | ||||||
Step 8 · 2013-10-01 → 2014-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 99 names held · selection: reselect · 0.0% in cash · turnover 9.3× · cost drag 1.59% · 5 names dropped at load (104 selected, 99 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.82% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2013-10-01 → 2014-01-01 | -15.4597% | 6.677% | 31.8865% | 13.0197% | yes | 2.5664% | 0 / 63 |
| 2014-01-01 → 2014-04-01 | -7.9875% | 5.9712% | 20.4808% | 4.5267% | yes | 1.5519% | 2 / 60 |
| 2014-04-01 → 2014-07-01 | -5.9799% | 5.5186% | 18.5029% | 3.9614% | yes | 1.4406% | 3 / 62 |
| 2014-07-01 → 2014-10-01 | -7.2604% | 5.7297% | 19.1584% | 1.0718% | yes | 1.5678% | 2 / 63 |
| 2014-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 106 names held · selection: reselect · 0.0% in cash · turnover 9.0× · cost drag 1.54% · 5 names dropped at load (111 selected, 106 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 4.84% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2013-10-01 → 2014-01-01 | -5.2253% | 7.452% | 20.4882% | 9.3116% | yes | 1.458% | 1 / 63 |
| 2014-01-01 → 2014-04-01 | -6.648% | 5.6325% | 18.1847% | 4.0426% | yes | 1.3834% | 4 / 60 |
| 2014-04-01 → 2014-07-01 | -6.2511% | 6.5608% | 21.2139% | 0.7938% | yes | 1.475% | 4 / 62 |
| 2014-07-01 → 2014-10-01 | -4.813% | 7.4848% | 20.0822% | -0.544% | yes | 1.3565% | 3 / 63 |
| 2014-10-01 | no segment follows this rebalance, not scored | ||||||
Step 9 · 2014-10-01 → 2015-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 117 names held · selection: reselect · 0.0% in cash · turnover 8.5× · cost drag 1.44% · 5 names dropped at load (122 selected, 117 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.87% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2014-10-01 → 2015-01-01 | -5.0382% | 6.7917% | 18.8625% | 1.9325% | yes | 1.2664% | 8 / 63 |
| 2015-01-01 → 2015-04-01 | -4.7385% | 6.8103% | 18.5121% | 2.3113% | yes | 1.3487% | 6 / 60 |
| 2015-04-01 → 2015-07-01 | -6.3969% | 5.125% | 18.1448% | 4.4744% | yes | 1.5242% | 1 / 62 |
| 2015-07-01 → 2015-10-01 | -6.9747% | 5.3536% | 18.0178% | -8.9475% | no | 1.5503% | 7 / 63 |
| 2015-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 112 names held · selection: reselect · 0.0% in cash · turnover 8.6× · cost drag 1.45% · 6 names dropped at load (118 selected, 112 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 9.27% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2014-10-01 → 2015-01-01 | -5.03% | 6.5788% | 18.4003% | 3.1433% | yes | 1.3162% | 7 / 63 |
| 2015-01-01 → 2015-04-01 | -7.017% | 4.9597% | 17.1731% | 3.4103% | yes | 1.583% | 4 / 60 |
| 2015-04-01 → 2015-07-01 | -6.4339% | 4.5628% | 16.9274% | 2.837% | yes | 1.5602% | 1 / 62 |
| 2015-07-01 → 2015-10-01 | -6.8299% | 4.315% | 15.639% | -10.1418% | no | 1.3519% | 11 / 63 |
| 2015-10-01 | no segment follows this rebalance, not scored | ||||||
Step 10 · 2015-10-01 → 2016-09-30
What the stock pickers bought
Portfolio book, rebalanced quarterly · 4 constructions · 107 names held · selection: reselect · 0.0% in cash · turnover 5.9× · cost drag 1.0% · 5 names dropped at load (112 selected, 107 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.02% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2015-10-01 → 2016-01-01 | -10.5712% | 3.3039% | 17.8284% | 4.0358% | yes | 1.7257% | 4 / 63 |
| 2016-01-01 → 2016-04-01 | -8.5439% | 4.2943% | 17.5141% | 0.817% | yes | 1.5475% | 7 / 60 |
| 2016-04-01 → 2016-07-01 | -14.145% | 0.8367% | 16.7701% | 6.6934% | yes | 2.0255% | 3 / 63 |
| 2016-07-01 → window end | -9.4087% | 4.392% | 18.8053% | 3.1426% | yes | 1.5457% | 1 / 63 |
What the stock pickers sold
Portfolio book, rebalanced quarterly · 4 constructions · 105 names held · selection: reselect · 0.0% in cash · turnover 6.8× · cost drag 1.15% · 4 names dropped at load (109 selected, 105 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.22% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2015-10-01 → 2016-01-01 | -8.9455% | 3.3506% | 16.0083% | 9.1439% | yes | 1.5336% | 1 / 63 |
| 2016-01-01 → 2016-04-01 | -11.0865% | 2.251% | 16.0954% | 0.0307% | yes | 1.79% | 9 / 60 |
| 2016-04-01 → 2016-07-01 | -10.3564% | 3.2554% | 17.4654% | 0.1018% | yes | 1.7638% | 2 / 63 |
| 2016-07-01 → window end | -15.1052% | -0.6689% | 14.6291% | 8.781% | yes | 1.8273% | 1 / 63 |
Step 11 · 2016-10-03 → 2017-09-29
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 121 names held · selection: reselect · 0.0% in cash · turnover 6.6× · cost drag 1.12% · 1 name dropped at load (122 selected, 121 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.02% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2016-10-01 → 2017-01-01 | -10.4277% | 2.378% | 17.1054% | 4.1738% | yes | 1.6531% | 1 / 62 |
| 2017-01-01 → 2017-04-01 | -10.1393% | 2.3544% | 17.9825% | 4.7915% | yes | 1.5668% | 1 / 61 |
| 2017-04-01 → 2017-07-01 | -10.2869% | 2.1868% | 16.4829% | 5.1489% | yes | 1.6015% | 1 / 62 |
| 2017-07-01 → 2017-10-01 | -9.2755% | 2.925% | 16.8519% | 5.2065% | yes | 1.4753% | 2 / 62 |
| 2017-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 123 names held · selection: reselect · 0.0% in cash · turnover 6.7× · cost drag 1.14% · 1 name dropped at load (124 selected, 123 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.81% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2016-10-01 → 2017-01-01 | -10.0218% | 2.6249% | 17.1386% | 4.084% | yes | 1.5374% | 0 / 62 |
| 2017-01-01 → 2017-04-01 | -9.5097% | 2.1209% | 16.5287% | 2.5123% | yes | 1.5383% | 0 / 61 |
| 2017-04-01 → 2017-07-01 | -10.2489% | 2.3698% | 16.852% | 3.3669% | yes | 1.6062% | 1 / 62 |
| 2017-07-01 → 2017-10-01 | -9.8254% | 2.4875% | 16.5682% | 2.8126% | yes | 1.651% | 1 / 62 |
| 2017-10-01 | no segment follows this rebalance, not scored | ||||||
Step 12 · 2017-10-02 → 2018-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 170 names held · selection: reselect · 0.0% in cash · turnover 8.5× · cost drag 1.45% · 1 name dropped at load (171 selected, 170 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.67% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2017-10-01 → 2018-01-01 | -7.5715% | 2.1001% | 12.8488% | 6.5154% | yes | 1.1661% | 1 / 62 |
| 2018-01-01 → 2018-04-01 | -8.3039% | 2.4333% | 13.2746% | -2.6266% | yes | 1.3104% | 8 / 60 |
| 2018-04-01 → 2018-07-01 | -6.2825% | 4.0511% | 14.4669% | 7.0265% | yes | 1.0339% | 5 / 63 |
| 2018-07-01 → 2018-10-01 | -6.3584% | 3.8599% | 15.2626% | 5.4745% | yes | 1.0848% | 0 / 62 |
| 2018-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 156 names held · selection: reselect · 0.0% in cash · turnover 8.5× · cost drag 1.45% · 3 names dropped at load (159 selected, 156 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 5.26% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2017-10-01 → 2018-01-01 | -9.1448% | 2.9341% | 16.7035% | 4.4802% | yes | 1.586% | 0 / 62 |
| 2018-01-01 → 2018-04-01 | -7.2448% | 3.9359% | 15.2581% | -1.7357% | yes | 1.3539% | 9 / 60 |
| 2018-04-01 → 2018-07-01 | -6.3423% | 4.6307% | 15.7567% | 6.9632% | yes | 1.1267% | 4 / 63 |
| 2018-07-01 → 2018-10-01 | -6.0727% | 3.0445% | 13.1076% | 7.2821% | yes | 0.9722% | 0 / 62 |
| 2018-10-01 | no segment follows this rebalance, not scored | ||||||
Step 13 · 2018-10-01 → 2019-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 123 names held · selection: reselect · 0.0% in cash · turnover 7.4× · cost drag 1.27% · 1 name dropped at load (124 selected, 123 held across the window), weights renormalised onto the rest
Projection accuracy, realized outcome fell inside the P5–P95 cone in 75.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 10.53% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2018-10-01 → 2019-01-01 | -5.6709% | 3.8481% | 14.3915% | -17.7819% | no | 1.0275% | 17 / 62 |
| 2019-01-01 → 2019-04-01 | -8.852% | 2.0408% | 13.0619% | 10.5175% | yes | 1.3181% | 3 / 60 |
| 2019-04-01 → 2019-07-01 | -8.7775% | 3.9127% | 18.4581% | 2.404% | yes | 1.6903% | 3 / 62 |
| 2019-07-01 → 2019-10-01 | -10.0308% | 3.3553% | 17.2944% | -1.5452% | yes | 1.7312% | 3 / 63 |
| 2019-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 134 names held · selection: reselect · 0.0% in cash · turnover 7.9× · cost drag 1.35%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 9.72% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2018-10-01 → 2019-01-01 | -5.6292% | 3.7575% | 14.1407% | -14.5372% | no | 1.0152% | 16 / 62 |
| 2019-01-01 → 2019-04-01 | -9.3489% | 2.07% | 13.6867% | 16.7995% | no | 1.5302% | 3 / 60 |
| 2019-04-01 → 2019-07-01 | -7.8833% | 2.7165% | 14.6086% | 3.7202% | yes | 1.4351% | 2 / 62 |
| 2019-07-01 → 2019-10-01 | -10.4173% | 2.4939% | 15.8863% | -0.3852% | yes | 1.7488% | 3 / 63 |
| 2019-10-01 | no segment follows this rebalance, not scored | ||||||
Step 14 · 2019-10-01 → 2020-09-30
What the stock pickers bought
Portfolio book, rebalanced quarterly · 4 constructions · 188 names held · selection: reselect · 0.0% in cash · turnover 6.2× · cost drag 1.05%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 8.84% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2019-10-01 → 2020-01-01 | -10.4963% | 2.2423% | 15.4358% | 8.219% | yes | 1.7028% | 0 / 63 |
| 2020-01-01 → 2020-04-01 | -8.8697% | 2.5759% | 16.716% | -25.5179% | no | 1.737% | 15 / 61 |
| 2020-04-01 → 2020-07-01 | -22.8829% | -3.3826% | 21.2073% | 33.8794% | no | 2.5542% | 7 / 62 |
| 2020-07-01 → window end | -18.2271% | 2.6519% | 26.3121% | 7.3828% | yes | 2.2813% | 0 / 63 |
What the stock pickers sold
Portfolio book, rebalanced quarterly · 4 constructions · 162 names held · selection: reselect · 0.0% in cash · turnover 6.5× · cost drag 1.1%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 50.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 10.04% of 249 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2019-10-01 → 2020-01-01 | -9.2756% | 3.261% | 16.2003% | 10.7208% | yes | 1.5618% | 1 / 63 |
| 2020-01-01 → 2020-04-01 | -8.5241% | 2.0891% | 15.084% | -22.6873% | no | 1.5915% | 15 / 61 |
| 2020-04-01 → 2020-07-01 | -21.2974% | -2.2814% | 21.4818% | 30.3453% | no | 2.3169% | 8 / 62 |
| 2020-07-01 → window end | -24.0573% | 0.1047% | 28.7889% | 6.0274% | yes | 2.9246% | 1 / 63 |
Step 15 · 2020-10-01 → 2021-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 108 names held · selection: reselect · 0.0% in cash · turnover 9.9× · cost drag 1.68%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 0.81% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2020-10-01 → 2021-01-01 | -21.9102% | 2.219% | 30.6745% | 22.8267% | yes | 2.6805% | 1 / 63 |
| 2021-01-01 → 2021-04-01 | -16.6751% | 5.2913% | 30.2311% | 6.1325% | yes | 2.4304% | 1 / 60 |
| 2021-04-01 → 2021-07-01 | -17.3761% | 4.3807% | 32.0459% | 4.0741% | yes | 2.6863% | 0 / 62 |
| 2021-07-01 → 2021-10-01 | -19.0257% | 4.4072% | 31.6472% | -3.982% | yes | 2.5472% | 0 / 63 |
| 2021-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 101 names held · selection: reselect · 0.0% in cash · turnover 10.5× · cost drag 1.78%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.61% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2020-10-01 → 2021-01-01 | -21.7664% | 1.3042% | 28.2321% | 18.4826% | yes | 2.5361% | 2 / 63 |
| 2021-01-01 → 2021-04-01 | -19.0989% | 3.5634% | 29.6126% | 8.1347% | yes | 2.3581% | 1 / 60 |
| 2021-04-01 → 2021-07-01 | -16.9709% | 5.4415% | 34.09% | 3.4342% | yes | 2.5027% | 1 / 62 |
| 2021-07-01 → 2021-10-01 | -18.9612% | 6.6479% | 37.0027% | -3.5528% | yes | 2.7589% | 0 / 63 |
| 2021-10-01 | no segment follows this rebalance, not scored | ||||||
Step 16 · 2021-10-01 → 2022-09-30
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 31 names held · selection: reselect · 0.0% in cash · turnover 6.4× · cost drag 1.09%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 4.44% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2021-10-01 → 2022-01-01 | -15.3153% | 8.6424% | 36.3591% | -0.3724% | yes | 2.3633% | 2 / 63 |
| 2022-01-01 → 2022-04-01 | -13.6535% | 7.6277% | 36.8865% | -2.9164% | yes | 2.2738% | 1 / 61 |
| 2022-04-01 → 2022-07-01 | -17.6758% | 2.9895% | 31.5105% | -13.1321% | yes | 2.5335% | 6 / 61 |
| 2022-07-01 → 2022-10-01 | -16.9036% | 4.7234% | 29.323% | 2.4415% | yes | 2.7914% | 2 / 63 |
| 2022-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 54 names held · selection: reselect · 0.0% in cash · turnover 5.8× · cost drag 0.98%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 7.26% of 248 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2021-10-01 → 2022-01-01 | -17.127% | 4.9557% | 30.1912% | -1.6751% | yes | 2.4454% | 1 / 63 |
| 2022-01-01 → 2022-04-01 | -17.9837% | 3.6478% | 33.8211% | -5.2447% | yes | 2.4965% | 4 / 61 |
| 2022-04-01 → 2022-07-01 | -17.9473% | 4.4434% | 35.9125% | -16.0453% | yes | 2.5352% | 10 / 61 |
| 2022-07-01 → 2022-10-01 | -13.9589% | 4.8729% | 25.622% | -2.9394% | yes | 2.3344% | 3 / 63 |
| 2022-10-01 | no segment follows this rebalance, not scored | ||||||
Step 17 · 2022-10-03 → 2023-09-29
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 57 names held · selection: reselect · 0.0% in cash · turnover 6.6× · cost drag 1.13%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 1.63% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2022-10-01 → 2023-01-01 | -19.694% | 0.788% | 26.661% | -2.2119% | yes | 2.9805% | 4 / 62 |
| 2023-01-01 → 2023-04-01 | -16.9075% | 0.771% | 24.3876% | 11.9146% | yes | 2.642% | 0 / 61 |
| 2023-04-01 → 2023-07-01 | -19.1302% | -0.8311% | 23.9003% | 10.2588% | yes | 2.654% | 0 / 61 |
| 2023-07-01 → 2023-10-01 | -18.171% | -0.3397% | 21.5164% | -1.2619% | yes | 2.4072% | 0 / 62 |
| 2023-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 50 names held · selection: reselect · 0.0% in cash · turnover 7.7× · cost drag 1.31%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.03% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2022-10-01 → 2023-01-01 | -18.394% | 1.8858% | 27.3693% | 4.2094% | yes | 2.9461% | 2 / 62 |
| 2023-01-01 → 2023-04-01 | -15.6232% | 1.358% | 23.8174% | 13.1798% | yes | 2.3094% | 2 / 61 |
| 2023-04-01 → 2023-07-01 | -16.9067% | 0.6518% | 24.0785% | 10.6648% | yes | 2.5753% | 0 / 61 |
| 2023-07-01 → 2023-10-01 | -17.1844% | 0.2062% | 21.3831% | -1.6178% | yes | 2.3354% | 1 / 62 |
| 2023-10-01 | no segment follows this rebalance, not scored | ||||||
Step 18 · 2023-10-02 → 2024-09-30
What the stock pickers bought
Portfolio book, rebalanced quarterly · 4 constructions · 96 names held · selection: reselect · 0.0% in cash · turnover 7.5× · cost drag 1.28%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 3.64% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2023-10-01 → 2024-01-01 | -16.7328% | -0.3554% | 19.3676% | 14.3% | yes | 2.0981% | 1 / 62 |
| 2024-01-01 → 2024-04-01 | -14.3485% | 1.3079% | 18.0002% | 11.5032% | yes | 1.8903% | 0 / 60 |
| 2024-04-01 → 2024-07-01 | -13.596% | 1.6684% | 19.7428% | -1.5478% | yes | 1.8631% | 1 / 62 |
| 2024-07-01 → window end | -11.5039% | 6.1013% | 25.1963% | 6.7281% | yes | 1.841% | 7 / 63 |
What the stock pickers sold
Portfolio book, rebalanced quarterly · 4 constructions · 81 names held · selection: reselect · 0.0% in cash · turnover 7.5× · cost drag 1.27%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 2.43% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2023-10-01 → 2024-01-01 | -18.2554% | -0.3342% | 21.6561% | 14.4437% | yes | 2.4266% | 1 / 62 |
| 2024-01-01 → 2024-04-01 | -17.5603% | 2.4479% | 24.8066% | 12.686% | yes | 2.3297% | 0 / 60 |
| 2024-04-01 → 2024-07-01 | -12.3579% | 2.0431% | 18.9156% | 1.0262% | yes | 1.7083% | 1 / 62 |
| 2024-07-01 → window end | -11.6405% | 3.3624% | 19.2575% | 5.1154% | yes | 1.5901% | 4 / 63 |
Step 19 · 2024-10-01 → 2025-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 101 names held · selection: reselect · 0.0% in cash · turnover 8.8× · cost drag 1.49%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.91% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2024-10-01 → 2025-01-01 | -11.7395% | 7.1684% | 27.9256% | 3.1202% | yes | 1.965% | 2 / 63 |
| 2025-01-01 → 2025-04-01 | -7.4215% | 6.5106% | 20.1187% | -4.6327% | yes | 1.5579% | 7 / 59 |
| 2025-04-01 → 2025-07-01 | -8.3301% | 3.7589% | 18.7813% | 8.9597% | yes | 1.6799% | 8 / 61 |
| 2025-07-01 → 2025-10-01 | -10.9728% | 4.4859% | 20.9152% | 4.0467% | yes | 1.7953% | 0 / 63 |
| 2025-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 77 names held · selection: reselect · 0.0% in cash · turnover 8.8× · cost drag 1.5%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 6.1% of 246 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2024-10-01 → 2025-01-01 | -8.8503% | 5.6714% | 20.9251% | 4.1182% | yes | 1.6345% | 1 / 63 |
| 2025-01-01 → 2025-04-01 | -7.7597% | 8.0669% | 23.7874% | -3.9574% | yes | 1.8047% | 8 / 59 |
| 2025-04-01 → 2025-07-01 | -8.8498% | 2.0551% | 15.4525% | 10.307% | yes | 1.6216% | 6 / 61 |
| 2025-07-01 → 2025-10-01 | -10.89% | 8.3047% | 29.3962% | 11.565% | yes | 1.8934% | 0 / 63 |
| 2025-10-01 | no segment follows this rebalance, not scored | ||||||
Step 20 · 2025-10-01 → 2026-10-01
What the stock pickers bought
Portfolio book, rebalanced quarterly · 5 constructions · 109 names held · selection: reselect · 0.0% in cash · turnover 8.2× · cost drag 1.4%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 4.45% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2025-10-01 → 2026-01-01 | -11.6789% | 5.8145% | 24.7751% | 2.0846% | yes | 1.893% | 3 / 63 |
| 2026-01-01 → 2026-04-01 | -9.0552% | 3.9287% | 17.3251% | -3.7878% | yes | 1.3716% | 4 / 60 |
| 2026-04-01 → 2026-07-01 | -10.2135% | 4.2234% | 22.6438% | 12.4007% | yes | 1.703% | 2 / 61 |
| 2026-07-01 → 2026-10-01 | -10.5271% | 8.6074% | 29.6073% | -1.9309% | yes | 2.1147% | 2 / 63 |
| 2026-10-01 | no segment follows this rebalance, not scored | ||||||
What the stock pickers sold
Portfolio book, rebalanced quarterly · 5 constructions · 99 names held · selection: reselect · 0.0% in cash · turnover 9.2× · cost drag 1.57%
Projection accuracy, realized outcome fell inside the P5–P95 cone in 100.0% of 4 scored rebalances (a well-calibrated 90% band contains ~90.0%) · 95% VaR breached on 4.05% of 247 days (expected ~5.0%)
| Rebalance | P5 | Median | P95 | Realized | In band | VaR 95 (1d) | Breaches |
|---|---|---|---|---|---|---|---|
| 2025-10-01 → 2026-01-01 | -10.7174% | 6.6013% | 25.3115% | 7.1694% | yes | 1.8118% | 1 / 63 |
| 2026-01-01 → 2026-04-01 | -9.7771% | 5.2934% | 21.1572% | 0.0914% | yes | 1.6511% | 8 / 60 |
| 2026-04-01 → 2026-07-01 | -10.8859% | 2.4796% | 19.3667% | 3.655% | yes | 1.7124% | 1 / 61 |
| 2026-07-01 → 2026-10-01 | -12.577% | 2.2149% | 17.8787% | 3.829% | yes | 1.6928% | 0 / 63 |
| 2026-10-01 | no segment follows this rebalance, not scored | ||||||